
How old is your house? If you live in the United States, chances are high that it has some age on it. According to recent data from the National Association of Home Builders, the average U.S. residence was built 42 years ago. That represents a significant aging
of the national housing stock when compared with historical baselines; as recently as 2005, the average American home was just 31 years old.
Furthermore, the pipeline for fresh inventory is remarkably constricted. The share of houses built in the past 10 years has dropped steeply from 18% in 2014 to a meager 13% today. To put this building slump into a broader historical perspective, new home construction starts are currently lower than they were in 1970, even though the total U.S. population has expanded by approximately 140 million people in the intervening decades.
The fundamental issue is simple arithmetic: the country is simply not building enough new places for people to live. At the root of this supply crisis are strict state and local zoning laws. Current property owners frequently lobby their elected representatives to block new developments, expressing deep resistance to having their local communities crowded with newcomers on quarter-acre lots or multi-family complexes.
Lately, however, this perennial zoning hurdle has been compounded by three formidable economic and policy obstacles that have brought residential real estate activity to a near standstill.
First, the mortgage rate lock-in effect has paralyzed the secondary market. Homeowners who might otherwise consider selling their current properties and moving are deterred by the prospect of trading a historical, low-rate mortgage for a new loan carrying interest rates of 7% or higher.
Second, construction costs have soared dramatically. This surge has been driven in large part by tariffs on vital building materials such as lumber, alongside acute worker shortages. These labor constraints have been further exacerbated by stricter immigration enforcement policies and an unexpected national boom in data-center construction, which competes directly for the same skilled trade labor pool.
Third, the general squishiness and sluggishness of the broader economy have weighed heavily on real estate. Home prices have actually fallen in real, inflation-adjusted terms for 13 consecutive months, creating a climate of uncertainty for both buyers and sellers.
A Languishing Housing Market
Residential sales are currently moving at a snail’s pace. Market prices are caught in an awkward limbo: they are not low enough to lure hesitant potential buyers off the sidelines, nor are they high enough to inspire potential sellers to list their homes.
The financial markets have reflected this prolonged malaise. The S&P Select Industry Homebuilders Index has delivered an anemic annual average return of just 7.3% over the past five years, lagging far behind the broader S&P 500 Index, which has posted a 13.8% annual return over the same timeframe. Over the most recent 12-month period, the homebuilders index trailed the S&P 500 by a staggering 28.1 percentage points.
Yet, in the eyes of savvy long-term investors, all of this persistent bad news is already baked into current stock prices, opening the door to potentially attractive opportunities.
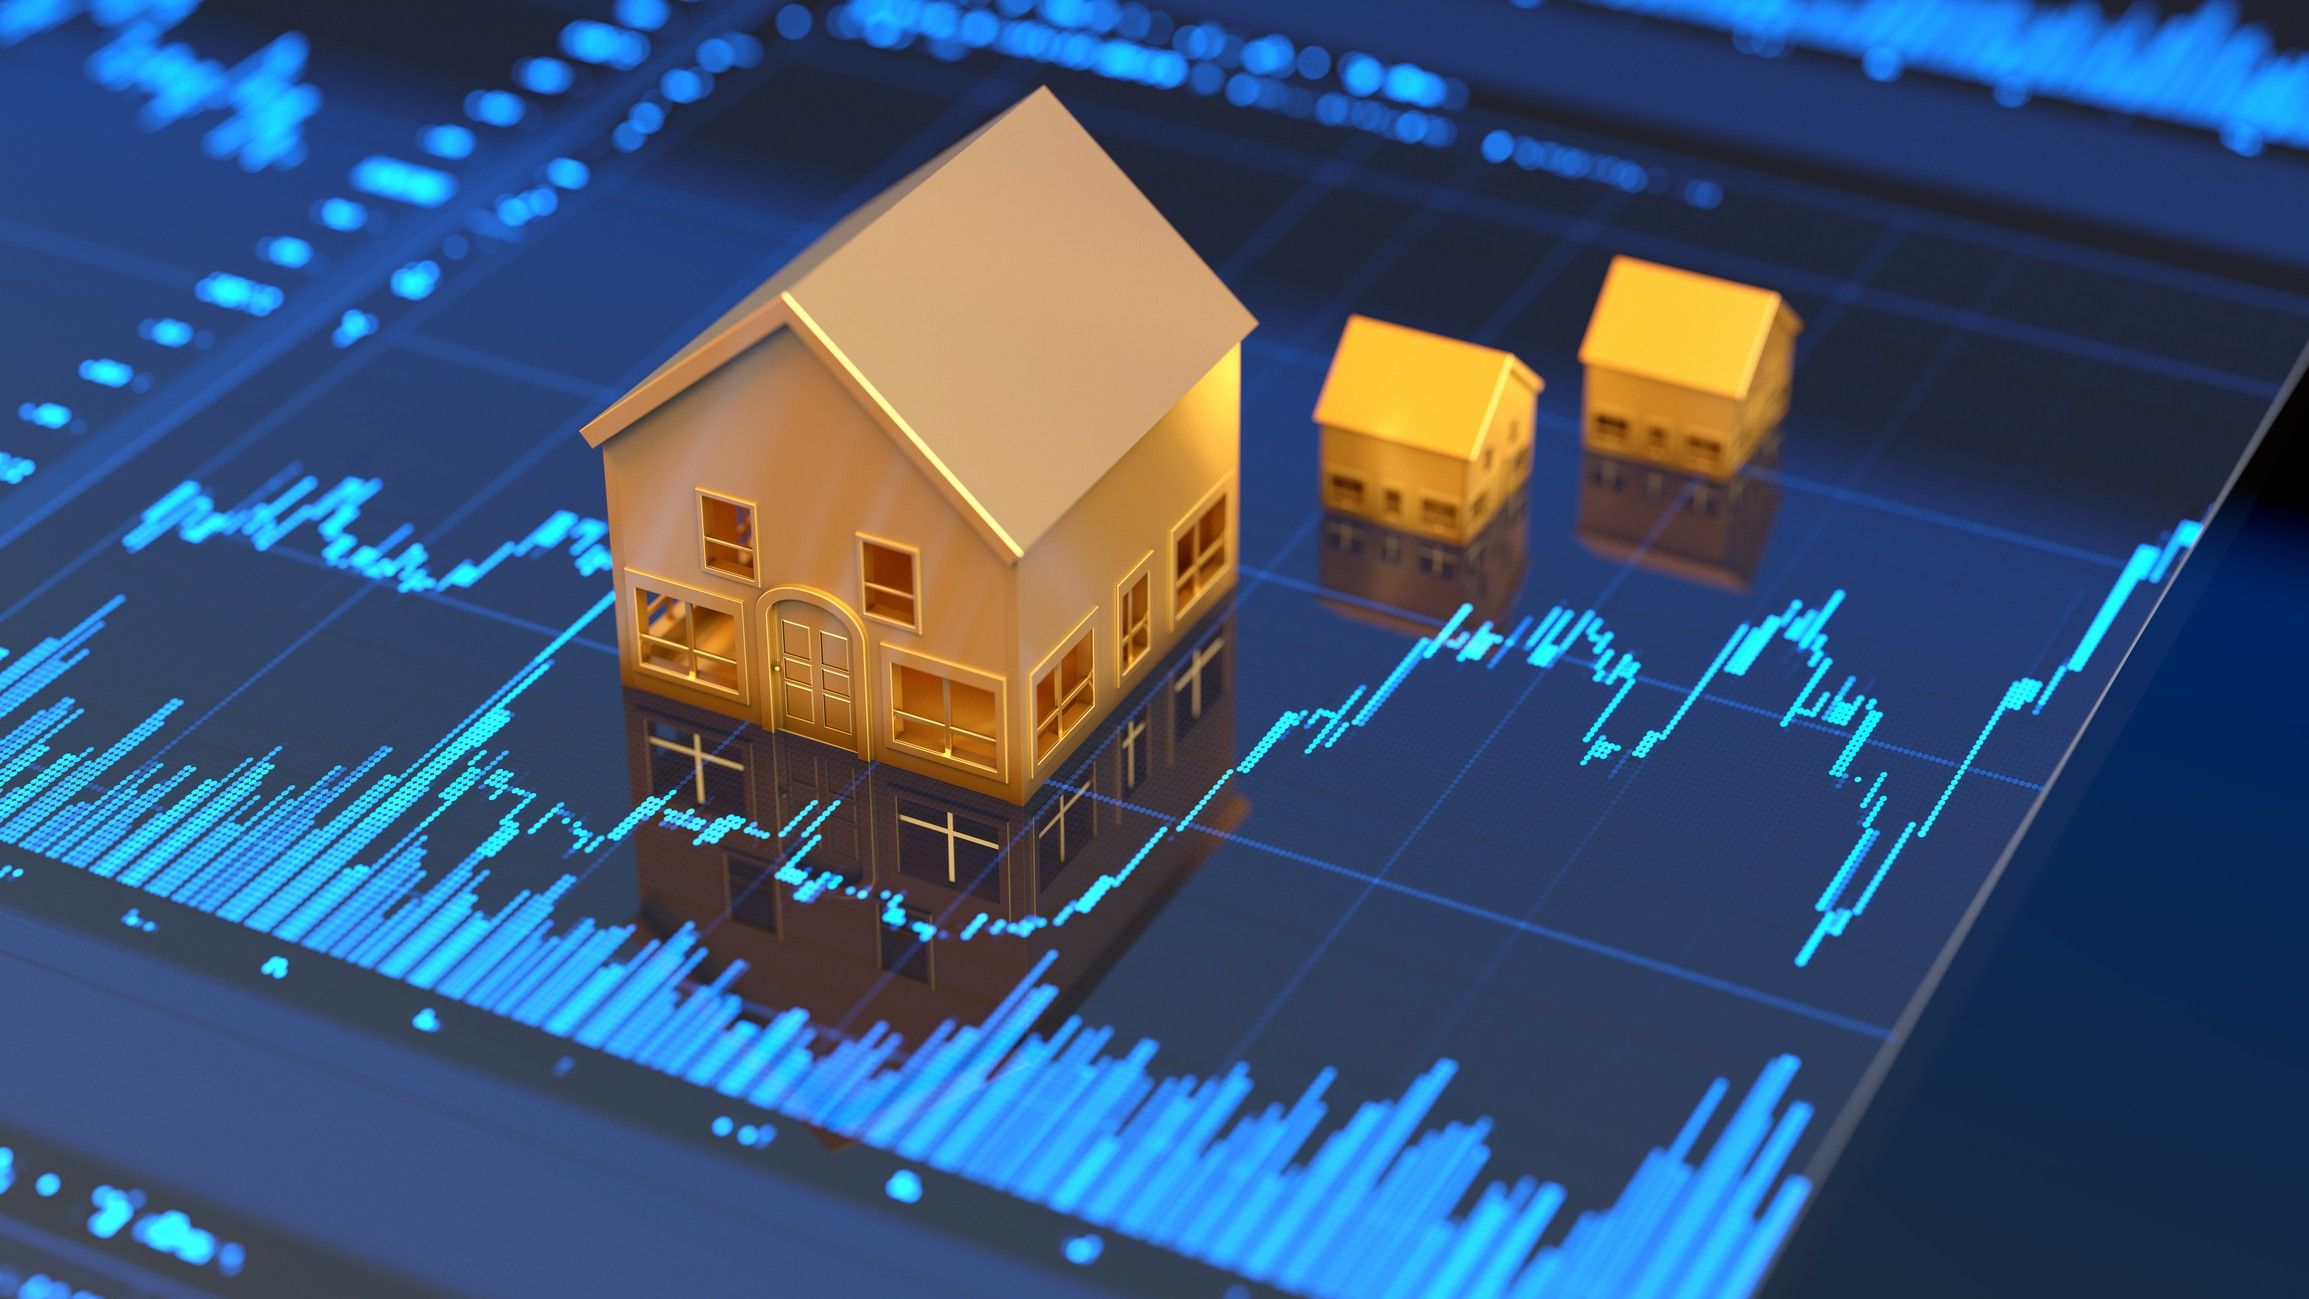
Warren Buffett and his successor as CEO of Berkshire Hathaway, Greg Abel, appear to share this contrarian view. From the beginning of 2025 through September 2026, Berkshire aggressively accumulated an 11% stake in Lennar, one of the nation’s premier homebuilders, as the company’s stock price slid from $126 down into the low $80s.
Lennar, boasting a market value of roughly $20 billion, has seen its market valuation cut by more than half over the past two years. Despite the industry downturn, the company trades at a modest price-to-earnings ratio of 16, maintains a remarkably strong balance sheet, and retains an established, dominant footprint in high-demand migration markets across Florida, Texas, and Tennessee.
The acquisition spree has not stopped there. In July, under Abel’s leadership, Berkshire Hathaway acquired Taylor Morrison, an Arizona-based homebuilder, for $8.5 billion, a figure that included the assumption of existing debt. Berkshire has also built notable positions in other industry leaders, including Virginia-based NVR and Texas-based D.R. Horton, which stands as the largest homebuilder in the country by revenue.
Shares of NVR have experienced a drop of about one-third over the past two years, while D.R. Horton has weathered the storm slightly better. While Berkshire’s aggressive buying in the sector should offer a measure of confidence to retail investors, market observers note a vital caveat: the conglomerate has made notable missteps in the past, such as its historical investment in US Airways, and operates with a famously long-term investment horizon.
Predicting the exact timing of when American consumers will return to the housing market in full force is difficult, meaning these equities are best viewed as long-term holdings. Nevertheless, industry observers argue that a revival in home building is practically guaranteed. Demography demands it, and so do advancing technology, macroeconomic pressures, and shifting political realities.
The national homeownership rate peaked in 2004 at 69% but has since drifted downward to 65%, where it continues to face downward pressure. Consequently, political pressure is mounting on lawmakers to adopt what housing policy experts Arthur Gailes and Edward Pinto of the American Enterprise Institute term "housing abundance" policies. A growing number of state legislatures are actively considering regulatory reforms that would permit smaller lot sizes, while parallel proposals for federal home-buying tax credits circulate in Congress.
On the technological front, the construction sector is ripe for disruption. Calculations by Goldman Sachs indicate that productivity in the U.S. home-building industry has actually declined at an average rate of 0.6% annually since 1965, contrasting sharply with the broader economy, where productivity has risen by 1.6% a year over the same period. The persistent shortage of construction labor may ultimately serve as the catalyst that forces the industry to adopt faster, cheaper, and more efficient building methods.
The Ripple Effect on Home Improvement
Given that home building and home buying have largely stalled, conventional wisdom might suggest that the home-renovation sector would flourish as people choose to fix up their current residences instead of moving. However, consumer spending patterns reveal a different reality: people tend to spend the most money on home improvements when they move into a new property, not when they feel financially stuck in their existing homes. Furthermore, higher interest rates have weighed heavily on renovation activity, as homeowners typically rely on borrowed capital to finance major remodeling projects.
Consequently, shares of Home Depot, the world’s dominant home-improvement retailer serving both do-it-yourself consumers and professional contractors, have suffered a brutal downturn. The stock has fallen 29.1% over the past year and sits more than $140 per share below its late-2024 high. Its smaller competitor, Lowe’s, has endured a similarly punishing trajectory.
Home Depot remains an absolute retail behemoth, commanding a market capitalization of $284 billion—a figure that is double the combined market value of all 19 publicly traded homebuilder stocks. In August, the company announced its 158th consecutive quarterly dividend payout, though the distribution was frozen at its previous rate to mirror the stagnant broader housing market. Even so, the stock continues to offer a respectable dividend yield of 3.2%.
For investors seeking exposure to a potential residential real estate recovery without picking individual builder stocks, Home Depot presents a compelling vehicle. Even if home sales experience a prolonged slide, homeowners will continue to require maintenance supplies, ensuring a steady baseline of business across the chain’s 2,364 retail locations.
Consider a Real Estate Fund
For investors looking to diversify away from individual equities, several exchange-traded funds offer broad exposure to the residential real estate ecosystem.
Home Depot is one of 35 companies held in the portfolio of the State Street SPDR S&P Homebuilders ETF. This exchange-traded fund utilizes an equal-weighting methodology, ensuring that a handful of massive stocks cannot overly dominate the fund’s performance. The portfolio includes major homebuilders alongside manufacturers of heating and cooling systems, window glass, paint retailers, kitchenware brands, and household appliance makers.
While there is no pure homebuilder play available via a single fund, this ETF carries an expense ratio of 0.35%, and nearly all of its underlying components stand to benefit from a broader housing market rebound.
Another large industry alternative, the iShares U.S. Home Construction ETF, features an expense ratio of 0.37% and holds a similarly sized portfolio of roughly three dozen stocks. However, it relies primarily on market-cap weighting with a formula that gives preference to dedicated homebuilders. As a result, the five largest builders account for about half of the fund’s total assets, while Home Depot and Lowe’s combined make up just 8% of the portfolio. Despite their structural differences, both funds have historically produced comparable, albeit modest, five-year average annual returns of a little under 7%.
A much smaller specialized option, the Hoya Capital Housing ETF, carries an expense ratio of 0.30% and holds a highly diversified, evenly weighted portfolio of 100 companies that includes several niche segments. Traditional homebuilders and building-materials companies make up roughly 30% of the fund’s assets, matching an equally sized allocation in apartment real estate investment trusts, including senior-living specialist Welltower.
The remainder of the fund’s holdings is distributed across home improvement and furnishing companies, mortgage lenders, and self-storage REITs such as Public Storage.
Ultimately, while the exact timeline for a housing market turnaround remains uncertain, market fundamentals suggest that home building is bound to stage a recovery. For investors willing to look past current headwinds, the sector offers compelling long-term potential.
No comments yet. Be the first to join the conversation!