
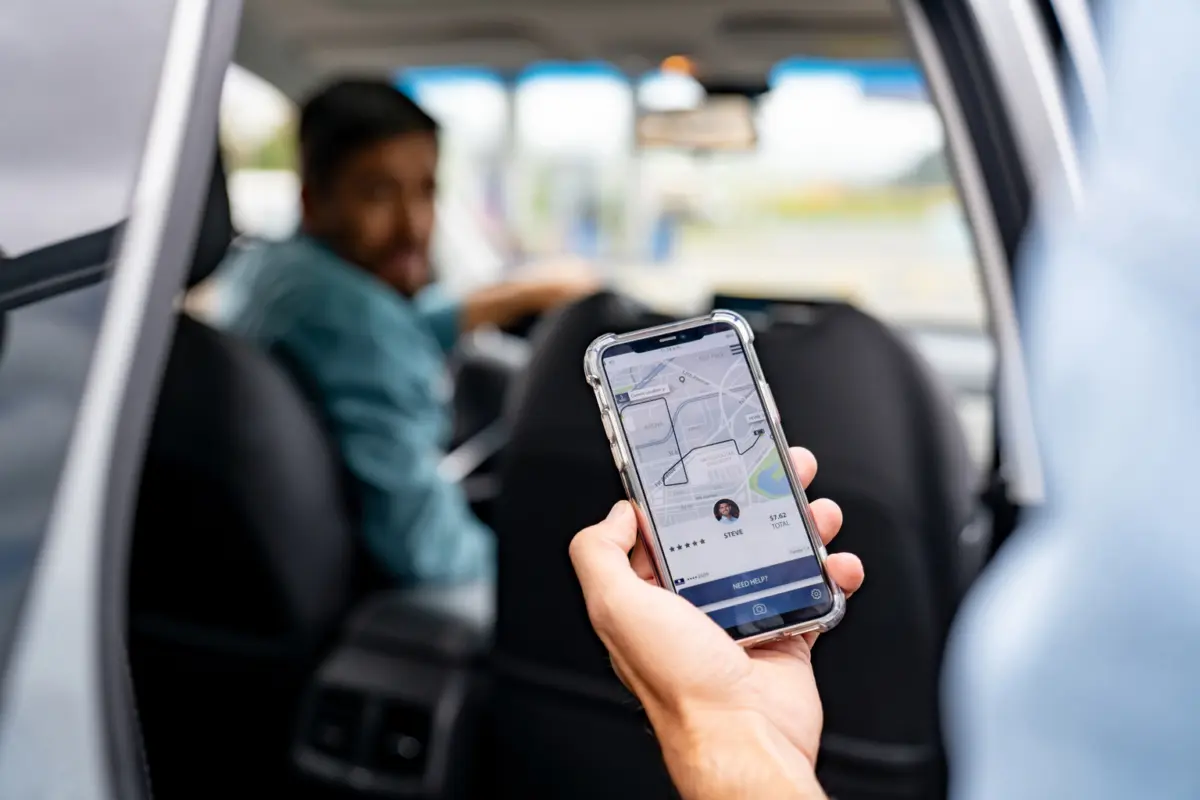
The foundational thesis for Uber’s robust market outlook stems from an initial coverage report published in August, which assigned a Buy rating to the shares alongside an ambitious fair value target of $130. At the time of that initial assessment, Uber’s stock was trading at $76.83, creating a wide margin between market price and projected valuation. This valuation gap has since remained a focal point for institutional investors and independent analysts monitoring how the company scales its operations, optimizes its cost structures, and capitalizes on secular shifts in urban transportation and consumer delivery habits.
To understand the mechanics driving such a substantial fair value estimate, market observers must look closely at how Uber’s growth metrics are currently priced by the broader financial community. According to recent equity research and market commentary, the market’s prevailing valuation models may be significantly underestimating the true magnitude of Uber’s future cash flow generation. When breaking down the core drivers—namely, the continuous scaling of the Mobility segment, the resilient profitability of the Delivery division, and the rapid maturation of its high-margin advertising business—analysts argue that the company’s actual growth potential is being valued at a fraction of its true economic output.
The evolution of Uber from a disruptive ride-hailing startup into a diversified global technology platform has fundamentally transformed its risk-and-reward profile. In its early years, the company faced intense skepticism regarding its path to profitability, as massive investments in driver incentives, market expansion, and legal battles consumed vast amounts of capital. However, the post-pandemic recovery and subsequent strategic pivot toward disciplined capital allocation have yielded a dramatically different financial reality. Uber has consistently demonstrated operating leverage, proving that as gross bookings expand, corporate overhead and operational expenses scale at a much slower rate, thereby driving meaningful free cash flow.
A critical component of this financial turnaround is the diversification of Uber’s revenue streams. While ridesharing remains the bedrock of the company’s identity, the Uber Eats delivery network has matured from a pandemic-era lifeline into a permanent, highly efficient logistics powerhouse. Furthermore, the integration of autonomous vehicle partnerships into the platform represents a potentially transformative frontier. By positioning itself as a neutral network orchestrator that can seamlessly connect consumers with both human-driven vehicles and autonomous fleets, Uber mitigates the capital expenditure risks associated with building driverless hardware while capturing the transaction fees.

Despite these strong operational tailwinds, the stock’s valuation journey has not been without short-term complexities. Market sentiment frequently fluctuates in response to broader macroeconomic indicators, interest rate expectations, and regulatory scrutiny surrounding gig-economy labor classifications. These external variables often create temporary dislocations between Uber’s fundamental business performance and its share price, presenting strategic entry or exit windows for market participants. For instance, recent disclosures from analysts covering the stock indicate active portfolio monitoring, including considerations of hedging strategies or tactical positioning, reflecting the dynamic nature of managing large-cap growth equities in a volatile macroeconomic environment.
The disclosure statements accompanying these financial analyses highlight the rigorous adherence to professional standards and transparency required in modern equity research. Analysts publishing opinions on platforms like Seeking Alpha routinely clarify their current market positions—whether holding long shares, exploring derivative strategies, or operating independently without commercial ties to the corporate entities they cover—ensuring that readers have full context regarding potential conflicts of interest. In the case of Uber, the independent nature of these evaluations underscores the growing divide between bearish short-term trading sentiment and bullish long-term fundamental models.
As investors look ahead to upcoming quarterly earnings reports and strategic updates from management, the core debate centers on execution. The $130 fair value target established in August serves as a benchmark for what is achievable if Uber successfully executes its multi-year strategic roadmap without major regulatory or economic disruptions. Achieving this target will require sustained double-digit growth in gross bookings, further margin improvements in the delivery sector, and the successful scaling of emerging monetization channels such as in-app advertising and enterprise logistics solutions.
Ultimately, Uber’s market standing reflects a broader maturation phase for the platform economy. Companies that successfully transitioned from cash-burning disruptors into cash-generative monopolies are now being judged on their ability to compound earnings over long horizons. Whether the broader market will eventually close the valuation gap and align with the more aggressive growth projections remains one of the most closely watched narratives in the technology and transportation sectors. For now, the analytical consensus highlights a compelling disconnect between current market pricing and the underlying financial power of Uber’s global platform.
No comments yet. Be the first to join the conversation!