
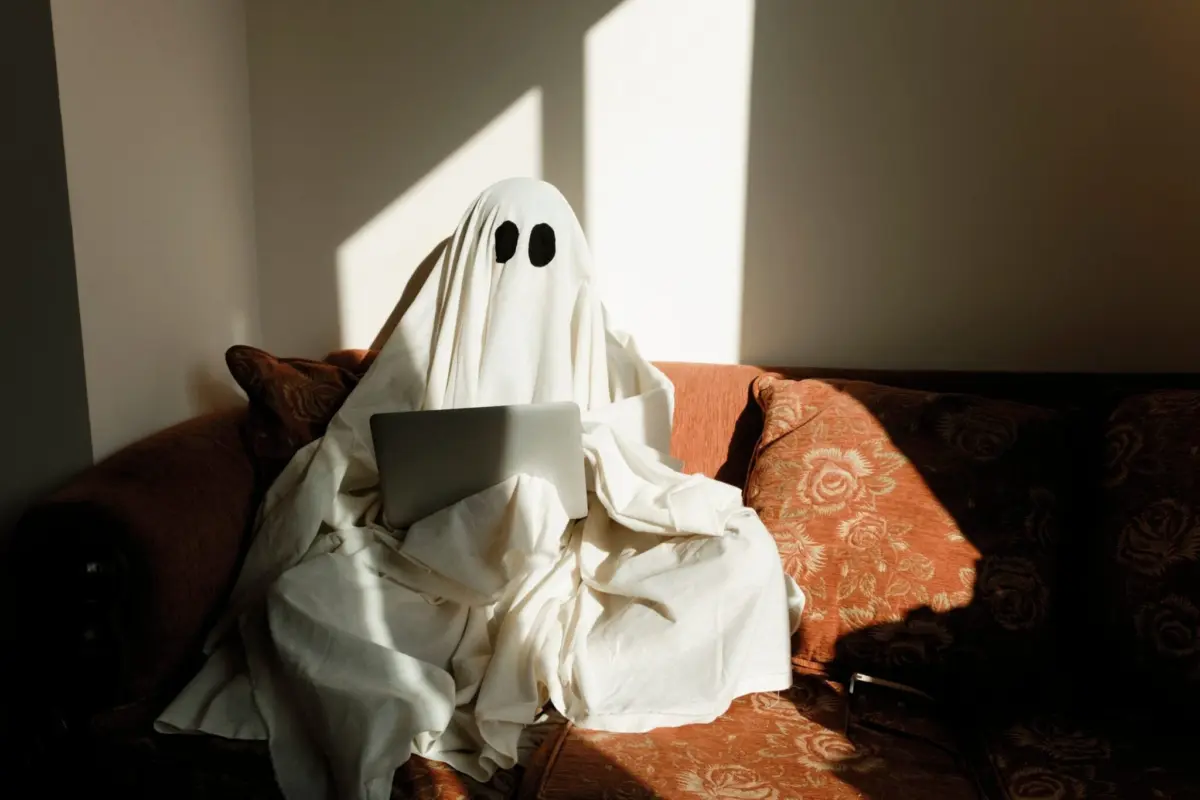
Most people are familiar with the modern phenomenon of being ghosted in the dating world. One day, a romantic interest is showering you with attention, and the next, there is total silence. But according to financial planners and wealth management experts, many consumers are turning this exact behavior inward, directing it toward their own bank accounts, credit cards, and long-term financial futures.
When thinking about money becomes too stressful, overwhelming, or anxiety-inducing, a significant portion of the population simply turns away. They leave bank statements unopened, ignore notifications from financial apps, and avoid logging into their accounts for weeks or even months at a time. This pattern of avoidance has become a silent epidemic in personal finance, leading to compounding monetary problems that only deepen the initial cycle of stress.
Steven Conners, founder and president of Conners Wealth Management in Scottsdale, Arizona, points out that this behavior quickly morphs into a destructive psychological cycle. It is remarkably easy to get caught up in a negative feedback loop where an individual experiences acute stress over mounting bills, and subsequently walks away from the problem simply to make themselves feel better in the short term.
The primary danger of financially ghosting oneself is that it creates a dangerous blind spot. Without active monitoring, it becomes effortless to overspend, quietly accumulate high-interest debt, or fall victim to spontaneous financial habits like doom spending. When people are not paying attention to their cash flow, minor budget leaks can easily transform into major financial crises.
Financial professionals across the country are now urging consumers to confront this avoidance behavior, offering strategies to break the ice with their own finances, regain control, and lower overall economic anxiety.
Log in and look around
The first step in ending the silent treatment with your money is often the hardest: breaking the seal and actually looking at the data. For individuals who have spent months avoiding their bank, credit card, and investment accounts, carving out dedicated time to dig into the numbers is essential for a financial reset.
Wanda Belle, an accredited financial counselor and founder of Belle Financial Services in the Atlanta area, recommends printing out physical paper statements whenever possible. Holding the numbers in your hand can make it significantly easier to comb through transactions systematically rather than getting distracted by digital interfaces.
When reviewing these statements, Belle suggests highlighting any expenses that come as a surprise. Crucially, she encourages people to approach this review process while actively avoiding judgment or shame. The goal of this initial audit is not to punish oneself for past behavior, but rather to bring objective awareness back to the numbers.
Set some achievable goals
Once an individual has successfully reviewed their spending patterns from the previous month or two, Belle advises channeling that newfound awareness into establishing realistic, achievable goals for the coming months. Instead of attempting a complete financial overhaul overnight, consumers might choose to focus on a modest target, such as decreasing restaurant spending by a specific amount or keeping online shopping expenditures under a strict threshold.
When selecting targets for improvement, Belle emphasizes focusing primarily on variable expenses because individuals maintain a much higher degree of control over them. These are the costs that fluctuate naturally from month to month, such as grocery bills, rideshare services, or dining out. Because they are malleable, they are substantially easier to trim back compared to fixed expenses like rent, mortgage payments, or auto loans.
Take a look at the big picture
Beyond day-to-day spending, wealth management professionals stress the importance of examining the broader financial landscape. This means taking a comprehensive look at outstanding loans, long-term investments, retirement accounts, and overall asset accumulation.
Jason Bernat, president and CEO of American Financial Services, a wealth management company in Boardman, Ohio, regularly walks clients through this exact process when they return after long periods of account neglect. When clients feel overwhelmed by their financial reality, Bernat sits down with them to go over all current bills, outstanding loans, and available assets to explicitly identify which specific elements cause the highest levels of stress. Once those pain points are clearly mapped, the advisory team can work backward to determine the most logical place to begin intervention.
That initial step does not need to be monumental. It could be as straightforward as opening a new retirement account, setting up an automatic transfer, or increasing contribution percentages to an existing employer-sponsored plan. Alternatively, it might involve identifying a single lingering balance that has been ignored for too long and mapping out a strategy to clear it.
Dial down debt and ramp up savings
Because debt frequently acts as a primary catalyst for money-related anxiety, Bernat suggests prioritizing the reduction of high-interest credit card debt by utilizing any financial breathing room or savings generated from recent spending adjustments. Attacking and shrinking this type of debt makes every other aspect of personal finance significantly more manageable over the long term.
Simultaneously, financial experts emphasize the necessity of continuing to build up liquid cash reserves. Establishing and growing an emergency savings fund serves as a crucial financial buffer, protecting consumers from being forced to take on additional, high-interest debt when unexpected life events occur, such as emergency car repairs or sudden medical bills.
Both paying down burdensome debt and accumulating an adequate emergency fund require sustained effort and time. Bernat cautions against the trap of trying to fix every financial imperfection over the course of a single weekend, recommending instead that individuals pick just one financial issue that is creating the most acute stress and focus on that single metric first.
Calm your nervous system
For many individuals, the resistance toward money management tasks stems from a deep-seated emotional response. The physiological stress associated with reviewing debt and bills can trigger a powerful fight-or-flight reaction, which explains why so many people choose avoidance. To counteract this barrier, Conners suggests pairing routine financial work with a calming physical activity to help regulate the body’s nervous system.
Over years of client interactions, Conners has observed that it is significantly easier to manage intense emotions surrounding money when individuals utilize a physical coping mechanism, such as working out at the gym, swimming, or taking a long, uninterrupted walk. Engaging in physical exertion helps flush tension and anxiety out of the body’s system.
Operating from a calmer physiological state makes it vastly easier to tackle difficult administrative tasks. For those who prefer non-athletic outlets, alternative calming activities such as listening to music, watching a favorite film, or engaging in crafts like knitting can serve a similar grounding purpose. Conners notes that simple adjustments—like putting on a favorite jazz playlist while paying bills, checking a banking app during a relaxing stroll, or enjoying a comforting beverage before sitting down to review a budget—can radically alter the emotional experience of managing money.
Track your progress
As the initial fear of financial intimacy begins to fade, consumers find themselves better equipped to maintain a consistent watch over their cash flow. Documenting spending habits and checking in periodically throughout the month helps ensure that behavior remains aligned with newly established financial goals.
Belle recommends reviewing updated statements at the end of each monthly cycle. If targeted goals were successfully met, individuals can reward themselves by choosing a new, constructive category to focus on for the following month. If the targets were missed, the process should not be viewed as a failure, but rather as an opportunity to commit to different adjustments and try again.
Whether the month ends in a triumph or a setback, the core objective is achieved: the individual remains acutely aware of where their money is flowing and becomes inherently more intentional about future purchases. By maintaining this continuous awareness, consumers take active control of their financial lives rather than leaving their money to drift away in silence.
No comments yet. Be the first to join the conversation!