
By Jonathan Small | Edited by Dan Bova
November 02, 2026
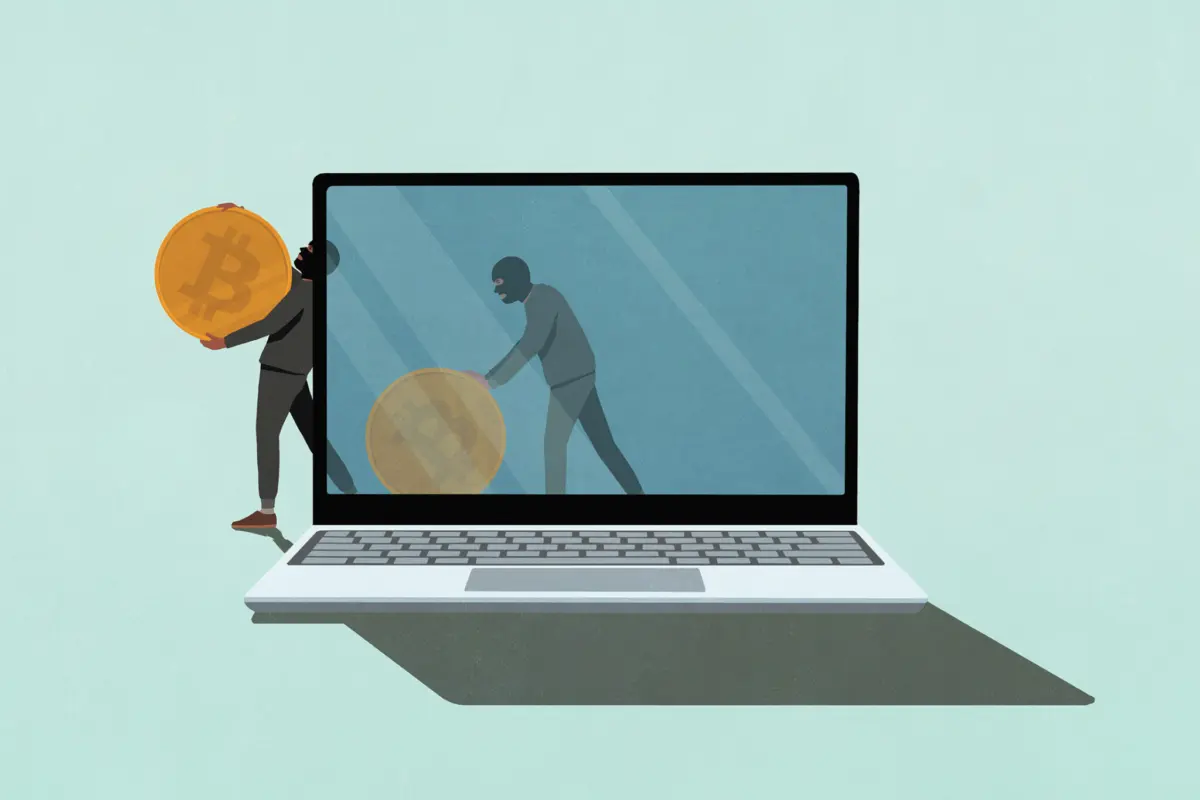
In what has officially been verified as the largest cryptocurrency heist in history, hackers breached Binance, the world’s leading digital asset exchange, making off with an astonishing $6.3 billion in digital coins. The massive security breach has sent shockwaves through the global financial technology sector, triggering swift regulatory scrutiny, a high-stakes investigation by federal law enforcement, and immediate fallout regarding user trust and platform liquidity.
According to reports from The New York Times, the sophisticated attack bypassed multiple layers of security to drain digital assets on a scale never before witnessed in the history of blockchain technology. Federal authorities moved quickly to identify the culprits behind the staggering cybercrime. The Federal Bureau of Investigation (FBI) has publicly laid the blame for the security breach squarely on North Korea’s notorious TraderTraitor hacking unit, a state-sponsored cyber espionage group known for targeting decentralized finance protocols and cryptocurrency exchanges to fund the regime’s illicit programs. Furthermore, blockchain analysis firm Chainalysis noted that the sophisticated attackers may have leveraged artificial intelligence tools to accelerate the execution of the hack, highlighting an alarming evolution in the capabilities of state-backed cybercriminal syndicates.
Despite the unprecedented scale of the theft, Binance moved rapidly to contain the panic and reassure its vast user base. The exchange promised to cover all user losses out of its own reserves to prevent a catastrophic collapse of confidence. According to reports from NBC News, Binance has already successfully replaced 90 percent of the stolen funds, demonstrating a massive liquidity buffer designed to weather the storm and keep the platform solvent in the wake of the disaster.
However, the psychological impact on customers was immediate. As soon as the platform resolved its technical lockdown and withdrawals were officially reopened, a substantial portion of the user base decided they were ready to part ways with the exchange. Since Sunday, data shows that nervous users pulled approximately $4.65 billion from their accounts. Concurrently, the platform saw $1.01 billion in fresh deposits, resulting in a net outflow of $3.64 billion. The vast majority of these withdrawals occurred during the chaotic opening hours following the restoration of platform access, as panicking traders rushed to transfer their assets to rival exchanges or self-custody wallets.
Despite the multi-billion-dollar exit of capital, Binance executives have sought to contextualize the numbers against the platform’s massive overall holdings. Company representatives pointed out that the net outflow represents a mere 2.1 percent of the total $171 billion in assets that the exchange currently manages. According to internal metrics provided by the company, overall trading and platform activity has since stabilized, and the vast majority of account holders chose to keep their funds within the ecosystem rather than flee.
The incident has reignited intense debates across the digital asset industry regarding cybersecurity preparedness, the vulnerability of centralized exchanges to nation-state actors, and the growing intersection of artificial intelligence and advanced cyber warfare. As regulatory bodies around the world review the implications of the multi-billion-dollar breach, security experts are urging both centralized and decentralized platforms to drastically upgrade their defensive architectures to counter increasingly sophisticated threats from state-backed actors like North Korea’s TraderTraitor unit.
Binance co-founder Changpeng Zhao took to social media on Sunday to address the community directly, emphasizing the importance of accountability and operational resilience during times of crisis. In a post published on X, Zhao wrote that trust is not earned by what a company says during prosperous times, but rather by what actions it takes when faced with extreme adversity. He highlighted that despite the initial panic and the billions withdrawn in the first twelve hours, roughly 98 percent of the exchange’s capital and user base chose to stay, expressing gratitude to the community for their enduring confidence as the platform works to fully recover from the historic breach.
No comments yet. Be the first to join the conversation!