
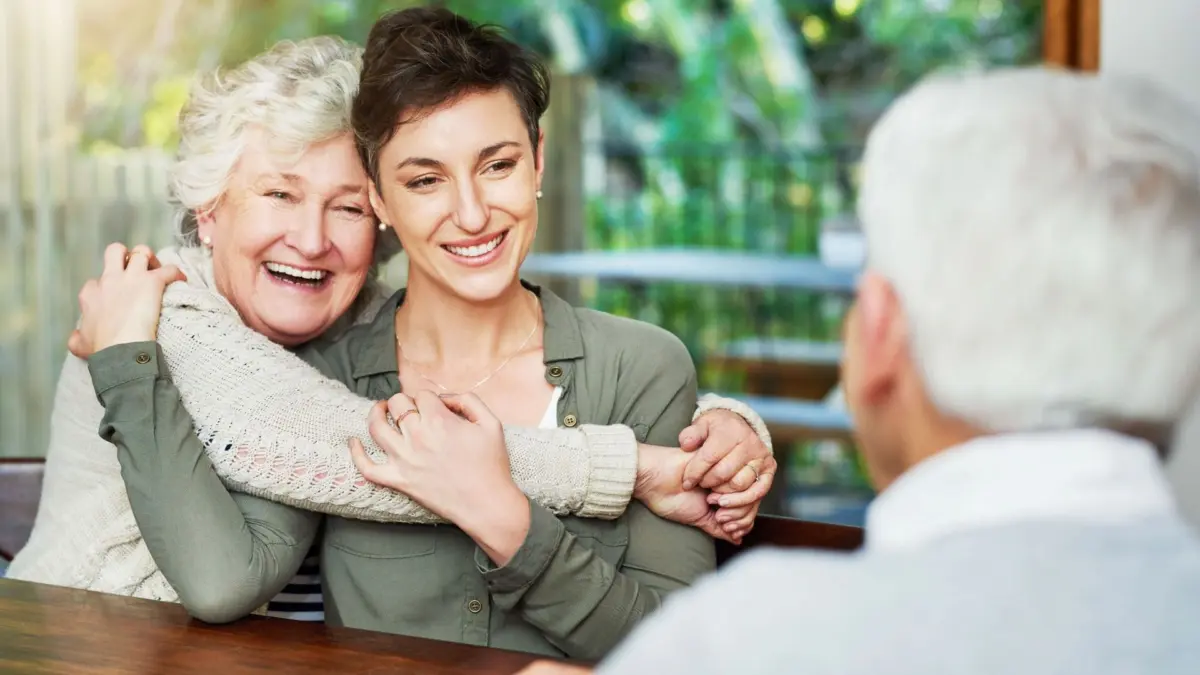
When discussions turn toward the massive generational shift known as the great wealth transfer, public and private attention typically gravitates immediately toward the numbers. Families, financial planners, and media outlets frequently obsess over the sheer scale of the assets involved: Exactly how much accumulated family wealth will pass from older generations to the next? How should those portfolios, real estate holdings, and liquid accounts be divided equitably among heirs?
Yet, this relentless focus on quantitative metrics frequently obscures how deeply complicated, emotionally charged, and highly personal the actual wealth transfer process truly is. At its core, the transition of generational wealth involves delicate, often difficult conversations about human aging, sickness, declining health, and mortality. It requires aging parents and benefactors to realistically evaluate how equipped their children and designated heirs actually are to receive substantial assets, manage complex portfolios, or take on significant administrative and fiduciary responsibilities.
Fundamentally, it means confronting difficult questions that many families would naturally prefer to put off until a crisis forces their hand. However, ongoing procrastination carries steep financial, operational, and emotional costs that can ripple across generations.
According to a recent Bank of America study focusing on high-net-worth individuals, only 36% of ultra-high-net-worth respondents believe their heirs are genuinely prepared to handle a significant inheritance. Furthermore, the survey revealed that 40% of affluent families have already experienced, or actively expect to experience, serious family tension surrounding inheritance matters.
These acute challenges are by no means limited to the ultra-wealthy or the top tier of asset holders. Findings from a recent Kiplinger-Morning Consult survey reinforce the reality that wealth transfer complexities touch households across various economic brackets. Regardless of the exact monetary figures involved, families from all walks of life stand to benefit immensely from starting their inheritance preparations sooner rather than later, replacing avoidance with proactive engagement.
A truly successful wealth transfer is an ongoing, multifaceted process that requires vastly more than simply moving asset titles from one generation to the next. Alongside financial accounts, critical elements such as family knowledge, shared values, and long-term responsibilities are also being passed down. Despite this reality, financial professionals frequently observe far too many families focusing exclusively on the mechanical financial handoff while ignoring the human and informational elements.
Information Must Be Passed Down, Too
The foundational first step in any generational transfer is passing down essential operational information. Unfortunately, a significant number of donors and parents inadvertently keep their heirs entirely in the dark without realizing the operational burden they are creating. Unless a benefactor has clearly and patiently explained how the family’s financial life is managed on a daily basis, their children may find themselves completely unequipped to step in when a sudden transition becomes necessary.
Take a moment to consider who within your immediate family actually knows the fundamental logistics of your household. Do your children know where critical documents are stored, who your primary legal and financial advisers are, how your recurring liabilities are handled, or what your wishes are regarding long-term medical care?
If circumstances permit, financial planners strongly advise walking your heirs through at least some of these logistical details while the opportunity remains. Whatever temporary discomfort or awkwardness those conversations might create will pale entirely in comparison to the immense stress your children would face if they were forced to perform financial forensics on your life in the middle of an acute health crisis or while actively grieving your loss.
Prepare Heirs Before the Transition
Even a perfectly documented, legally bulletproof estate plan does not automatically prepare your heirs to step smoothly into the complex roles they may inherit. Beneficiaries need tangible opportunities to understand the weight of these responsibilities well before they are suddenly expected to assume them full-time.
This preparation can safely begin with small, manageable steps. Parents might eventually consider involving adult children in more consequential financial conversations and strategic decisions, offering them a secure environment to observe how wealth is managed, preserved, and deployed.
This gradual integration gives heirs a valuable opportunity to gain practical experience in the roles they may eventually assume. More importantly, it creates an open, communicative environment where parents can explain the underlying rationale and philosophy behind the specific choices they have made in their planning.
When a family owns an operating business, experts recommend proactively explaining the core values and historical sacrifices that shaped how the company was built and successfully operated. Similarly, if a family maintains a cherished vacation property that parents hope will remain in the family for decades to come, it is vital to talk openly about why that continuity matters and to discover whether the younger generation actually shares that long-term goal.
Such conversations can reveal misaligned expectations, differing priorities, and conflicting goals early in the process. Catching these discrepancies early leaves ample time to adjust the estate plan collaboratively, rather than leaving the next generation to sort out bitter disputes and resentment long after the parents are gone.
The most critical factor is initiating these dialogues while the transitioning generation is still fully capable of teaching, listening, and adjusting their strategies based on realistic feedback.
Every Family Has a Handoff to Plan For
Succession and continuity issues are considerations that every household should address, even if they are not handing down an operating commercial enterprise or a sprawling nine-figure estate. Naturally, ultra-high-net-worth families face complex decision points involving trusts, tax mitigation, and philanthropic foundations. However, all families—regardless of their net worth—must eventually decide who will manage day-to-day household finances, coordinate long-term medical and personal care, and communicate effectively with financial, legal, or healthcare professionals when aging parents are no longer able to do so themselves.
More Time Means More Choices
Regardless of what assets are being transferred or the total monetary value involved, the overarching advice for every family is to start thinking about these transition issues well in advance.
Unspoken assumptions often serve as the root cause of many succession failures. Children may harbor entirely different expectations regarding who should shoulder the physical burden of caregiving or how much financial support they will ultimately receive. Conversely, aging parents may assume they know precisely which child is best suited to manage investments or take over a family property, only to be surprised later to learn that the chosen child has little to no personal interest in carrying that heavy responsibility.
Left unmanaged, these divergent expectations can rapidly morph into corrosive family tension if the underlying plans are never discussed openly beforehand.
Families who begin the planning and communication process early afford themselves invaluable extra time. They can clearly articulate what is required, carefully consider which legal and financial structures best reflect their true intentions, and deliberately decide which family members are best suited to take on specific responsibilities.
This proactive approach does not mean parents need to disclose every granular detail of their current net worth or their confidential estate documents, which naturally evolve over time. Instead, by equipping family members with the basic tools, knowledge, and context they need to step into anticipated roles, benefactors provide their heirs with the confidence required to handle those responsibilities honorably and effectively when the time finally arrives.
No comments yet. Be the first to join the conversation!