
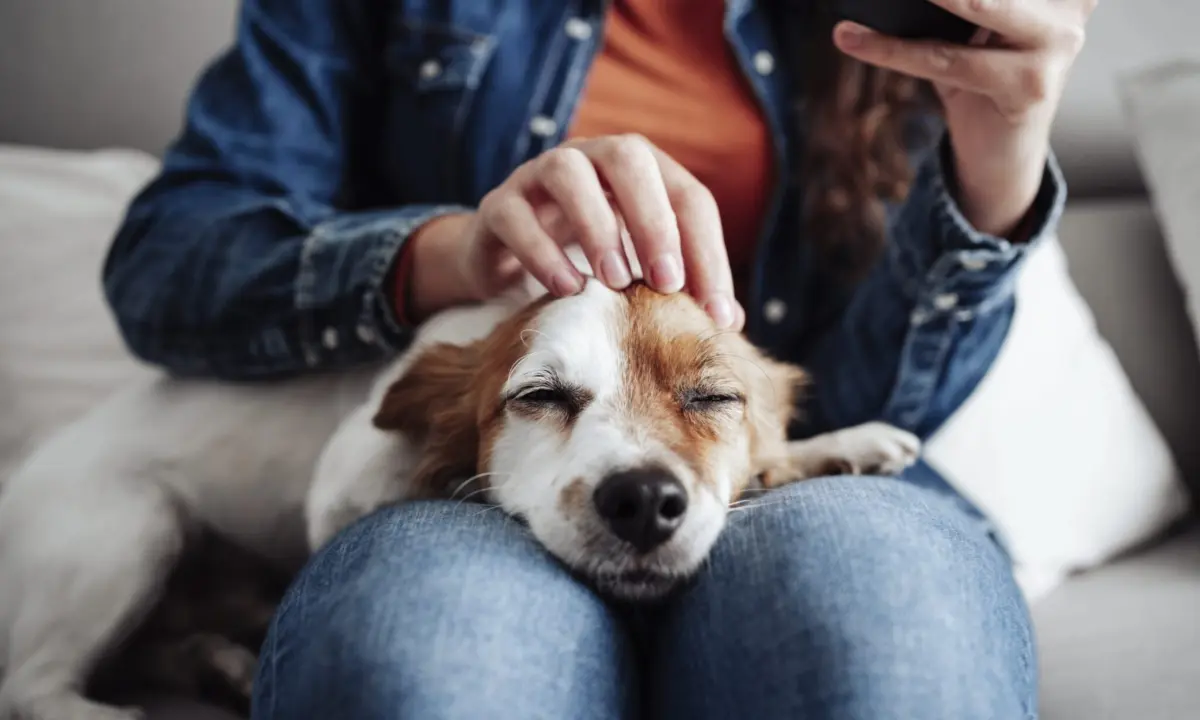
For millions of pet owners around the world, treating a dog or cat like a member of the family is simply second nature. It feels entirely natural to extend the same kind of careful financial planning and health protection to a furry companion that people routinely secure for human loved ones. Yet, for anyone who has shopped around for a pet insurance policy recently, the sticker shock can be jarring. Prospective policyholders frequently find themselves hesitating, questioning whether it makes economic sense to pay hundreds of dollars every year for an insurance product they may never actually utilize.
For a significant number of pet parents, the decision to invest in coverage is driven by long-term financial risk management—even when their animals are currently young, vibrant, and completely healthy. That persistent calculus is shaped heavily by how the pet insurance industry handles pre-existing conditions, a structural reality of the market that catches many owners off guard when they finally decide to file a claim.
In the insurance industry, a pre-existing condition is defined broadly as any illness, disease, or physical injury that exhibits symptoms before a pet insurance policy officially takes effect. As a standard practice across the market, pet insurers decline to cover these pre-existing ailments, meaning any future treatments related to them must be paid for completely out of pocket.
Dr. Rebecca Greenstein, chief veterinarian at Kleinburg Veterinary Hospital and a veterinary expert for rover.com, reports witnessing a tangible rise in claim denials tied directly to pre-existing conditions. The primary function of insurance, she emphasizes, is to secure broad-spectrum financial protection for a wide variety of unexpected medical scenarios. However, by the time insurers begin carving out major organ systems and any related complications from a policy, owners may find themselves paying a monthly premium for coverage that fails to deliver support when an actual veterinary emergency arises.
Industry professionals generally advise that if pet owners are seriously considering purchasing health coverage for an animal, the most prudent strategy is to secure a policy well before any health issues manifest or medical interventions become necessary.
Pre-Existing Conditions Matter in Pet Insurance
A pet’s medical history forms the foundation upon which insurers determine which treatments, medications, and procedures will be financially covered down the line. Understanding how these exclusions operate can prevent unexpected expenses after a policy has already been purchased.
Consider a common scenario involving a dog with a documented history of seasonal allergies. If an owner decides to purchase an insurance policy only after their four-footed companion has already exhibited clinical symptoms, pet insurers typically refuse to cover ongoing allergy shots, specialized diets, or related pharmaceutical treatments. According to Dr. Michael Goldstein, medical director at Billerica Veterinary Hospital and Thrive Pet Healthcare, these policy exclusions can stretch even further to encompass seemingly unrelated secondary problems, such as persistent skin itchiness or recurrent ear infections.
Dr. Goldstein illustrates the risk with a frequent clinical example: a dog that is brought into a veterinary clinic to be treated for a hot spot one year, followed by an ear infection the next. If the owner acquires pet insurance in the interim period between those two veterinary visits, the insurer may ultimately deny coverage for both conditions. This denial happens because underwriters can view both separate issues as systemic manifestations of an underlying, un-insurable allergy.
The most effective way for pet owners to circumvent these frustrating coverage gaps is to buy comprehensive insurance coverage while their pets are still young, long before any subtle symptoms or minor veterinary diagnoses have a chance to develop.
Why Skipping Pet Insurance Might Be Risky
Weighing the financial pros and cons of pet insurance can be an intricate exercise in risk assessment. Standard comprehensive plans, which typically cover a mix of unexpected accidents and sudden illnesses, require significant financial commitments. According to data compiled by the North American Pet Health Insurance Association (NAPHIA), the average annual cost for a dog accident-and-illness policy sits at $836, while equivalent coverage for a cat averages $435 per year. An owner might faithfully pay these annual premiums for years before an emergency surgery or a costly chronic illness forces them to test the policy’s true value.
While it is impossible to predict whether an individual animal will maintain robust health throughout its life or accumulate staggering veterinary bills, owners can better evaluate the potential worth of insurance by examining the common chronic conditions that frequently develop as pets age.
Cats, for example, tend to experience relatively few major health complications during their youth. However, as they transition into their senior years, specific ailments become far more prevalent. Older cats face a particularly high risk of developing chronic kidney disease, a progressive condition that requires careful long-term management. Data from the Cornell Feline Health Center indicates that as many as 40% of cats over the age of 10 suffer from chronic kidney disease, with annual veterinary treatment costs frequently topping $1,200.
Dogs face their own set of age-related vulnerabilities. Atopic dermatitis resulting from skin allergies is a widespread ailment that affects up to 15% of the canine population, according to figures from the Cornell Richard P. Riney Canine Health Center. A single veterinary appointment aimed at diagnosing and managing these persistent, itchy symptoms can easily cost $250 or more. While that initial diagnostic expense may represent only a fraction of the cost of an annual insurance premium, the cumulative financial burden of managing chronic conditions over a pet’s entire lifetime can scale rapidly.
Furthermore, veterinary bills have the capacity to balloon exponentially if a chronic health problem requires surgical intervention. A prominent example is hip dysplasia, an inherited genetic disorder that frequently leads to severe osteoarthritis and chronic pain, particularly in large-breed dogs. Depending on the complexity of the required surgical procedure, owners can face bills reaching up to $10,000.
Many traditional pet insurance plans do provide coverage for surgical and medical treatments related to hip dysplasia, provided the condition is not classified as pre-existing. Nevertheless, some policies enforce strict waiting periods ranging from six to 12 months specifically for orthopedic issues. If a dog begins showing symptoms of hip dysplasia during that initial waiting period, the condition is officially categorized as pre-existing and is permanently excluded from coverage. This structural reality serves as yet another compelling argument for purchasing insurance coverage early in a pet’s life rather than waiting until a health concern arises.
Ultimately, proponents argue that holding an active insurance policy grants owners the peace of mind needed to make medical decisions based strictly on what is best for the animal rather than what fits within an immediate budget. Dr. Greenstein notes that it is deeply tragic when life-and-death medical decisions are dictated entirely by personal financial constraints, observing that what is medically best for an animal and what is economically affordable for an owner frequently occupy opposite ends of the spectrum.
If Pet Insurance Is Too Pricey, Consider Alternatives
For owners who find comprehensive pet insurance financially prohibitive, alternative strategies exist to help manage veterinary risk. One popular option is purchasing an accident-only plan. These policies are generally much less expensive than full coverage, carrying an average annual cost of about $190 for dogs and $112 for cats, according to NAPHIA data. Accident-only plans are designed to handle physical injuries resulting from sudden mishaps, which include not only lacerations and broken bones but also the ingestion of dangerous foreign objects or toxins.
However, an accident-only policy leaves owners exposed to some of the most frequent drivers of veterinary expenditures. Illnesses, rather than sudden physical injuries, account for the vast majority of insurance claims submitted to providers. Data shared by the pet insurer Lemonade reveals that over 60% of all claims filed with the company over the course of a recent year stemmed from illnesses, a figure that is twice as large as the next most common category, preventive care. A similar underlying trend appears in data published by Nationwide, which shows chronic diseases representing a clear majority of the pet insurance claims submitted to the carrier.
For pet parents who choose to rely on an accident-only plan or decide to forgo third-party insurance entirely, veterinary experts emphasize the importance of maintaining a dedicated personal savings fund. Setting aside money specifically for inevitable veterinary emergencies and unexpected illnesses can prevent owners from facing agonizing choices regarding their pet’s medical care based solely on the upfront cost of treatment.
No comments yet. Be the first to join the conversation!