
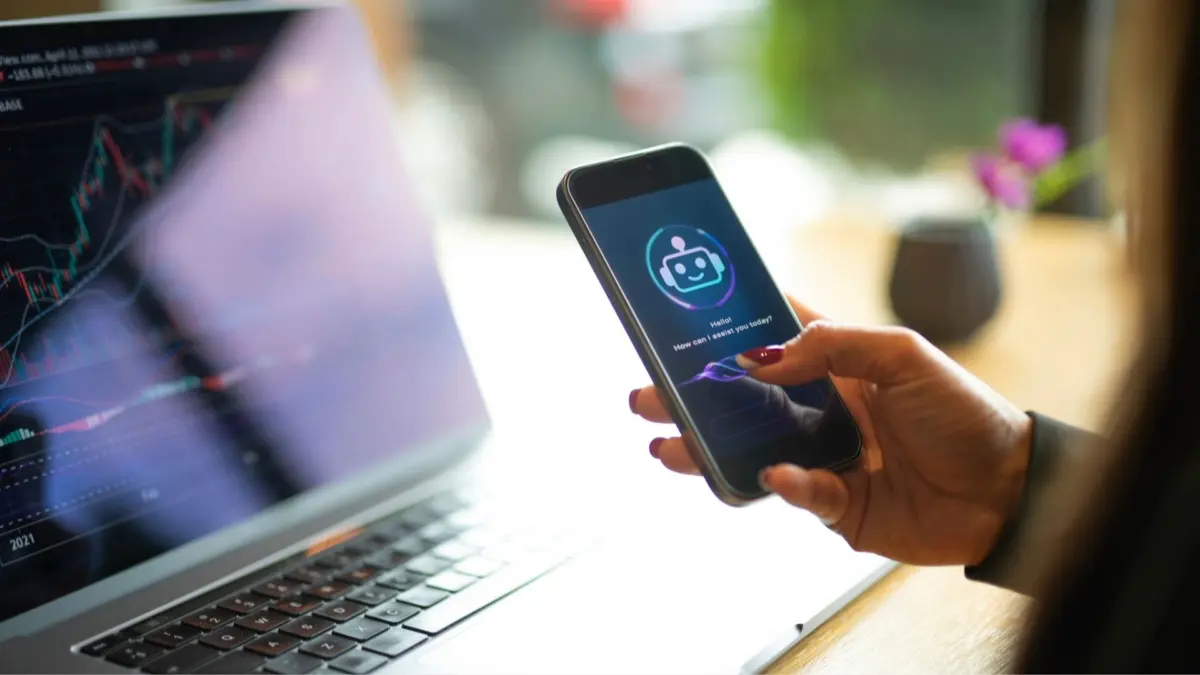
An increasing number of retirees are bypassing traditional human financial advisers in favor of artificial intelligence, turning to conversational chatbots to answer complex questions regarding their personal finances. The appeal of these digital tools is straightforward: answers are generated in a matter of seconds, sensitive questions can be asked without embarrassment, and the service is entirely free. However, financial experts warn that this convenience hides a significant risk. Because generative AI models are designed to produce fluent and persuasive language, an incorrect or incomplete answer looks identical to a correct one, leaving unsuspecting users vulnerable to costly financial mistakes.
The fundamental issue stems from how modern AI models operate. A chatbot does not actively look up current data or review live government databases. Instead, these systems are trained on massive archives of text gathered up to a specific cutoff date and generate responses by predicting which words are statistically most likely to come next. When a chatbot states a specific monetary figure, age threshold, or percentage, it is simply reproducing what appeared most frequently in its training data. It is not reading a live government policy page or tracking legislative changes in real time.
This mechanism makes retirement planning one of the worst possible use cases for unverified AI assistance, because crucial financial rules and limits change on an annual basis. Contribution limits serve as the clearest example of this vulnerability. For the 2026 tax year, the maximum amount an individual can contribute to a 401(k) plan rose to $24,500, while the IRA contribution limit increased to $7,500. Just one year prior, those limits were set at $23,500 and $7,000, respectively. An AI model trained before those official announcements will confidently provide last year’s figures, and its phrasing will offer no indication that the numbers are outdated or stale.
Other critical retirement figures are routinely altered by federal legislation years after previous rules have circulated widely across the internet. For instance, the mandated age at which retirees must begin taking required minimum distributions, commonly known as RMDs, has shifted multiple times. It was historically set at age 70½, later raised to 72, then adjusted to 73, and is scheduled to reach age 75 by 2033. Because all four of these different ages remain active across countless online articles, typically without publication dates attached, a chatbot can easily pull and present an obsolete age as current policy.
Ultimately, artificial intelligence handles broad concepts reliably while handling specific numeric details unreliably. Industry analysts emphasize that navigating this split requires extreme caution, as any answer containing a dollar amount, an age restriction, a tax percentage, or an income threshold needs independent verification before a retiree takes any financial action. Experts advise questioning the exact tax year to which a figure applies, noting that chatbots will frequently admit their information may be outdated when directly challenged, even after volunteering the incorrect number without hesitation.
Understanding which federal agency oversees a specific rule provides another layer of protection. While a chatbot may struggle with precise annual numbers, it can accurately identify the governing body behind a financial regulation. Information regarding contribution limits, RMDs, and general tax treatment must always come directly from the Internal Revenue Service. Benefit calculations and official claiming ages are governed by the Social Security Administration, while Medicare premiums and income-related monthly adjustment amounts fall under the purview of Medicare and the Social Security Administration. Pension regulations are handled separately by the Department of Labor. Recognizing the correct oversight agency transforms vague online searches into targeted reviews of authoritative primary sources.
Failing to verify these details at the source can lead to severe financial penalties. Missing a required minimum distribution, for example, triggers a steep penalty equal to 25% of the amount that should have been withdrawn, though that fine is reduced to 10% if corrected promptly. On a distribution of $40,000, a missed deadline resulting from incorrect AI guidance could cost a retiree $10,000 in penalties alone.
Furthermore, chatbots generally answer in broad generalities unless explicitly provided with personal circumstances. To get a more relevant evaluation, users must supply key details that influence financial outcomes, such as age, account types, pension income, state of residence, and marital status. However, experts strongly caution against sharing personally identifiable information. Comparing a generalized response with a personalized response reveals whether the underlying advice accounts for individual thresholds. For example, Medicare’s income-related monthly adjustment amount functions as a strict financial cliff rather than a gradual increase, hitting single filers and couples hard once specific income lines are crossed. A chatbot that suggests executing a Roth conversion without factoring in these Medicare surcharges can inadvertently saddle a retiree with thousands of dollars in unexpected annual healthcare premiums two years down the line.
Financial professionals also recommend testing a chatbot’s reliability by rephrasing questions across different days or slightly altering variables to see if the resulting output shifts logically. However, consistency should never be mistaken for accuracy. Rawad Baroud, chief financial officer of ZeroGPT, notes that generative AI can produce responses that are clear, detailed, and convincing without ever verifying the underlying facts. Asking a question multiple times can expose inconsistencies, but receiving the same answer twice does not prove it is correct. For financial matters, the final verification must always rest against an authoritative source rather than repeated chatbot prompts.
Another major pitfall is that conversational models typically answer only the specific question asked while ignoring critical contextual factors or potential downsides. A recommendation to execute a Roth conversion, for instance, should immediately surface the immediate tax liability incurred in the current year, the subsequent impact on Medicare premiums, and the IRS five-year holding rule before the guidance can be considered complete. Gregor Emmian, deputy chief growth and finance officer at Rise, points out that the most dangerous AI answers are those delivered without caveats. Advising someone to convert funds or claim benefits early without mentioning potential negative consequences represents only half an answer, as every major retirement decision involves permanent tradeoffs.
For irreversible financial decisions, the stakes are simply too high to rely on unverified digital tools. Actions such as claiming Social Security benefits, converting a large lump sum to a Roth account, purchasing an annuity, or taking a pension payout as a lump sum cannot be undone once executed. Making a permanent miscalculation can severely reduce lifetime income. For instance, claiming Social Security at age 62 when a worker’s full retirement age is 67 permanently reduces monthly benefits by approximately 30% for life, a reduction that also extends to survivor benefits. On a standard monthly benefit of $2,400, that penalty amounts to roughly $720 every month, or more than $8,600 annually, for the remainder of a couple’s lives.
When facing decisions of this magnitude, experts advise printing out the chatbot’s findings and bringing them directly to a qualified financial adviser or certified public accountant to identify errors and discuss underlying risks. This approach ensures that personal finances are reviewed by a human professional who is legally accountable for the guidance provided, a level of responsibility that no conversational algorithm can shoulder.








No comments yet. Be the first to join the conversation!