
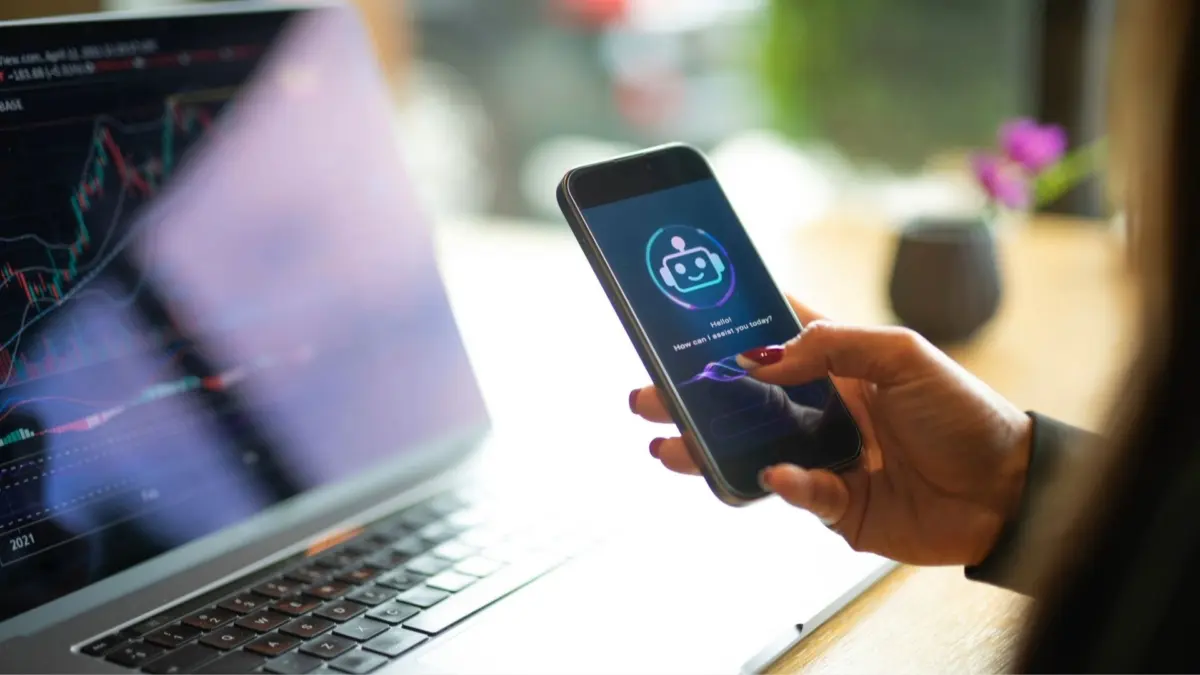
A growing number of retirees are bypassing traditional human financial advisers in favor of artificial intelligence chatbots to answer complex questions regarding their personal finances, retirement planning, and tax strategies. The immediate appeal of this digital shift is understandable. AI chatbot responses are generated in a matter of seconds, require no appointment scheduling, eliminate the social awkwardness or embarrassment of asking basic financial questions, and are entirely free to use.
However, financial experts warn that this convenience comes with a significant hidden danger. A completely incorrect or incomplete answer provided by an AI model looks identical to a correct one on a computer or smartphone screen. Because generative artificial intelligence is designed to sound authoritative and confident regardless of the factual accuracy of its output, unsuspecting retirees can easily fall victim to outdated regulations, flawed arithmetic, or missing legal caveats that carry severe financial consequences.
Understanding why artificial intelligence frequently miscalculates retirement figures is critical for anyone attempting to navigate modern personal finance through digital tools. Unlike a human researcher or a certified financial planner, a chatbot does not actually look up information in real time or browse government databases. Instead, these systems are trained on vast bodies of text gathered up to a specific training cutoff date. When a user prompts a chatbot for a financial figure, the model generates an answer by predicting which words are statistically most likely to come next based on patterns in its training data. When it states a specific monetary limit, age requirement, or tax threshold, it is merely reproducing the figure that appeared most frequently in historical texts rather than consulting a current government web page.
This operational mechanism makes retirement rules exceptionally poorly suited for AI assistance, primarily because the most critical numbers governing retirement plans change on an annual basis. Contribution limits serve as the clearest illustration of this vulnerability. For the year 2026, the maximum amount an individual can contribute to a 401(k) plan rose to $24,500, while the standard IRA contribution limit increased to $7,500. Just one year prior, those respective limits were $23,500 and $7,000. An AI model trained prior to the official announcement of these adjustments will provide the previous year’s figures with absolute, unhesitating confidence. Furthermore, the phrasing of the response typically contains no indication that the provided numbers are stale or obsolete.
Other vital figures can be altered unexpectedly by federal legislation years after earlier figures have already circulated widely across the internet. For instance, the statutory age at which retirees are legally required to begin taking mandatory withdrawals from their tax-deferred accounts—known as required minimum distributions, or RMDs—has shifted multiple times over recent years. The mandatory starting age was historically 70½, before being raised to 72, then 73 under subsequent legislation, and scheduled to reach 75 by the year 2033. Because all four of these different ages currently populate various financial blogs, articles, and discussion boards across the internet—frequently without any accompanying publication date—chatbots easily conflate historical rules with current mandates.
In practice, artificial intelligence models handle overarching financial concepts quite reliably while handling specific numeric details and temporal constraints unreliably. Navigating this reality requires retirees to establish rigorous verification habits before acting on any digital recommendation. The first safeguard involves rigorously checking the temporal context of every single number produced by a chatbot. Any response containing a specific dollar amount, age threshold, tax percentage, or income limit demands a verified date before it holds any practical value. Users should proactively ask the chatbot directly to specify the exact tax year to which a given figure applies. Interestingly, when explicitly challenged about temporal validity, chatbots will frequently acknowledge that their underlying information may be outdated, despite having volunteered the exact same figure moments earlier without hesitation. Any financial figure presented without a clear, verified year attached must be treated as highly suspect.
The second line of defense involves identifying the precise regulatory agency responsible for setting the specific rule in question. While numerical data points can easily become corrupted within an AI model’s training parameters, conceptual questions regarding institutional jurisdiction are answered much more reliably. Information concerning retirement account contribution limits, tax treatment, and RMD schedules originates strictly from the Internal Revenue Service. Benefit calculations, claiming age rules, and earnings limitations are managed exclusively by the Social Security Administration. Details regarding Medicare premiums and income-related monthly adjustment amounts, commonly known as IRMAA, are overseen by Medicare.gov and the Social Security Administration, whereas pension regulations fall under the jurisdiction of the Department of Labor. Pinpointing the exact governing agency transforms a vague, generalized verification task into a straightforward visit to a single authoritative government webpage.
Once an official source is identified, verifying the information directly at the primary source is paramount, rather than relying on secondary summaries or AI-generated synopses. Federal agency web pages explicitly state the precise tax year and operational guidelines to which every figure applies. Skipping this verification step can prove remarkably expensive for retirees. For example, failing to execute an RMD on time triggers a steep federal penalty equal to 25% of the amount that should have been withdrawn, though this penalty is reduced to 10% if the error is corrected promptly. On a required distribution of $40,000, a missed deadline resulting from inaccurate guidance provided by a chatbot can cost a retiree thousands of dollars in avoidable penalties.
Providing individualized personal circumstances to an AI model represents another essential step in evaluating the validity of its guidance. Chatbots naturally default to broad generalities unless the user supplies specific personal details. Essential data points that heavily influence financial outcomes include the user’s current age, the specific types of retirement accounts they hold, any existing pension income, their state of residence, and their marital status—including whether a spouse maintains an independent earnings record. However, financial experts strictly caution against inputting personally identifiable information into public AI platforms. Once specific circumstances are provided, retirees should compare the tailored response against the generalized answer received initially. If the generated advice barely changes despite the introduction of critical personal variables, the underlying guidance cannot be trusted.
This discrepancy matters significantly when dealing with strict government income thresholds. Medicare’s IRMAA operates as a sharp cliff rather than a gradual sliding scale, imposing significantly higher monthly premiums once modified adjusted gross income exceeds specific thresholds, such as $109,000 for single filers and $218,000 for married couples filing jointly. A chatbot that casually suggests executing a Roth conversion without factoring in IRMAA brackets can inadvertently cause a retiree to incur thousands of dollars in unexpected annual healthcare surcharges two years later, given that IRMAA calculations are based on tax returns from two years prior.
As part of the evaluation process, financial experts recommend asking the same question multiple times using different phrasing, ideally across separate days, to test whether the original response remains consistent. Introducing slight variations, such as adjusting an age parameter or removing a pension income stream, should logically alter the output in a predictable direction. Responses that swing wildly upon rephrasing indicate that the content is being dynamically generated rather than accurately recalled from a verified knowledge base.
Rawad Baroud, chief financial officer of ZeroGPT, emphasizes that consistency should never be conflated with accuracy when evaluating AI-generated financial content. Generative artificial intelligence is fully capable of producing an answer that is clear, highly detailed, and thoroughly convincing without having verified any of the underlying facts. While rephrasing questions can expose internal contradictions, receiving the same answer twice does not constitute proof of correctness. For sensitive financial matters, the ultimate verification must always be performed against an authoritative, official source.
Furthermore, retirees should proactively prompt AI models to disclose what information or caveats have been omitted from their initial responses. Chatbots are structurally designed to answer the exact prompt provided and rarely volunteer information regarding external factors or downstream consequences. A standard recommendation to execute a Roth conversion, for instance, should automatically surface the immediate tax liability incurred in the current tax year, the subsequent impact on Medicare premium surcharges, and the strict five-year holding rule before the advice can be considered comprehensive.
Gregor Emmian, deputy chief growth and finance officer at Rise, notes that the most hazardous AI answers are invariably those devoid of necessary caveats. If a chatbot recommends executing a Roth conversion or claiming Social Security benefits early without addressing potential pitfalls, the response is incomplete. Retirees should treat inquiries regarding what information has been omitted as a mandatory follow-up step rather than an optional feature. Every major retirement decision involves complex trade-offs, and an answer that highlights no potential downsides is fundamentally incomplete.
Finally, experts stress that certain irreversible financial decisions demand direct consultation with human professionals, such as certified financial planners or certified public accountants. Actions that cannot be undone once executed—including claiming Social Security benefits, converting large sums into a Roth IRA, purchasing complex financial annuities, or accepting a company pension as a lump sum—belong firmly in this category. The financial cost of a miscalculation in these areas is permanent. Claiming Social Security benefits at age 62 when an individual’s full retirement age is 67 permanently reduces their monthly benefit by roughly 30% for the rest of their life, a reduction that also extends directly to survivor benefits. On a standard monthly benefit of $2,400, that permanent reduction amounts to approximately $720 every month, exceeding $8,600 annually for the remainder of either spouse’s life.
For decisions carrying irreversible consequences, retirees are advised to print the chatbot’s generated response and bring it directly to a qualified human adviser or accountant to evaluate which components are flawed and why. That collaborative conversation will be far more targeted and efficient than starting from scratch, while placing the responsibility for the final execution onto a licensed professional who can be held legally accountable—a safeguard no artificial intelligence model can provide.








No comments yet. Be the first to join the conversation!