
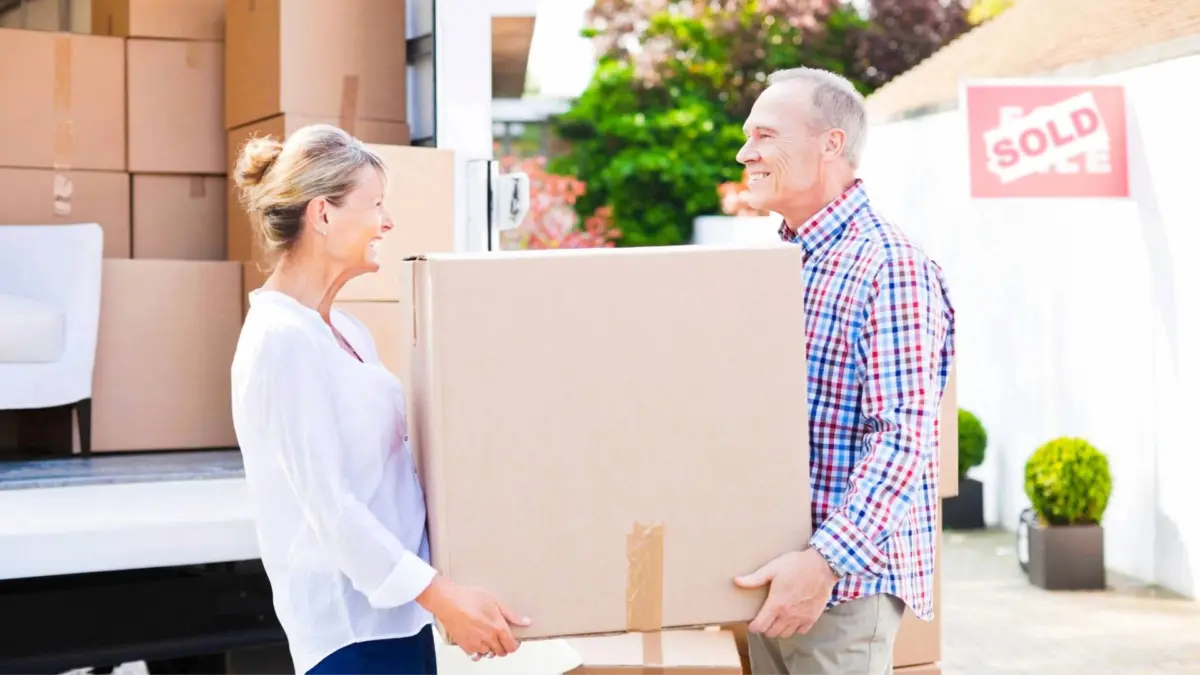
For many Americans approaching their golden years, the decision of where to spend retirement is frequently framed by a singular pursuit: escaping state income taxes. The conventional narrative often sends retirees stampeding from high-tax states like New York or California toward sun-drenched, tax-friendly havens like Florida or Texas. But according to financial planners and tax experts, this narrow focus can often obscure a much more complex financial reality.
Sitting in a home office straddling the border regions of Virginia and Maryland offers a unique vantage point on this phenomenon. A common misconception persists that crossing the bridge from Virginia into Washington, D.C., automatically triggers a massive tax penalty across the board. In truth, the financial picture is far more intricate. While income taxes—the metric most commonly used by the public to gauge whether a tax climate is "high" or "low"—do indeed increase for those who move into the District, property taxes simultaneously decrease. Consequently, retirees with modest real estate footprints or specific financial layouts may find themselves in a surprisingly advantageous position within the city limits.
However, layer in additional variables—such as the District’s estate tax or Maryland’s combination of estate and inheritance levies—and a retiree with a substantial balance sheet might ultimately be better off remaining across the river in Virginia. The broader takeaway is that state and local tax codes are multi-dimensional, and relocating solely for a single perceived benefit can introduce unforeseen financial trade-offs.
Financial professionals emphasize that making a major relocation decision in retirement strictly for tax purposes is frequently a misstep if approached without a comprehensive evaluation of the complete tax landscape. To unpack why the broader picture demands careful scrutiny, experts point to five distinct categories of taxation that deserve thorough examination before anyone boxes up their belongings for an interstate move.
Five Taxes to Consider
1. Income Tax
The pursuit of zero-income-tax states is a well-trodden path. People frequently migrate to destinations like Texas not necessarily for the regional cuisine, but to ditch state income tax burdens entirely. While income tax is almost universally the most consequential financial factor during a person’s working years, that dynamic frequently shifts once an individual transitions into retirement.
Currently, a select group of states do not levy a tax on earned income. Yet, much like the federal government, the majority of states utilize a progressive income tax structure where the statutory rate scales upward alongside earnings. Retirees must look beyond top-line rates to understand the progression and determine the effective or average rate they are realistically expected to pay. When financial planners integrate a retirement relocation into a comprehensive financial plan, the projections typically reveal clear trajectories for income, capital gains, and estate tax liabilities. Using specialized financial planning software, advisors can often quantify precise savings, illustrating how much capital a relocating retiree might retain and reallocate elsewhere.
2. Capital Gains Tax
At the federal level, capital gains rates are intentionally designed to be more favorable than ordinary income tax rates to incentivize investment. Unfortunately, the same generous treatment does not always translate to state-level tax codes.
In the vast majority of states that levy an individual income tax, capital gains are treated as ordinary income and taxed at the exact same rates. For instance, when homeowners sell a long-held property, the resulting capital gain is frequently subjected to the state’s standard income tax brackets.
There are, however, notable exceptions that can catch unwary taxpayers off guard. Washington state, for example, does not levy a traditional individual income tax, but it does enforce a distinct tax on capital gains. For retirees whose wealth is largely insulated within tax-deferred retirement accounts like traditional IRAs or 401(k)s, this distinction may matter very little. But for individuals who have recently liquidated a business or hold the vast majority of their assets in taxable, non-retirement brokerage accounts, Washington state might prove to be a remarkably unfavorable tax destination.
3. Sales Tax
The state of Delaware is frequently celebrated in popular culture as a "tax-free state," earning praise from proud university alumni and cost-conscious consumers alike. In reality, the label is a misnomer. While Delaware does not impose a statewide sales tax, it certainly collects revenue through other means, including income taxes and property taxes—though coastal property tax rates remain notably low compared to neighboring regions.
Sales taxes are generally viewed as straightforward transactional levies, yet they often feature complex adjustments depending on the specific category of consumer goods purchased. For instance, individuals who frequently dine out may find that Washington, D.C., presents a heavier financial pinch due to specialized local dining and hospitality taxes. Conversely, retirees who enjoy fine wines or spirits might want to factor specific state-level alcohol pricing and tax structures into their lifestyle equations, as seen in states like Washington, where adult beverage taxes run high.
4. Property Taxes
A frequent rude awakening awaits retirees who migrate to popular sunbelt destinations like Texas or Florida in search of income tax relief, only to be met with exorbitant property tax bills. As the old adage reminds consumers, there is no such thing as a free lunch. State and local governments require steady streams of revenue to fund public infrastructure and services, meaning money saved in one area is often recouped in another.
The primary objective for retirees should be identifying a jurisdiction where the tax burden falls elsewhere. For those considering the purchase of a secondary residence or retirement home, renting rather than buying can sometimes serve as a viable alternative, provided the arrangement satisfies state residency requirements. Furthermore, homeowners must evaluate a property’s assessed value relative to its actual market value. A seemingly high tax rate applied to an assessed value that sits significantly below market value may ultimately sting far less than a moderate rate levied against a fully modernized market valuation.
5. Estate and Inheritance Taxes
Although the terms are frequently used interchangeably in casual conversation, estate taxes and inheritance taxes represent distinct mechanisms of wealth extraction. Estate taxes are levied directly upon the overall estate of the decedent before distribution, whereas inheritance taxes are paid directly by the individual beneficiaries receiving the assets.
An increasingly small number of states maintain either of these levies on their books. However, for high-net-worth individuals who have failed to implement proactive estate planning, these state-level "death taxes" can prove exceptionally punitive. Rather than packing up and moving across state lines solely to evade potential estate liabilities, financial advisors suggest exploring whether strategic estate planning tools can adequately mitigate the exposure.
Why the Full Picture is Even More Nuanced
The reality of the American tax code is that there is an exception to nearly every rule, and very few financial scenarios are entirely black and white. While a state’s headline income tax rate may appear intimidatingly high on paper, many jurisdictions offer substantial exemptions or exclusions for common retirement income streams, such as Social Security benefits, public and private pensions, and traditional retirement account distributions. In many cases, these exemptions are subject to income phaseouts or statutory caps that require careful navigation.
Similarly, property tax relief programs and homestead exemptions can significantly reduce the tax bite in multiple jurisdictions for qualifying seniors who meet specific age or income criteria.
Beyond direct taxation, the broader cost of living continues to play a decisive role in the financial sustainability of any retirement relocation. Many retirees who meticulously model state income, sales, and property tax scenarios on spreadsheets still find themselves grappling with unexpectedly high grocery bills, surging contractor and home maintenance costs, and inflated restaurant prices—particularly in regions that experienced massive population inflows during the economic shifts of the COVID-19 pandemic.
Ultimately, financial professionals advise that anyone contemplating an interstate move for tax optimization in retirement should proceed with a thorough, eyes-wide-open assessment of all interacting financial variables, ensuring that lifestyle satisfaction and comprehensive financial security remain balanced long after the moving trucks have departed.
No comments yet. Be the first to join the conversation!