
Mortgage rates continued their downward trajectory this week, extending a gradual slide that began well before voters headed to the polls for the midterm elections. Homebuyers facing a prolonged affordability crunch are watching closely as political shifts, geopolitical tensions, and broader economic forces intersect to influence borrowing costs.
According to rate data provided to NerdWallet by Zillow for the week ending November 5, the average rate on a benchmark 30-year fixed-rate mortgage fell 13 basis points to 7.05% APR. A basis point represents one one-hundredth of a percentage point, with the weekly average calculated using daily annual percentage rates recorded over the preceding five business days.
While the modest relief is a welcome development for prospective buyers, the broader housing market remains burdened by a complex web of financial pressures. Homebuyers’ purchasing power continues to feel the pinch from stubbornly high mortgage rates, elevated home prices, and an ongoing shortage of housing inventory across the country. On the recent campaign trail, political candidates from both major parties made sweeping promises to restore affordability to the American housing market. However, industry experts note that untangling the current market dynamics is far from simple.
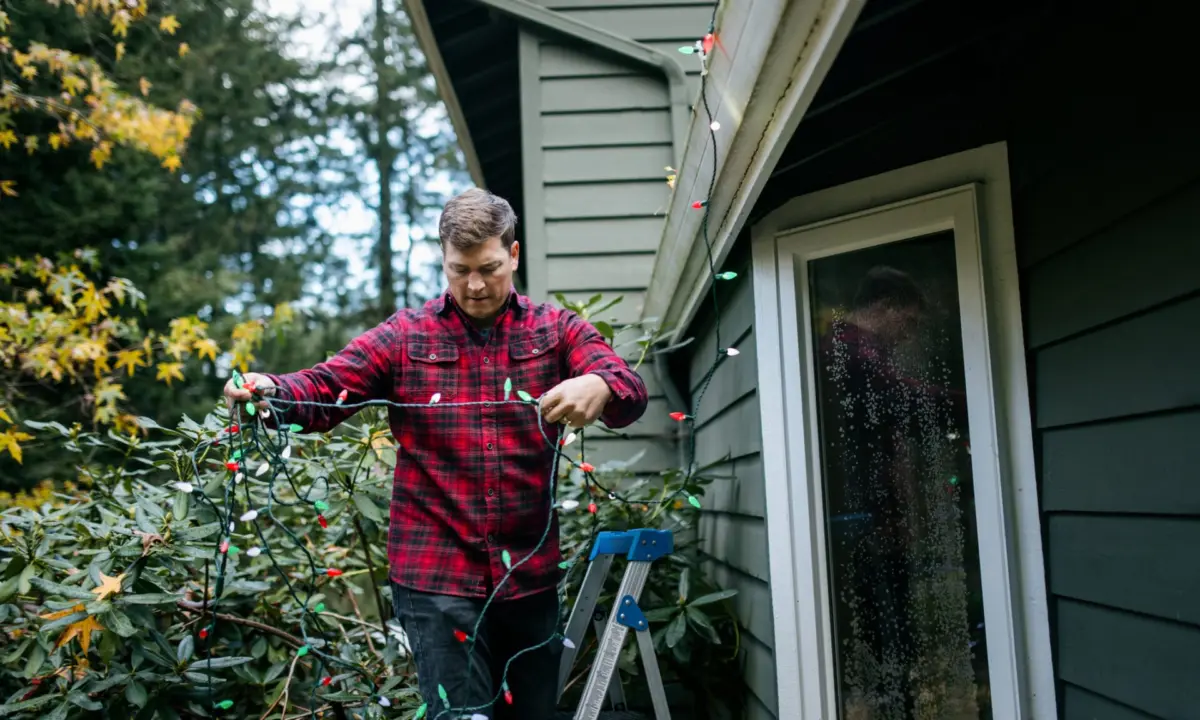
Jake Krimmel, senior economist for Realtor.com, compared solving the housing affordability crisis to untangling decades-old holiday lights from an attic. Pulling on a single strand often only tightens several others. Jumpstarting the housing market, Krimmel noted, relies heavily on achieving a calmer geopolitical environment and a stable bond market in the short run, alongside significantly boosting housing supply and fostering a more dynamic labor market over the long term.
A shift in the balance of political power in Washington will not magically erase these structural challenges overnight. Understanding the current trajectory of mortgage rates requires a closer look at the competing economic forces at play—ranging from government spending and corporate debt to global conflicts and central bank monetary policy.
Phew, the Midterms Are Over
The conclusion of the midterm elections has removed a significant layer of uncertainty from the financial markets, giving mortgage rates some much-needed breathing room. Election outcomes that left control of Congress divided between political parties have signaled to investors that major, sweeping spending legislation could face formidable roadblocks in the legislative branch.
While political gridlock is rarely popular among the electorate, financial markets frequently welcome a divided government. When structural gridlock limits the passage of expansive new federal spending bills, the federal government may need to borrow less money than previously anticipated. This potential reduction in federal borrowing pressure can help cool down the broader bond market, which in turn takes some of the upward pressure off mortgage rates.
At the same time, this very same political gridlock introduces a notable catch for consumers. A divided government could simultaneously make it significantly more difficult to pass bipartisan legislation aimed at directly tackling high housing costs and expanding residential inventory. Analysts point out that while market volatility tied to political uncertainty may subside, legislative solutions to the nation’s housing crisis will likely require persistent bipartisan cooperation.
Government Debt Meets Big Tech’s Borrowing Binges
The broader direction of mortgage rates remains tightly linked to the health and behavior of the bond market, particularly the yield on the 10-year Treasury note, which serves as a benchmark for home loans. Heavy borrowing from both the federal government and massive technology corporations continues to add upward pressure to these yields.
When the federal government runs a deficit and spends more than it collects in tax revenues, it finances the difference by issuing and selling Treasury bonds. When a high volume of government debt floods the market, investors often demand higher returns—known as yields—to absorb the supply. Because mortgage lenders price their loans in relation to Treasury yields, rising government borrowing costs frequently translate into higher monthly mortgage payments for everyday consumers.
The newly seated Congress will continue to grapple with a massive mountain of national debt. How lawmakers choose to approach fiscal policy and budgetary negotiations will send immediate ripples through the broader economy. Andy Winkler, managing director for housing and infrastructure policy at the Bipartisan Policy Center, emphasized that sound fiscal policy, rather than deficit-financed spending and high-stakes standoffs over budgets and debt limits, is essential for keeping borrowing costs in check.
Adding to the heavy supply of debt in the financial markets is a massive borrowing binge by major technology companies racing to construct artificial intelligence data centers. To secure the immense amounts of capital required for these massive infrastructure projects, tech giants have increasingly issued corporate bonds. This surge in corporate debt gives investors alternative places to park their money, creating additional competition in the bond market that can push Treasury yields higher and pull mortgage rates upward along with them.
Questions remain regarding how long the current artificial intelligence building boom can sustain its rapid pace. Voters across the political spectrum expressed frustration over the proliferation and environmental impact of data centers during the recent midterm elections. Yet, even if lawmakers or local communities successfully pump the brakes on new construction, economists warn that a slowdown in tech sector spending does not automatically guarantee cheaper mortgages for homebuyers.
Iran War and Inflation Complicate the Economic Picture
Geopolitical instability continues to cast a long shadow over the domestic economy. Ongoing disruptions to global oil supplies stemming from the war in Iran have fueled persistent inflationary pressures, driving up borrowing costs across the board.
The unpopular conflict in Iran contributed significantly to the voter anxiety and economic frustration that helped shape the outcomes of the midterm elections. Higher energy costs reverberate through household budgets in multiple ways—hitting consumers directly at the gasoline pump, driving up the cost of manufactured goods that rely on complex shipping networks, and eventually translating into higher interest rates as inflation heats up.
Krimmel noted that a diplomatic resolution to the conflict would likely improve global oil supplies, helping to ease underlying price pressures and potentially offering meaningful relief to mortgage rates. While a newly configured Congress might push for alternative approaches to ending the conflict, lawmakers ultimately lack direct control over foreign actors reaching a lasting diplomatic agreement.
Meanwhile, stubborn inflation driven in part by wartime energy shocks has raised the distinct prospect of another Federal Reserve interest rate hike at its upcoming policy meeting. Futures traders have increasingly priced in the likelihood of a quarter-point increase as economic data remains resilient. While the Federal Reserve does not set mortgage rates directly, bond market investors closely anticipate central bank decisions, causing mortgage rates to frequently adjust well in advance of any official Fed policy announcement.
Navigating the Housing Market Amid Economic Uncertainty
For prospective homebuyers wondering whether to press pause on their search or jump into the market, financial advisors suggest that timing the broader political and economic cycle is rarely a reliable strategy. If buying a home aligns with a household’s current financial budget and long-term goals, waiting solely because of changes in Washington or fluctuating interest rate headlines may not be necessary.
Real estate experts note that buyers can occasionally secure more favorable purchase prices during the winter months, when housing inventory slows down and sellers are frequently more motivated and willing to negotiate. However, with mortgage rates hovering above the 7% threshold, higher borrowing costs can quickly erode potential savings on the purchase price. Consequently, financial experts emphasize the importance of shopping around and comparing offers from multiple mortgage lenders to secure the most competitive rate available.
Looking toward longer-term structural solutions for housing affordability, analysts point to legislative efforts such as the bipartisan 21st Century ROAD to Housing Act, which was signed into law earlier this year. The legislation demonstrated that lawmakers from both parties can find common ground to address fundamental challenges within the housing sector.
Winkler suggested that even within an environment of divided government, lawmakers and the executive branch have an opportunity to build upon that existing common ground. Further efforts could focus on boosting overall housing production, preserving existing affordable housing stock, and assisting families struggling with the combined burdens of high housing and utility costs.
Ultimately, constructing new homes takes considerable time, and an individual’s personal house hunt does not need to follow the calendar of Congress. Sound financial planning, personal budget constraints, and localized market conditions remain far more critical factors than the next political headline when deciding when to buy a home.
No comments yet. Be the first to join the conversation!