
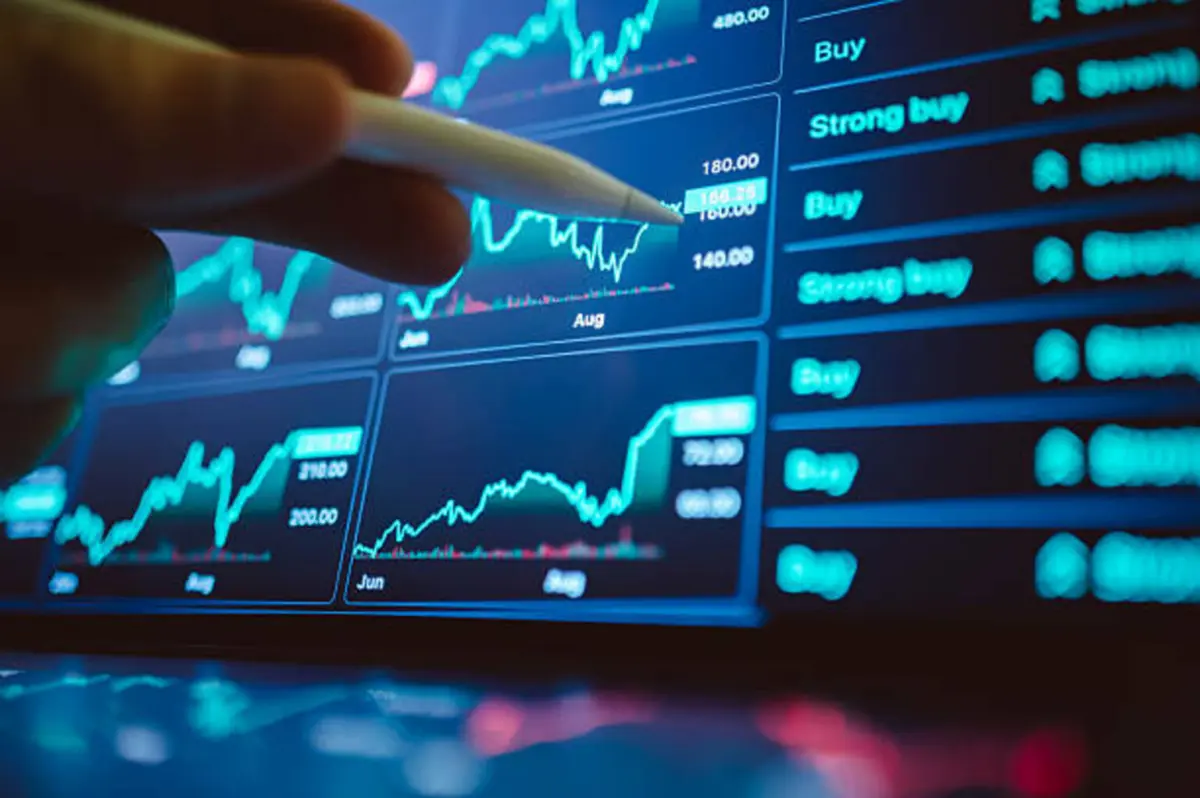
In the contemporary financial landscape, the integration of advanced digital platforms, big data analytics, and automated computing systems has fundamentally reshaped how institutional and retail investors approach asset allocation. As global markets grow increasingly complex and interconnected, traditional methods of financial analysis are continually being augmented—and in many cases replaced—by sophisticated computational tools capable of processing vast amounts of market information in real time. This technological evolution is particularly evident in the rapidly expanding sectors of exchange-traded funds (ETFs) and bond investments, where precision, speed, and data-driven insights have become paramount for navigating shifting economic conditions.
The modern investor operates in an environment where macroeconomic data, corporate earnings reports, geopolitical developments, and high-frequency trading metrics converge simultaneously. To make sense of this continuous stream of information, financial institutions and technology providers have developed specialized digital platforms that harness the power of big data. These systems utilize advanced algorithms and machine learning models to analyze historical trends, evaluate credit risks, and predict market movements with a degree of granularity that was previously unattainable through manual research alone.
Within the realm of exchange-traded funds, big data computing plays a crucial role in portfolio construction, liquidity management, and index tracking. ETFs have experienced exponential growth over the past decade, evolving from simple equity index trackers into sophisticated investment vehicles that cover virtually every asset class, sector, and geography. As the universe of ETFs expands, fund managers rely heavily on digital platforms to monitor underlying index constituents, optimize basket creation and redemption processes, and maintain tight tracking accuracy. Furthermore, quantitative analytics enable managers to assess intraday liquidity and trading volumes, ensuring that these funds can efficiently absorb large capital flows without causing severe market distortions.
Simultaneously, the fixed-income market has undergone a significant digital transformation. Historically characterized by over-the-counter trading, fragmented liquidity, and a reliance on manual broker-dealer networks, the bond market has gradually embraced electronic trading platforms and data-centric analytical tools. Bond investing involves evaluating a myriad of complex variables, including interest rate trajectories, inflation expectations, credit spreads, issuer fundamentals, and macroeconomic policy shifts. By leveraging big data computing platforms, fixed-income investors can aggregate pricing data from multiple disparate sources, allowing for more transparent execution and improved price discovery.

The convergence of big data analytics, ETF structures, and bond investments represents a pivotal shift in how fixed-income strategies are packaged and delivered to the market. Bond ETFs, in particular, have emerged as a focal point of this technological integration. Traditionally, buying and selling individual corporate or municipal bonds required significant capital and administrative effort, often posing liquidity challenges for smaller market participants. The advent of fixed-income ETFs addressed many of these friction points by securitizing diversified baskets of bonds into a single, exchange-traded instrument. However, managing a portfolio of thousands of underlying fixed-income securities presents unique logistical hurdles, especially during periods of market stress when underlying bond liquidity may dry up.
This is where advanced digital platform analysis becomes indispensable. Portfolio managers utilize sophisticated computational modeling to simulate how a bond ETF will perform under various liquidity scenarios and interest rate shocks. By analyzing historical trading patterns of the underlying bonds—even those that do not trade frequently—algorithms can estimate fair value, optimize portfolio rebalancing, and construct synthetic liquidity models. This analytical capability allows fund managers to maintain the intraday tradability of ETFs while holding portfolios composed of relatively illiquid underlying assets.
Moreover, the application of big data in bond and ETF investing extends beyond portfolio management and into risk assessment and regulatory compliance. Financial institutions are subject to rigorous reporting standards and risk management frameworks that require continuous monitoring of market, credit, and operational risks. Automated platforms enable risk managers to run stress tests across entire portfolios within seconds, identifying potential vulnerabilities long before they materialize into actual losses. This proactive approach to risk management has become a cornerstone of modern financial stability, helping both institutional players and individual investors navigate periods of heightened volatility.
As the financial industry continues to digitize, the synergy between computational power and investment strategy is expected to deepen further. Emerging technologies, such as advanced predictive analytics and alternative data integration, are continuously expanding the boundaries of what digital platforms can achieve. Whether evaluating the creditworthiness of a corporate bond issuer through unconventional data sets or optimizing the structural efficiency of a multi-asset ETF, the reliance on big data computing has transitioned from a competitive advantage to an operational necessity. Ultimately, these technological advancements empower market participants with the analytical depth required to make informed decisions in an increasingly dynamic global economy.
No comments yet. Be the first to join the conversation!