
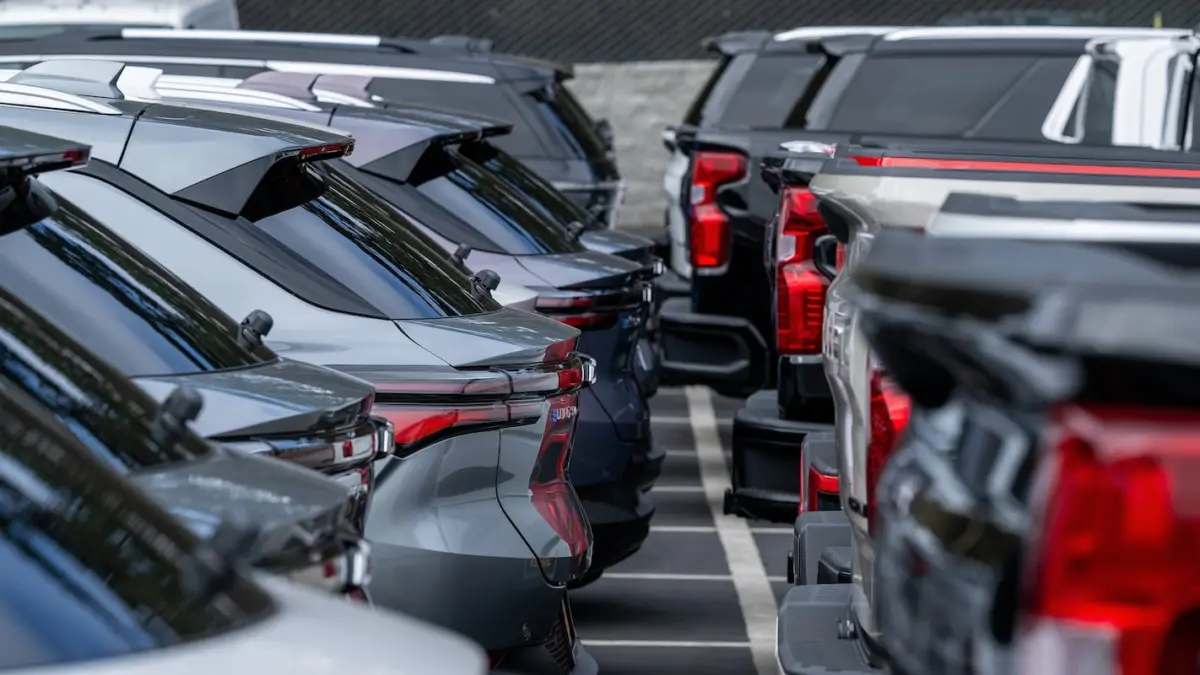
Slowdown or seasonality? New-vehicle inventories reach 3 million as full-size and big-ticket truck supplies climb
New-vehicle inventories reached 3 million in October as full-size pickups and luxury SUVs saw days’ supply climb faster than smaller, more fuel-efficient vehicles.
By Larry P. Vellequette
The total supply of new vehicles sitting on dealership lots across the United States officially surpassed the significant threshold of 3 million units in October, prompting a deeper industry-wide debate over whether the growing surplus represents a broader consumer demand slowdown or merely a predictable return to traditional seasonal automotive retail patterns.
This latest inventory milestone, tracked across the retail automotive sector, highlights a distinct divergence in how different segments of the market are moving. While smaller, more fuel-efficient cars and compact crossovers continue to experience relatively brisk movement and tighter supplies, big-ticket vehicles are telling a drastically different story. Specifically, full-size pickup trucks and large luxury sport utility vehicles are seeing their days’ supply climb at a notably faster rate, creating mounting pressure on dealerships and manufacturers alike to assess their production levels and pricing strategies as the final quarter of the year unfolds.
The accumulation of 3 million new vehicles on the ground represents a stark contrast to the severe inventory shortages that characterized the automotive retail landscape during and immediately following the global supply chain disruptions of recent years. Back then, lean inventories meant that vehicles frequently sold before they even arrived at a dealership, allowing automakers and retailers to maintain high transaction prices and minimal incentives. Today, however, the pendulum has swung significantly in the other direction, returning a level of choice and negotiation power to car buyers that has not been witnessed in years.
Yet, automotive analysts and retail experts are currently divided on how to interpret this rapid inventory accumulation. On one hand, some market watchers view the 3 million vehicle mark as a warning sign of consumer fatigue. Persistent high interest rates, elevated vehicle sticker prices, and broader economic uncertainties have begun to weigh heavily on household budgets. For months, affordability has remained a central challenge for consumers looking to purchase a new car, truck, or SUV. When borrowing costs remain elevated, big-ticket purchases are frequently the first items that consumers choose to delay or forgo entirely.
On the other hand, seasoned industry veterans point out that an inventory level of around 3 million units was historically considered a healthy, normal baseline for the U.S. retail automotive market prior to the pandemic. During those predictable pre-pandemic years, automakers relied on robust inventories to ensure that customers could walk onto a lot and drive away in the exact color, trim level, and configuration they desired without having to place a custom factory order or wait weeks for delivery. From this perspective, the current inventory growth could simply be interpreted as typical seasonality—a traditional fourth-quarter ramp-up as manufacturers push year-end production and dealerships prepare for the holiday selling season and the impending arrival of the next model year vehicles.
The nuanced nature of this inventory buildup becomes much clearer when examining the data beneath the headline numbers. Not all vehicles are accumulating at the same rate, and the segmentation of the market reveals where the real pressure points lie. The most pronounced increases in days’ supply are heavily concentrated in high-margin, high-priced segments, most notably full-size pickup trucks and large luxury SUVs. These big-ticket items represent substantial financial commitments for consumers, often carrying monthly payments that rival or exceed residential mortgage payments, especially when paired with current auto loan interest rates.
Full-size pickup trucks have long been the profit engine for domestic automakers, serving as cultural and economic mainstays of the American retail automotive market. However, the days’ supply for these lucrative workhorses and lifestyle haulers has expanded noticeably. As assembly plants maintain steady output, the retail pace for these heavy-duty and light-duty trucks has not kept exact pace with production, leading to a visible backing up of inventory at regional distribution hubs and local dealership franchises. Similarly, large luxury SUVs—vehicles that thrived during periods of strong wealth effect and high consumer confidence—are lingering on lots longer before finding buyers.
Conversely, the story on the other end of the lot remains relatively tight. Smaller passenger cars, hybrid options, and entry-level compact crossovers continue to move at a much more robust pace. Consumers grappling with stretched personal finances and the ongoing cost of living frequently gravitate toward vehicles that offer lower purchase prices, better fuel economy, and reduced insurance and maintenance costs. Because production allocations for these smaller, more efficient vehicles have not flooded the market to the same degree as their larger counterparts, their days’ supply metrics have remained comparatively stable and significantly lower than those of full-size trucks and luxury utilities.
This divergence places retail dealerships in a delicate balancing act. Managing lot space, floor plan interest—the financing costs that dealers pay to hold inventory on their lots—and pricing strategies requires a high degree of agility. When days’ supply climbs rapidly for big-ticket trucks and luxury SUVs, dealerships are forced to reevaluate their holding costs. Prolonged stays on the lot mean that floor plan expenses begin to eat into profit margins, ultimately compelling retailers to rely more heavily on manufacturer-backed incentives, lease subvention programs, or localized price discounts to encourage hesitant buyers to sign on the dotted line.
Automakers, too, are monitoring these inventory metrics closely. Manufacturing facilities operate on long-term schedules, meaning that adjusting assembly line speeds or temporarily pausing production to match shifting retail demand cannot happen overnight. If the October inventory milestone of 3 million units is indeed a signal of a broader demand slowdown rather than just a seasonal blip, automotive manufacturers may soon face difficult decisions regarding production cuts, plant retooling, or extended holiday shutdowns to prevent lot bloat from spiraling out of control as the new year approaches.
For the average consumer currently shopping the market, the growing availability of new vehicles, particularly in the truck and large SUV segments, could yield distinct advantages. After years of paying near-MSRP prices and facing limited choices, prospective buyers are likely to find a much more accommodating retail environment characterized by greater negotiating leverage, a wider array of available trims on the lot, and potentially more aggressive promotional financing offers as brands vie for market share heading into the final stretch of the year.
As the retail automotive sector continues to process the October data, the overarching question remains whether this 3 million unit threshold is a temporary seasonal peak or the early indicator of a more permanent cooling off in consumer demand for expensive vehicles. How manufacturers and dealerships respond to these shifting inventory dynamics in the coming weeks will largely determine the financial health of the retail automotive landscape as it transitions into the new year.



No comments yet. Be the first to join the conversation!