
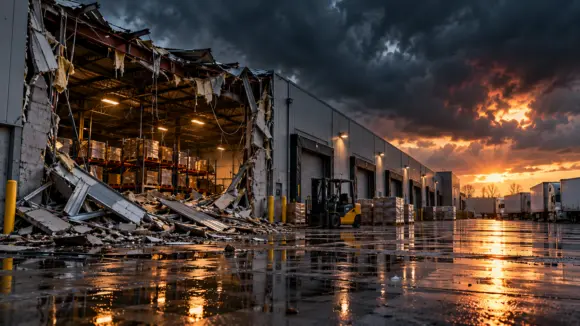
The average cost of a business interruption (BI) claim is rapidly closing in on the $1 million mark, driven by a compounding mix of natural catastrophes, fragile supply chains, geopolitical conflicts, inflationary pressures, and evolving technology-related disruptions.
According to a comprehensive new report from Allianz Commercial, which analyzed nearly 8,000 business interruption claims valued at a staggering $7.82 billion between 2021 and 2025, the average BI claim has now exceeded $950,000. This striking figure places business interruption claims roughly 70% higher than the corresponding average property damage claim over the same period, highlighting a growing disconnect between physical asset damage and the financial fallout of operational downtime.
While the overall frequency of claims has remained relatively steady over the last few years, the average financial value of these claims has surged by more than 30% annually over the past two years, the data reveals.
"What we’re seeing isn’t necessarily more claims — it’s that each claim is getting significantly more expensive," said Melissa Hill, North American head of claims for Allianz Commercial. "The biggest culprit is time. Supply chains are still fragile, and when something breaks, it takes much longer to get parts, materials, and equipment to rebuild. During that extended downtime, inflation is compounding the cost of every single day a business can’t operate."
Primary Drivers of Rising Losses
The Allianz report breaks down the leading contributors to business interruption losses, revealing that traditional man-made disasters and severe weather events continue to exact the highest tolls on corporate balance sheets.
By far the most expensive cause of business interruption claims was fire and explosion, which accounted for more than 40% of the total value of all claims analyzed. Furthermore, fire was responsible for nine of the 10 costliest man-made business interruption events examined across the five-year study window.
Natural catastrophes followed closely behind as the second most expensive cause of BI claims by value, representing 34% of losses. Notably, natural catastrophes were also the most frequent single cause of business interruption, accounting for 26% of all claims recorded. Machinery breakdown rounded out the top three leading causes by value, contributing 6% to the total losses.
The report highlights concentrated production models as an increasing structural vulnerability for modern enterprises. Many contemporary industries rely heavily on a small, highly specialized pool of suppliers or singular manufacturing facilities. When a single node in this tightly wound network fails, the ripple effects are felt globally. Additionally, persistent geopolitical tensions—such as the ongoing conflicts in Ukraine and Iran—have continued to drive up energy prices, elevate logistics costs, and place unprecedented pressure on international trade routes.
The Quiet Impact of Tariffs
Beyond dramatic events like fires and natural disasters, trade policy is emerging as a critical yet often overlooked factor inflating claims. According to the Allianz report, tariffs are actively adding real cost and complexity to the recovery process.
"Tariffs are one of those factors that don’t always make headlines in the insurance world, but they’re quietly adding real cost and complexity to claims," Hill noted. "When you impose tariffs on key building materials — take softwood lumber, where 85% of U.S. supply comes from Canada — you’re directly inflating the cost of every rebuild. And in a typical property claim, about 60% of the loss is rebuilding costs, so that impact is substantial."
Beyond material costs, tariffs are generating operational delays as companies scramble to source alternative vendors or absorb unexpected financial surcharges. These friction points inevitably extend restoration timelines, lengthening the business interruption period and swelling the final payout.
"The net effect is that our loss adjustment process has become more complex, requiring more comprehensive analysis, and that added complexity comes with higher expenses across the board," Hill added.
Differing Perspectives on Future Trends
Industry experts hold divergent views on whether these escalating cost trajectories will become the permanent new normal or eventually subside.
Christopher J. Boggs, president and chief consultant of Boggs Risk & Insurance Consulting, suggests that the lingering, compounding effects of the COVID-19 pandemic may have heavily skewed the data in the Allianz report, much of which was captured during the height of pandemic-era disruptions. Boggs believes that the acute supply chain bottlenecks that defined the pandemic era have largely begun to smooth out.
"Supply chains were a major issue during COVID. I tend to think that has begun to smooth out," Boggs said, pointing out that the study period began during the early days and peak shutdowns of the health crisis.
Looking forward, Boggs anticipates that future BI claim costs will eventually retreat closer to historic norms. "My opinion is that the research over the following five years — Jan. 1, 2026, to Dec. 31, 2030 — will see the cost drop closer to the pre-COVID averages," he stated. "Remember, business income losses are based on the period the business is shut down."
However, Matt Weaver, an attorney with Reed Smith who specializes in insurance recovery, offers a less optimistic outlook. While acknowledging that COVID-19 played a role in the historical data, Weaver argues that structural economic shifts and escalating global instability will ensure that claim costs continue their upward trajectory.
"There’s no stopping the trends in that report," Weaver said. "You’ve got more global uncertainty in the supply chain, you can see that in what’s happening in the Middle East. You’ve got more concerns about AI. You’ve got, currently, less frequent natural disasters, but when they happen, they’re more severe. There’s been a lot of data about that, especially with hurricanes. So, this notion that business interruption is getting more severe, you’re going to keep seeing that."
The Rise of Cyber and Long-Tail Catastrophe Losses
The Allianz report also underscores the growing threat of non-physical disruptions, noting that cyber incidents are becoming a significant source of business interruption losses. Ransomware attacks, cloud outages, and flawed software updates are frequently disrupting business operations and rippling swiftly through interconnected supply chains.
While ransomware remains the primary driver of cyber-related BI, other IT failures—including widespread cloud service outages and problematic software updates—accounted for a meaningful share of large cyber losses. The report tracked more than 48,000 individual outages across cloud and software services in 2025 alone.
At the same time, physical catastrophes are leaving longer-lasting footprints. Prolonged recovery periods following major weather events continue to inflate BI totals. For example, many business interruption claims stemming from Hurricane Helene, which struck in September 2024, remained unresolved long after landfall because affected businesses required extensive time to rebuild. Ongoing supply chain delays, severe labor shortages, and volatile material costs have systematically stretched out recovery periods.
Hill described Hurricane Helene as "a textbook example" of a long-tail natural catastrophe loss characterized by a cascading operational effect.
"Helene wiped out critical infrastructure in places like Spruce Pine, North Carolina, which supplies roughly 85% of the world’s high-purity quartz for semiconductors," Hill explained. "You can’t just relocate that kind of specialized production overnight, and the downstream disruption rippled across the global tech supply chain for months."
Furthermore, severe bottlenecks in repairing foundational local infrastructure—such as roads, rail systems, and local utilities—further delayed commercial resumption.
"The big takeaway for adjusters is that you have to think beyond the physical repair timeline from day one," Hill said. "If you’re not accounting for supply chain dependencies and infrastructure recovery in your early estimates, you’re going to be chasing the true loss figure for a very long time."
As the severity and complexity of these claims mount, insurance recovery experts anticipate that the market for business interruption coverage will inevitably tighten. Weaver predicts that companies seeking BI protection will likely face a more restrictive underwriting environment moving forward.
"To the extent companies are using it, they might have higher deductibles or higher waiting periods or other things that limit what they can actually recover," Weaver said. "So the industry is going to respond to increased severity how they always respond to increased severity, which is you’re going to have more expensive coverage and you’re going to have less of it."








No comments yet. Be the first to join the conversation!