
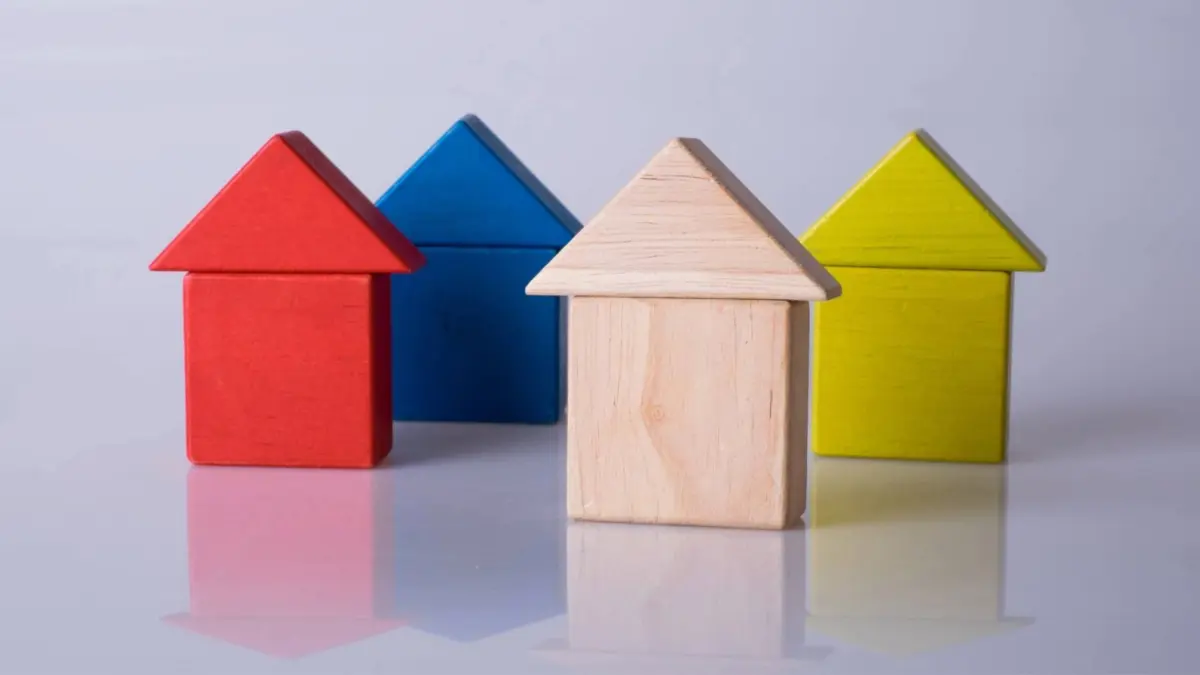
When advising real estate investors, seasoned wealth managers often emphasize a fundamental truth about the tax code: it does not respond to emotion. Instead, it offers substantial rewards to those who understand how to select the right financial instruments at the exact moment they are needed. Yet, a widespread pitfall in wealth planning is the treatment of complex vehicles like 1031 exchanges, Delaware statutory trusts (DSTs), and Qualified Opportunity Zones (QOZs) as one-size-fits-all solutions. Relying on a single tax-deferral strategy for every financial profile is akin to a medical practitioner prescribing an identical medication to every patient who walks through the door. While certain remedies are effective in specific contexts, they fail to resolve unrelated financial challenges.
To illustrate how sophisticated tax strategies operate in practice, financial experts frequently examine four distinct investor profiles, each navigating a unique set of circumstances, and pair them with the specific financial tool designed to address their challenges.
Henry: The stock market refugee
Henry spent a quarter-century building a seven-figure stock portfolio, only to face the sudden market volatility driven by the tariff adjustments of late 2025 and the subsequent energy crisis of 2026. Within a matter of weeks, a decade of market gains eroded, leaving him grappling with financial uncertainty and a diminished appetite for Wall Street’s fluctuations. Ready to exit his positions, Henry realized that liquidating his holdings would trigger a substantial capital gains tax bill. He sought an asset class that offered tangible security—something insulated from daily market volatility.
For Henry, the solution lies in a Qualified Opportunity Zone Fund (QOF). By reinvesting his stock market capital gains into a QOF within 180 days of realization, his original tax liability is deferred. Furthermore, if he maintains the QOZ investment for at least ten years, any subsequent appreciation becomes entirely tax-free, allowing the growth on his new assets to bypass federal taxation.
Recent legislative updates, including the provisions introduced under the One Big Beautiful Bill Act (OBBBA), have cemented the Opportunity Zone program as a permanent fixture. These updates include a rolling five-year deferral framework for capital gains reinvested after December 31, 2026, alongside a 10% basis step-up for investors who maintain their positions for a minimum of five years.
For stock market participants seeking to pivot toward tangible real estate while securing tax relief, QOZs serve as an effective transition vehicle. Crucially, while Henry could not utilize a traditional 1031 exchange because he was liquidating equities rather than real estate, the QOZ framework accommodates capital gains generated from nearly any asset class, including stocks, cryptocurrency, privately held businesses, and fine art, cementing its versatility as a capital gains management strategy.
Rachel and Tom: The divorcing couple
Unforeseen life changes frequently collide with complex asset portfolios, as demonstrated by Rachel and Tom. Joint owners of three rental properties, the couple faced the necessity of dividing their shared holdings during divorce proceedings without surrendering a third of their equity to the Internal Revenue Service. Liquidating the properties and splitting the cash proceeds would have triggered devastating federal and state capital gains liabilities, alongside depreciation recapture penalties, severely depleting the net value available to either party.
To mitigate this exposure, Rachel and Tom utilized a 1031 exchange coupled with Delaware statutory trusts. By working through a qualified intermediary, they sold their jointly held properties under the provisions of a 1031 exchange. Instead of purchasing new replacement properties together—an arrangement rendered untenable by their personal circumstances—they each directed their respective exchange proceeds into separate DST investments.
DST investments enable individual investors to hold fractional ownership interests in institutional-grade commercial real estate, such as Class A multi-family apartment complexes or logistics distribution centers, with minimum thresholds typically beginning around $100,000. This approach granted each party an independent portfolio, distinct monthly distribution streams, and individual tax deferral, effectively dissolving their joint ownership liabilities and eliminating operational friction regarding property management.
Additionally, the DST structure circumvents the rigid 45-day property identification window that frequently jeopardizes standard 1031 exchanges. Because DST properties are pre-packaged and acquired in advance by professional sponsors, investors can secure replacement assets efficiently, even amidst complex personal transitions. This mechanism provides a clean separation of assets while minimizing tax liabilities.
Sofia: The empire builder
At age 42, Sofia approached real estate investment with a long-term accumulation strategy. Holding a small portfolio of single-family rental homes, her objective was not immediate passive income generation, but rather the systematic consolidation of smaller assets into high-performance commercial real estate to construct lasting generational wealth.
Sofia’s strategy centered on a classic 1031 exchange in its purest form. By selling her two single-family rentals for a combined valuation of $800,000 and rolling the gross proceeds into a 20-unit multi-family residential building valued at $2 million—while financing the remainder through commercial debt—she deferred all capital gains taxes. Consequently, every dollar of earned equity remained actively deployed within the market.
Executing a 1031 exchange shields investors from the immediate tax drag of federal and state capital gains levies and depreciation recapture. Had Sofia liquidated her holdings without this mechanism, her capital base would have been significantly reduced, limiting her borrowing capacity and restricting her acquisition scale. Instead, the tax-deferred rollover enabled her to secure a larger commercial asset, establishing a compounding foundation for future portfolio expansion.
Over a multi-decade horizon, investors can execute successive 1031 exchanges, trading up into increasingly substantial commercial assets, such as retail centers or industrial complexes. Furthermore, if an investor maintains ownership of their ultimate real estate holding until death, heirs benefit from a stepped-up cost basis, which can eliminate accumulated deferred capital gains taxes entirely, forming the cornerstone of an effective estate preservation strategy.
Raymond: The high-income professional
As a high-earning medical specialist with an annual income exceeding $800,000, Raymond faced a substantial annual tax liability. His primary objectives were securing reliable passive income streams independent of his clinical schedule and maximizing legitimate tax deductions to lower his overall exposure.
Raymond implemented a dual-track strategy combining Delaware statutory trusts and Qualified Opportunity Zones. By allocating capital directly into DSTs that offered accelerated depreciation benefits—supported by the restoration of 100% bonus depreciation rules—he was able to offset a substantial portion of his ordinary income with paper losses generated by the real estate investments, thereby reducing his immediate tax burden without diminishing his underlying wealth.
Simultaneously, Raymond directed a portion of his investment gains into a Qualified Opportunity Zone fund, initiating the ten-year holding period required to secure tax-free appreciation. The permanence of the Opportunity Zone program under current tax frameworks provided him with an extended horizon to compound returns free from annual capital gains taxation.
The integration of DST-driven depreciation benefits and QOZ long-term growth vehicles provides high-earning professionals with a multi-faceted approach to wealth management. This combination delivers recurring passive distributions, immediate liability reduction, and long-term asset appreciation, all without requiring direct operational involvement in property management.
Navigating the complexities of tax-advantaged real estate requires aligning specific financial tools with individual investor profiles. Financial advisers emphasize that inaction often results in suboptimal tax outcomes, making it essential for investors to evaluate their complete financial picture and collaborate with professionals capable of tailoring strategies to their specific circumstances.








No comments yet. Be the first to join the conversation!