
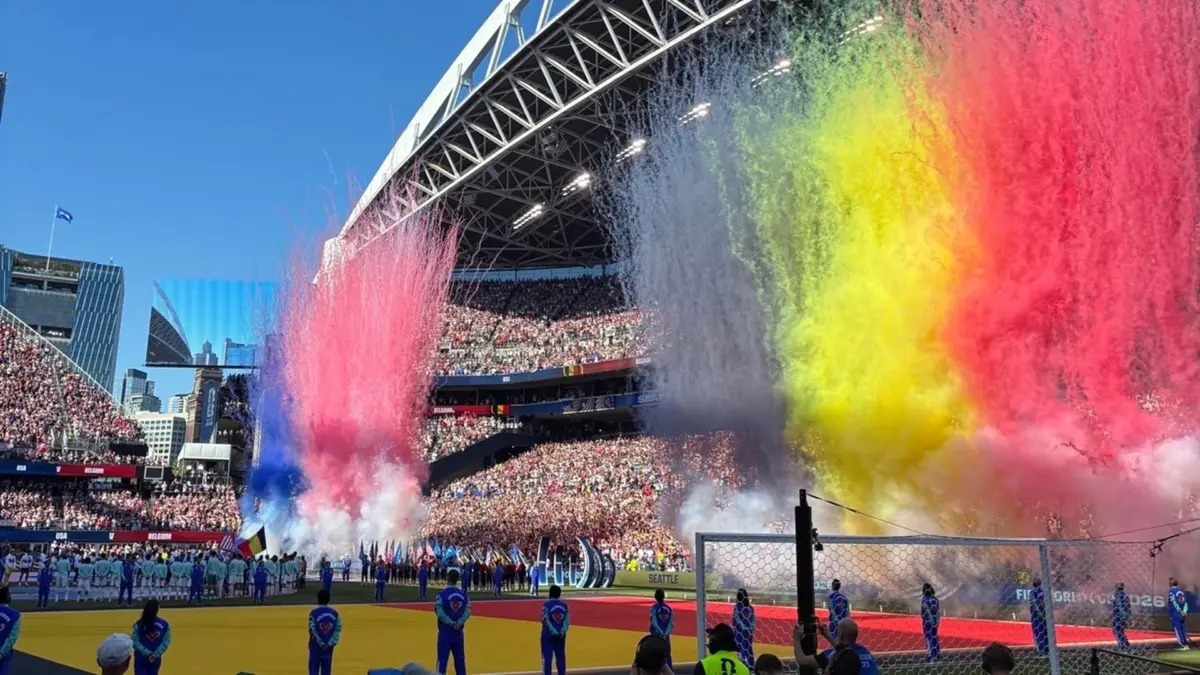
Sitting high in the stands in Seattle at what would sadly be the U.S. soccer team’s final appearance of the 2026 World Cup, the view offered a stark reminder of why financial planning ultimately serves a greater human purpose. The journey to that seat began weeks earlier, bouncing around the idea of attending ever since the national team qualified for the round of 32. Yet, like many people facing spontaneous travel and high-ticket events, the initial hesitation brought a cascade of excuses to dismiss the possibility.
It was not until the eve of the match, when a timely reminder from home reframed the entire dilemma, that the hesitation vanished. With a simple, definitive phrase—"Memories over money"—the decision was made, reinforcing a philosophy that is increasingly guiding how individuals view the true return on investment of a lifetime of careful saving.
As the president of Exit 59 Advisory, reviewing client communications provides a unique window into the milestones that truly matter to people. The most rewarding emails received from clients rarely focus solely on a portfolio milestone or a tax-optimization strategy. Instead, the messages that stand out feature spontaneous declarations of lived experience. They tell stories of sudden getaways, long-planned adventures, and commitments to shared moments. The best among them echo that exact family refrain: "Memories over money."
While this perspective might initially sound counterintuitive coming from a financial planner whose daily work revolves around balance sheets, asset allocation, and tax efficiency, it represents a vital balance in modern wealth management. Financial security forms the foundational base, much like Maslow’s hierarchy of needs. There is no intention to diminish the critical importance of financial security or the fundamental requirement of having adequate resources to enjoy a stable, secure retirement.
Extensive academic research consistently demonstrates that financial security, combined with physical health and strong social connections, forms the triad necessary for true happiness in retirement. However, what changes significantly beyond the threshold of financial security is the marginal return on additional capital. Once basic security is comfortably established, accumulating more money yields diminishing returns regarding personal fulfillment.
Establishing a comprehensive financial plan naturally incorporates room for life’s significant experiences. Every sound plan includes line items dedicated to travel, family gatherings, and personal enrichment. The integration of robust financial planning software allows individuals to map out these goals, ensuring that discretionary spending aligns with long-term stability without compromising future security.
The personal journey with travel illustrates this principle across different stages of life. When my wife and I were first married and traveling without children, we caught the travel bug early. When children arrived, conventional wisdom suggested pressing pause on ambitious travel plans, at least temporarily. Yet, we chose a different path and kept traveling.
Doubters frequently argued that very young children would not retain memories of early trips, suggesting the effort and expense were wasted. Even acknowledging that validity, the trips remained immensely rewarding for the parents, fostering shared family moments. With children currently aged eight, four, and one, the experiential ledger continues to grow through family adventures. If young children derive joy and resilience from these family trips—even when logistics go awry—the impact on older children, teenagers, and grandchildren is magnified exponentially.
Carl Richards, a fellow financial planner, prominent speaker, and former personal finance columnist for The New York Times, conceptualizes this dynamic through a simple yet powerful framework. His illustrative Venn diagram features "experiences" in one circle and "people you love" in the natural overlap, with an arrow pointing directly to the intersection bearing the instruction to spend money there.
This philosophy extends far beyond elaborate travel itineraries. It encompasses deliberate spending designed to cultivate memories, as well as recognizing and appreciating moments that require no financial investment at all. Extended family gatherings, such as weekly Sunday dinners maintained consistently for over a decade, demonstrate that relational experiences provide a far superior return on investment than material purchases.
Experiences offer a unique threefold economic and emotional return that physical consumer goods simply cannot match. You receive the psychological benefit of anticipation beforehand, the active engagement during the actual experience, and the lasting value of the memory afterward.
Armed with this three-phase framework, the Sunday night before the United States squared off against Belgium in Seattle proved to be the ultimate test of the philosophy. A hasty booking yielded a flight, a single night in a hotel, and a ticket to the stadium. Although the match ultimately did not end in a victory for the home side, the absence of regret validates the underlying principle.
Embracing spontaneity and experiential spending highlights two crucial lessons about life and wealth. First, even imperfect experiences or those marred by inconvenient mishaps frequently transform into cherished memories over time. Years later, recounting the trials of traveling with a sick child on a transatlantic red-eye flight turns past stress into shared family laughter.
The second lesson involves the powerful concept of contrast. One primary reason for the deep appreciation of a whirlwind, unconventional itinerary stems from its sharp contrast with the predictable rhythms of daily life. Had such travel been routine or mundane, the experience would lack its vibrant resonance, leaving one easily distracted by everyday habits.
Daily professional responsibilities remain dedicated to helping clients build healthy balance sheets, minimize tax burdens, and optimize their overall financial structures. Yet decades of industry experience reveal a clear truth: individuals who successfully translate their accumulated financial balance sheet into a rich memory balance sheet report significantly higher levels of life satisfaction. Memories over money remain the ultimate metric of a well-managed life.
No comments yet. Be the first to join the conversation!