
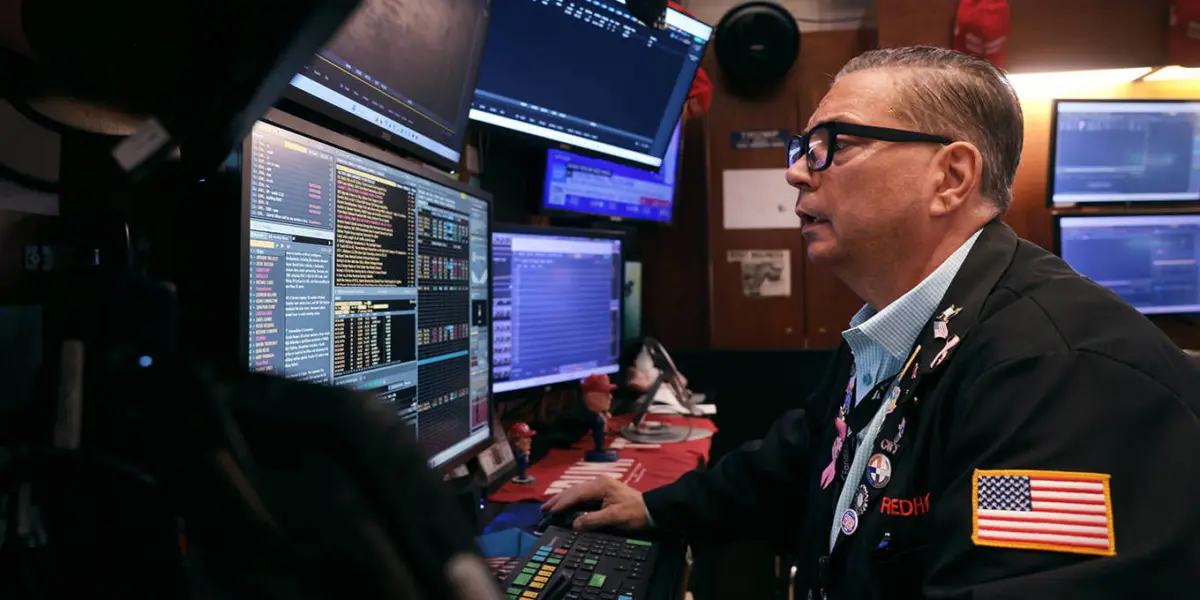
NEW YORK — For years, the global economic landscape was defined by an era of “easy money,” where interest rates hovered near zero or, in some notable cases, dipped into negative territory. Investors, policymakers, and corporations alike grew accustomed to a paradigm where the cost of servicing public debt was negligible, allowing advanced economies to finance expansive budget deficits with little immediate fiscal friction. However, that era has come to a definitive end. As of late October 2026, the financial markets are grappling with a starkly different reality: large, persistent budget deficits and climbing public debt-to-GDP ratios are no longer theoretical concerns; they have become the primary drivers of market volatility and investor anxiety.
The shift in the macroeconomic environment has been profound. With central banks having transitioned from ultra-loose monetary policies to more restrictive stances in response to inflationary pressures, the yields on government bonds—the bedrock of the global financial system—have surged. This rapid recalibration of interest rates has fundamentally altered the calculus of fiscal sustainability. As bond yields climb across the spectrum of short- and long-term maturities, the burden of servicing existing and new debt has ballooned, forcing a critical re-examination of the long-term viability of current fiscal trajectories in many of the world’s most developed nations.
The apprehension now rippling through global markets stems from a simple, yet daunting, arithmetic. When the interest rate paid on government debt exceeds the rate of nominal GDP growth, the debt-to-GDP ratio enters an upward trajectory that, if left unchecked, inevitably leads to a fiscal reckoning. For many years, advanced economies benefited from a "goldilocks" scenario where growth was sufficient and interest rates were low enough to keep debt servicing costs manageable. Today, that margin of safety has evaporated. Investors are increasingly questioning whether the current fiscal paths of major economies are compatible with long-term stability, and this skepticism is beginning to manifest in the pricing of sovereign risk.
The structural nature of these deficits cannot be overstated. In many advanced economies, the spending pressures are not merely cyclical—the result of temporary downturns—but deeply structural. Demographic shifts, characterized by aging populations, are placing unprecedented strain on pension systems and healthcare budgets. Simultaneously, there is an intensifying demand for increased government spending on national security, the energy transition, and infrastructure modernization. When these permanent spending obligations are combined with political systems that are increasingly resistant to tax increases or significant spending cuts, the result is a structural fiscal gap that requires constant, and increasingly expensive, borrowing.
The market reaction to these trends has been one of cautious, yet mounting, concern. Bond markets, which serve as the ultimate arbiters of fiscal discipline, are signaling that they are no longer willing to overlook the rising tide of sovereign debt. As yields on benchmark government securities rise, the risk premium demanded by investors for holding the debt of more heavily indebted nations is also expanding. This creates a feedback loop: as the cost of borrowing increases, the interest expense on the budget rises, which in turn widens the deficit, necessitates further borrowing, and potentially triggers higher yields.
While it is true that some countries possess more robust fiscal frameworks and stronger institutional credibility than others, the consensus among observers is that no economy is entirely immune to the gravitational pull of these macroeconomic forces. The degree of protection varies, of course. Nations with sovereign currencies, stable political institutions, and large domestic investor bases are generally better positioned to navigate periods of fiscal stress than those that are heavily reliant on foreign capital or are constrained by rigid monetary arrangements. Yet, even for the most stable of economies, the psychological threshold of what constitutes a "sustainable" level of debt is shifting.
The anxiety is particularly acute because of the potential for a crisis to be self-fulfilling. Financial markets are sensitive to perceptions of political paralysis. When investors believe that a government lacks the political will to enact necessary fiscal reforms, they may preemptively sell off that country’s debt, driving yields higher and forcing the very crisis that the policymakers had hoped to avoid. This dynamic is exacerbated by the global interconnectedness of capital markets. A spike in bond yields in one major economy can rapidly spill over into others, as global investors reassess their risk exposure and rotate their portfolios in search of safety or higher returns.
The current situation is further complicated by the fact that global debt levels were already elevated prior to the recent interest rate spikes. The emergency spending programs implemented during the pandemic—while necessary to prevent an economic collapse—left many nations with historically high levels of public debt. Now, as those governments attempt to roll over that debt in a higher-rate environment, the sheer volume of issuance is creating a supply-demand imbalance in the bond markets. This technical pressure, combined with the underlying fiscal concerns, is what keeps market participants on edge.
Looking forward, the debate over fiscal sustainability is likely to dominate the policy discourse for the foreseeable future. The challenge for policymakers in advanced economies is to thread an incredibly narrow needle: they must find a way to maintain market confidence through credible fiscal consolidation without triggering a sharp contraction in economic activity. This requires a delicate balancing act that involves either increasing tax revenues, curbing the growth of entitlement spending, or fostering higher levels of productivity-enhancing economic growth—a task that is easier said than done in the current political climate.
As we move deeper into the final quarter of 2026, the question is no longer whether interest rates will remain higher for longer, but rather how the global economy will adjust to this new reality. The era of near-zero rates masked a multitude of fiscal sins, allowing for a period of relative calm. Now that the tide has gone out, the vulnerabilities inherent in the current structure of public finances have been laid bare. Whether this leads to a controlled adjustment or a more disruptive period of market turbulence remains the defining uncertainty for the global economy. For now, the markets are watching, the debt is mounting, and the pressure on policymakers to address these structural imbalances is intensifying by the day. The sustainability of public debt, long taken for granted, has once again moved to the center stage of economic concern, reminding everyone that in the world of finance, nothing—not even the perceived safety of government bonds—remains immune to the relentless laws of arithmetic.
No comments yet. Be the first to join the conversation!