
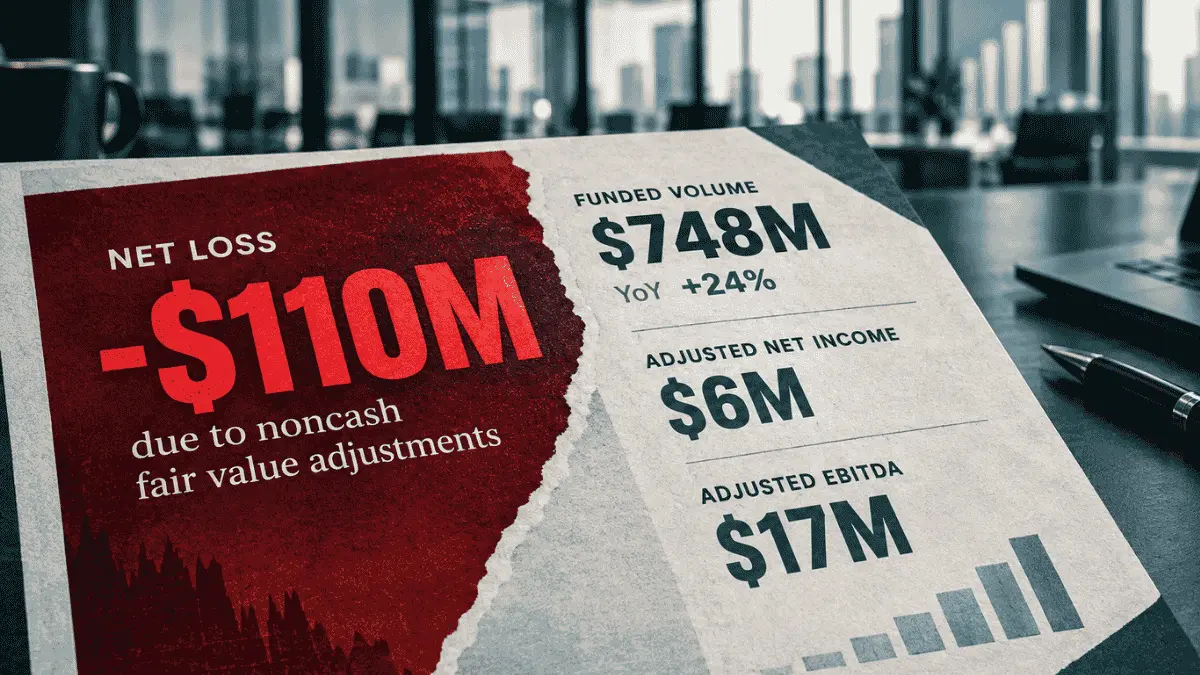
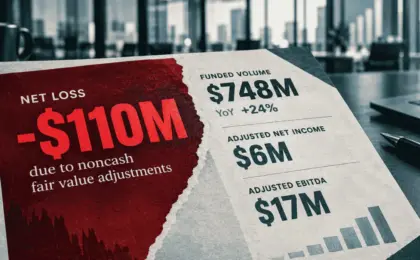
Finance of America (FOA) reported a net loss of $110 million for the third quarter of 2026, weighed down heavily by noncash fair value adjustments even as the company continued to post robust growth in its core home equity lending and retirement solutions business.
The Plano, Texas-based specialty finance and mortgage company announced on Tuesday that its funded volume for the quarter ending Sept. 30 reached $748 million, marking a 24% increase compared to the $603 million recorded during the same period in the previous year. On a year-to-date basis, FOA’s total funded volume climbed to $2.07 billion, representing a 17% expansion from the first nine months of 2025.
Despite the top-line volume growth, the company recorded a basic loss of $5.24 per share for the third quarter, a steep widening from the basic loss of 98 cents per share reported in the third quarter of 2025. Executives pointed out that the quarterly net loss was driven primarily by $125 million in noncash fair value adjustments, which pressured the bottom line despite steady operational momentum.
When evaluated on an adjusted basis, Finance of America remained profitable, posting a net income of $6 million, or 28 cents per share. This compared favorably in terms of positive territory, though it was down from the adjusted net income of $33 million, or $1.33 per share, recorded a year earlier. Meanwhile, adjusted EBITDA for the third quarter totaled $17 million, dropping from the $55 million reported in the third quarter of 2025.
“The third quarter of 2026 demonstrated the continued strength of our platform, with funded origination volume growing 24% year over year,” CEO Graham Fleming said in a statement accompanying the earnings release. “While higher interest rates drove near-term pressure on earnings, we believe this impact is temporary. We have already taken steps to improve margins.”
During the company’s quarterly earnings call with investors and analysts, Fleming elaborated on the macroeconomic headwinds that impacted operations. He emphasized that FOA remains squarely focused on production growth, operational efficiency, and consistent cash generation. He explained that margins compressed rapidly after the Federal Reserve shifted its monetary policy stance from cutting interest rates to raising them in response to persistent inflation pressures and broader macroeconomic shifts.
“We have already made the necessary changes to product pricing, and we expect margins to return to historical levels in the first half of 2027,” Fleming told investors during the call.
Providing additional context on the broader market environment, Fleming noted that Finance of America has consistently grown its origination volumes by an average of 20% each year since 2023. However, he characterized the third quarter as uniquely challenging from an interest rate perspective. During the quarter, 10-year Treasury yields increased by more than 75 basis points—a direct market reaction to the Federal Reserve’s pivot and elevated inflationary readings.
Retirement Solutions Performance
FOA’s primary operating segment, the retirement solutions division, which originates home equity-based financing products including reverse mortgages, served as a key engine for volume expansion during the period. The segment recorded $748 million in funded volume during the third quarter, representing a 24% increase compared to the same period in 2025.
However, profitability within the segment faced immediate margin compression due to the changing rate environment.
“Our retirement solutions revenue margin was impacted in the third quarter, decreasing to 9%, compared with 11.3% in the third quarter of 2025, and a historical average since the start of 2024 of 10.7%,” Fleming said during the call. “We believe these impacts are temporary and do not change the underlying fundamentals of our business.”
Revenue for the retirement solutions segment totaled $67 million, slipping 1% from the prior-year period and declining from the $74 million reported in the second quarter of 2026. Pretax income for the segment fell to $3 million, down from $10 million a year earlier, while adjusted net income declined to $9 million from $20 million.
Company leadership reiterated that the downward pressure on profitability stemmed directly from origination margins tightening as benchmark interest rates escalated during the quarter. In response, management implemented swift product and pricing adjustments designed to mitigate this impact, expressing confidence that margins will recover to historical averages moving forward.
For the first nine months of 2026 as a whole, the retirement solutions segment generated $2.07 billion in funded volume, marking a 17% year-over-year increase. Total revenue for the first three quarters rose 14% to reach $208 million.
“Since 2023, our submission volumes have increased by 21% annually, while our funded volume has grown by 20% annually,” FOA President Kristen Sieffert said during the earnings call. “This is across our product suite, as HECM volume is up 14% year over year, HomeSafe first liens are up 15%, and HomeSafe seconds are up 63%.”
Portfolio Management Performance
In contrast to the origination-focused retirement solutions business, FOA’s portfolio management segment—which generates revenue through net interest income and fair value changes on portfolio assets—experienced more pronounced financial headwinds during the quarter.
The portfolio management segment reported a pretax loss of $138 million for the third quarter of 2026, widening significantly from the $11 million pretax loss recorded in the third quarter of 2025. The company attributed this loss primarily to negative noncash fair value adjustments associated with retained interests in securitizations. On an adjusted basis, the portfolio management unit reported a net income of $11 million, down from $30 million in the same period last year.
Despite the accounting adjustments and pretax losses, the scale of the portfolio continued to expand. Assets under management within the segment increased by 23% year over year, reaching $37.4 billion at the close of the quarter. This growth was driven by ongoing organic originations as well as the strategic acquisition of Onity Mortgage Corp.’s Home Equity Conversion Mortgage (HECM) servicing portfolio, which officially closed on July 1.
Looking at the broader year-to-date figures for the first nine months of 2026, the portfolio management segment recorded a cumulative pretax loss of $128 million, a stark shift from the $202 million in pretax income generated during the first nine months of the previous year. Adjusted net income for the segment stood at $57 million for the year-to-date period, down slightly from $66 million in 2025.
Capital Position and Outlook
Finance of America closed out the third quarter with a strengthened balance sheet regarding its liquidity position. The company reported $118 million in cash and cash equivalents as of Sept. 30, up notably from the $85 million reported at the end of June. Management attributed this liquidity accumulation to steady cash generation from originations and ongoing capital markets activity.
Total stockholders’ equity stood at $307 million as of the end of September, which included $259 million attributable to common stock. This resulted in a book value of $28.08 per common share.
Capitalizing on its cash position, the company announced plans to complete a $60 million paydown of its senior secured notes in November, a move aimed at deleveraging its balance sheet.
Looking ahead to the final quarter of 2026, Chief Financial Officer Matt Engel outlined an optimistic outlook for origination volume. Engel stated that the company expects funded volume in the fourth quarter to reach between $3.1 billion and $3.4 billion, a projected range supported by favorable consumer demographics, the breadth of the company’s product offerings, and ongoing improvements in conversion efficiency.
No comments yet. Be the first to join the conversation!