
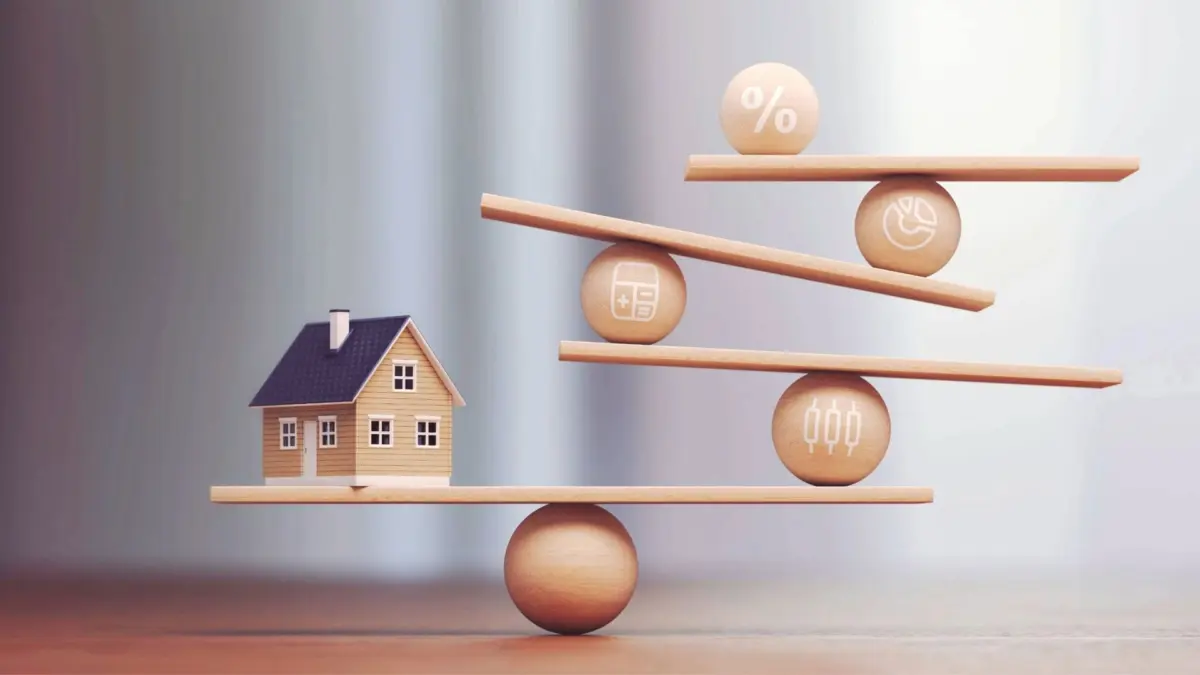
For generations, real estate has occupied a hallowed space in the portfolios of individual and institutional investors alike. It is frequently marketed as the ultimate asset class—a rare combination offering robust appreciation potential, steady income streams, lucrative tax breaks, and a dependable hedge against the erosive effects of inflation. For decades, this stellar reputation has been well-earned. Real estate investments have historically delivered on these diverse fronts while simultaneously providing essential portfolio diversification and giving investors a tangible stake in physical property.
Yet, those very same promises that have drawn capital into property markets for years can quietly undermine an investor who takes them for granted. In the modern economic landscape, pillars like property appreciation, investment yield, tax depreciation, and inflation protection are not built-in guarantees. Instead, they are fundamental assumptions. Unless investors develop a granular understanding of the specific macroeconomic and microeconomic factors driving each pillar, they risk deploying capital into ventures they fundamentally do not understand. As the property market navigates a radically altered financial environment, examining the reality behind these four traditional benefits is more critical than ever.
Appreciation
Appreciation traditionally commands the lion’s share of investor attention. Whether riding a powerful upward market trend or executing a value-add flip to capture a quick margin, capital appreciation represents the most visible upside real estate has to offer. However, it is also the least certain outcome to actually materialize on a balance sheet.
For an extended period, an era of historically cheap debt and steadily rising valuations made property appreciation feel like a near-certain bet. Investors could rely on the rising tide of broader economic expansion to lift property values regardless of minor operational missteps. Then, interest rates shifted upward rapidly, fundamentally altering the underlying math of property valuation. The market environment of today bears little resemblance to the hyper-stimulated conditions seen just five years ago.
This volatility underscores the inherent nature of appreciation: it is inextricably tied to macroeconomic winds that remain notoriously difficult to predict. For substantial, broad-based appreciation to return to the current housing and commercial markets, two primary pressures must resolve. First, existing excess inventory must be fully absorbed by organic demand, and second, interest rates must recalibrate downward. While those conditions may materialize over the next half-decade, there is no guarantee they will. In a market defined by these dynamics, appreciation should be treated strictly as an opportunistic upside rather than the foundational baseline upon which an investment thesis relies.
Yield
A sound real estate investment must perform from day one by generating immediate, reliable cash flow. Without dependable income underneath a deal, an investment lacks a vital financial floor when broader valuations retreat or capital markets tighten. Operating cash flow is what services existing debt obligations, keeps day-to-day property operations flowing smoothly, and protects investors from having to cross their fingers for future appreciation just to break even.
In today’s saturated, low-cap-rate markets—where many buyers naturally concentrate their searches—securing meaningful yield has become increasingly difficult. A property generating a modest 4% to 5% return on its purchase price annually leaves an extremely narrow margin of error once debt service, insurance, and maintenance costs are accounted for.
To find genuine yield, investors are increasingly forced to look beyond the major primary hubs where massive institutional capital dominates. Secondary markets—smaller cities and overlooked metropolitan areas featuring authentic organic demand without wildly inflated asset prices—often provide the breathing room necessary for operational income to comfortably cover debt service while still putting cash directly into the investor’s pocket.
Ultimately, a viable investment should never require aggressive future rent growth or an assumption of an eventual lower-rate refinance to function. While operational improvements that enhance revenue can serve as a welcome bonus, the fundamental cash flow must be rock-solid from the moment the acquisition closes.
Depreciation
Depreciation provides one of the most powerful mechanisms in the tax code, allowing investors to claim a paper loss against real operating income even though no actual cash has left their pockets. While various asset classes experience depreciation, real estate remains uniquely positioned: it can simultaneously generate operational revenue and appreciate in the physical world while producing a substantial tax loss on paper.
Under current Internal Revenue Service guidelines, owners are generally permitted to deduct the gradual wear and tear of a property over a standardized schedule—27.5 years for residential real estate and 39 years for commercial properties. However, utilizing a specialized cost segregation study allows investors to accelerate a significant portion of a property’s structural value, often capturing between 30% and 40% in bonus depreciation during the very first year of ownership.
The landscape governing these rules has experienced notable shifts. Legislative adjustments, such as provisions enacted through federal tax policy over recent years, have periodically altered the viability of 100% bonus depreciation, demonstrating that these policies remain subject to legislative changes. Because tax laws evolve, investors must ensure their financial strategies align directly with the active tax code rather than relying on outdated assumptions about perpetual write-offs.
Inflation Hedging
The theoretical mechanics behind real estate’s reputation as an inflation hedge are straightforward. As inflation drives consumer prices higher, rental rates theoretically follow suit, allowing real estate income to grow proportionately even as the broader purchasing power of currency declines. However, the operational economics of rental housing are rarely that simple in practice.
Rental rates are ultimately dictated by the timeless forces of local supply and demand, not by the movements of the Consumer Price Index. A landlord simply cannot unilaterally raise rents by 5% merely because annual inflation sits at 5% if competing properties sit vacant down the street and prospective tenants have viable alternative housing options.
This disconnect is currently evident across numerous regional markets that experienced heavy apartment and multi-family construction over the past decade. When regional vacancy rates climbed sharply, broad macroeconomic inflation became entirely irrelevant to local pricing power. The sheer volume of excess housing supply forced landlords into aggressive price competition, causing local rents to flatten or decline.
Stronger, more reliable inflation hedging is typically found in sub-markets characterized by durable, resilient demand and genuinely constrained supply. Markets featuring stable population growth combined with strictly limited new construction possess the fundamental economic traits that grant a property true pricing power during inflationary cycles.
The Real Question
Real estate is not a financial magic wand. It remains an asset class governed by economic reality, requiring rigorous evaluation one investment at a time within the context of broader market cycles and shifting trends.
Electing to omit real estate entirely from a diversified portfolio means missing out on some of the most flexible investment structures available. Yet, treating the historical benefits of property investing as intrinsic, unconditional guarantees is a dangerous oversimplification.
Investors must carefully examine the prevailing tax codes, macroeconomic indicators, and hyper-local market conditions that underpin every prospective real estate venture. When the underlying fundamentals of a deal are sound, the traditional benefits of the asset class will naturally take care of themselves.








No comments yet. Be the first to join the conversation!