
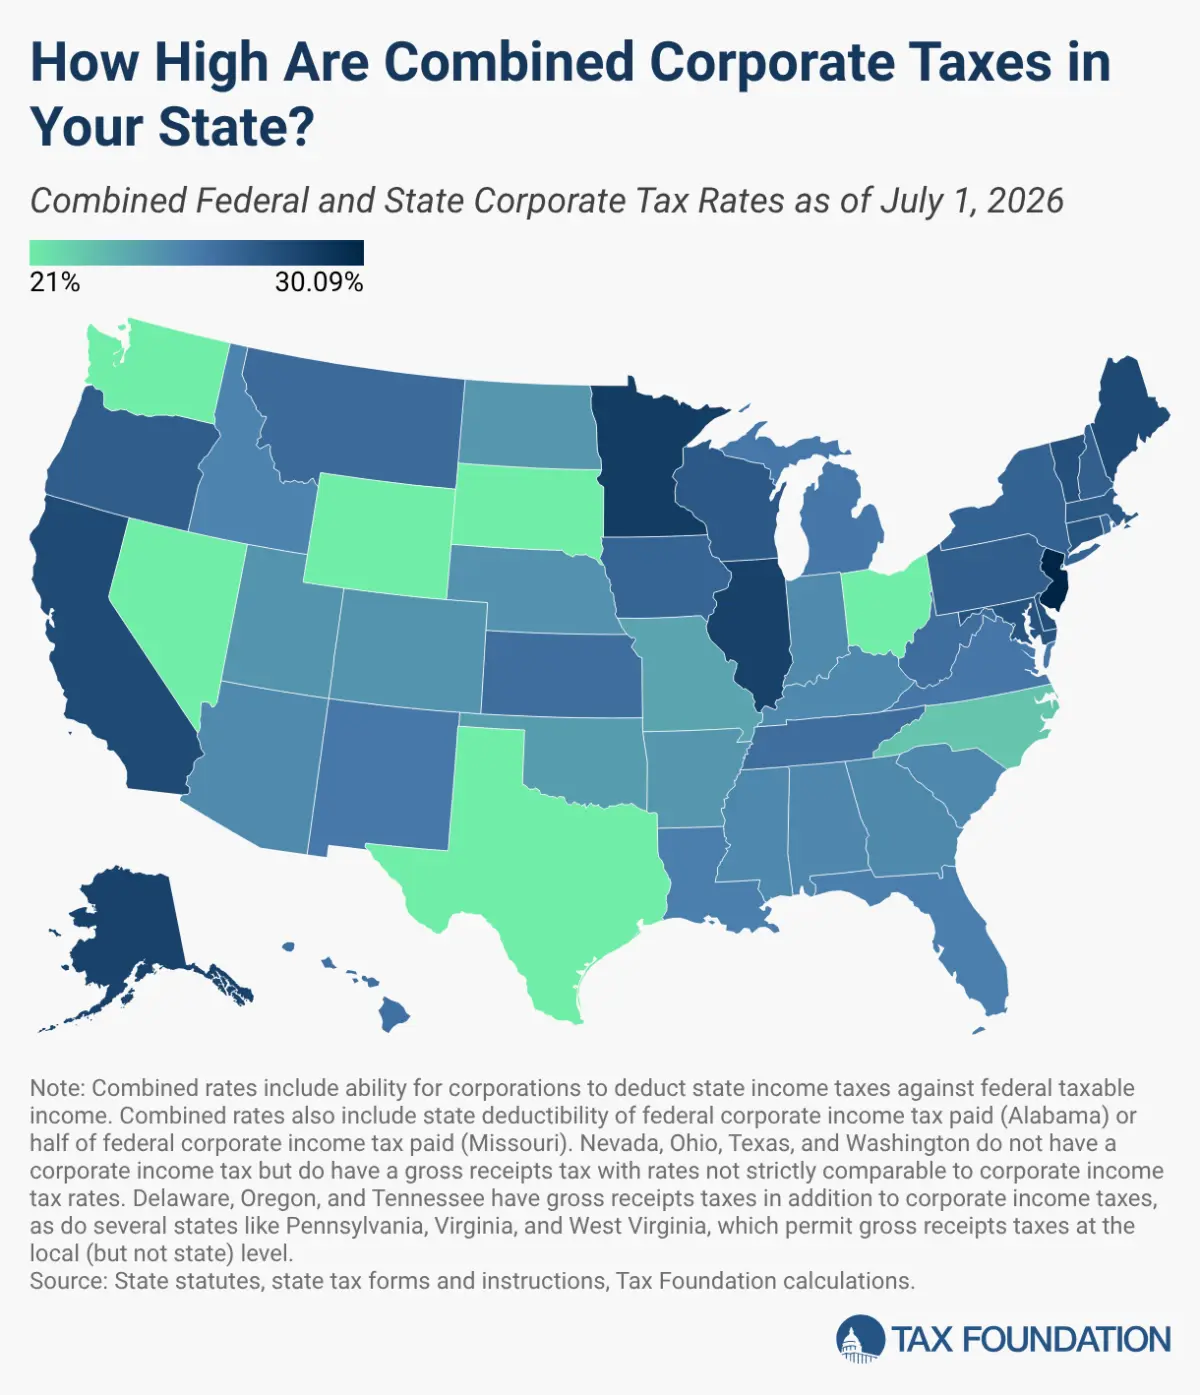
When corporations operate within the United States, they face a multilayered tax environment that extends far beyond the federal government. At the core of this framework is the federal corporate income tax, which is levied at a flat rate of 21 percent. However, understanding the true tax burden carried by American businesses requires looking closely at the state level, where forty-four states and the District of Columbia also impose their own taxes on corporate income.
The landscape of state-level corporate taxation is marked by significant diversity in both structure and rates. Across the states that levy a corporate income tax, top marginal rates vary widely, stretching from a modest 2.0 percent in North Carolina up to a hefty 11.5 percent in New Jersey. Furthermore, states diverge in how these brackets are structured. Thirteen states employ a graduated corporate income tax system, where rates increase as a company’s profits rise. Meanwhile, a larger share—31 states and the District of Columbia—opt for a flat rate on corporate income, providing a single, predictable percentage for businesses operating within their borders.
The variety of approaches does not stop at income taxes. In a handful of jurisdictions, corporations encounter alternative mechanisms known as gross receipts taxes. In Nevada, Ohio, Texas, and Washington, businesses are subject to gross receipts taxes instead of traditional corporate income taxes. Unlike a standard sales tax, which is assessed at the final point of retail sale, a gross receipts tax is applied directly to a company’s total gross sales without allowing deductions for ordinary business expenses such as employee compensation, the cost of goods sold, or general overhead costs. Because these taxes apply to transactions at every stage of the production process, they can lead to a phenomenon known as tax pyramiding, where the tax is compounded at multiple levels of production before a good or service reaches the final consumer.
Adding to the complexity, some states combine multiple approaches. Delaware, Oregon, and Tennessee impose both a traditional tax on corporate income and a separate levy on gross receipts. Other states, such as Pennsylvania, Virginia, and West Virginia, do not impose gross receipts taxes at the state level, but allow local municipalities to levy them. On the other end of the spectrum, only two states in the entire country—South Dakota and Wyoming—levy neither a corporate income tax nor a gross receipts tax, leaving corporations in those jurisdictions free from direct state-level taxes on their business activities or revenues.
When federal and state policies are combined, the overall tax pressure on corporations shifts dramatically depending on geography. The state with the highest combined corporate income tax rate in the nation is New Jersey, where businesses face an aggregate rate of 30.1 percent when factoring in federal obligations. Several other states also push total rates into the higher tiers; in Alaska, Illinois, Maine, and Minnesota, corporations face combined corporate income tax rates at or above 28 percent. Conversely, the six states that levy no state corporate income tax—Ohio, Nevada, South Dakota, Texas, Washington, and Wyoming—expose corporations only to the federal rate of 21 percent, though four of those states offset the absence of an income tax by implementing statewide gross receipts taxes.
Calculating the final tax liability is further complicated by the interaction between federal and state tax codes. Corporations are generally permitted to deduct state corporate income taxes paid against their federal taxable income. This deduction effectively lowers the corporation’s federal tax liability, softening the blow of the combined rates. For example, a corporation subject to Rhode Island’s flat 7 percent corporate income tax may deduct that state tax paid against the 21 percent federal corporate income tax. This deduction reduces the effective federal rate to 19.53 percent, resulting in a combined rate of 26.53 percent rather than a simple addition of the two nominal rates.
Conversely, a small number of states offer relief by allowing corporations to deduct federal corporate income tax liability against a portion of their state corporate income tax. Alabama stands out by allowing full deductibility of federal corporate income tax liability against state liability, while Missouri permits a 50 percent deduction of federal corporate income tax liability. These rare provisions further reduce the effective corporate income tax rate faced by businesses operating within those borders.
When averaging across all fifty states—including those that impose no corporate income taxes whatsoever—the average combined state and federal corporate tax rate in the United States sits at 25.5 percent. Economists and policy experts emphasize that evaluating the true cost of doing business requires looking at this total combined burden rather than focusing exclusively on federal figures.
Tax policy analysts frequently point out that corporate income and gross receipts taxes are among the most economically damaging ways for governments to raise revenue. Because these levies directly impact capital investment, business expansion, and labor productivity, tax reform in this area is widely viewed as a promising avenue for states looking to increase their overall competitiveness. By modernizing their tax codes and reducing these burdens, lawmakers can foster a more hospitable environment for economic growth, ultimately generating benefits that extend to both companies and the workers they employ.








No comments yet. Be the first to join the conversation!