
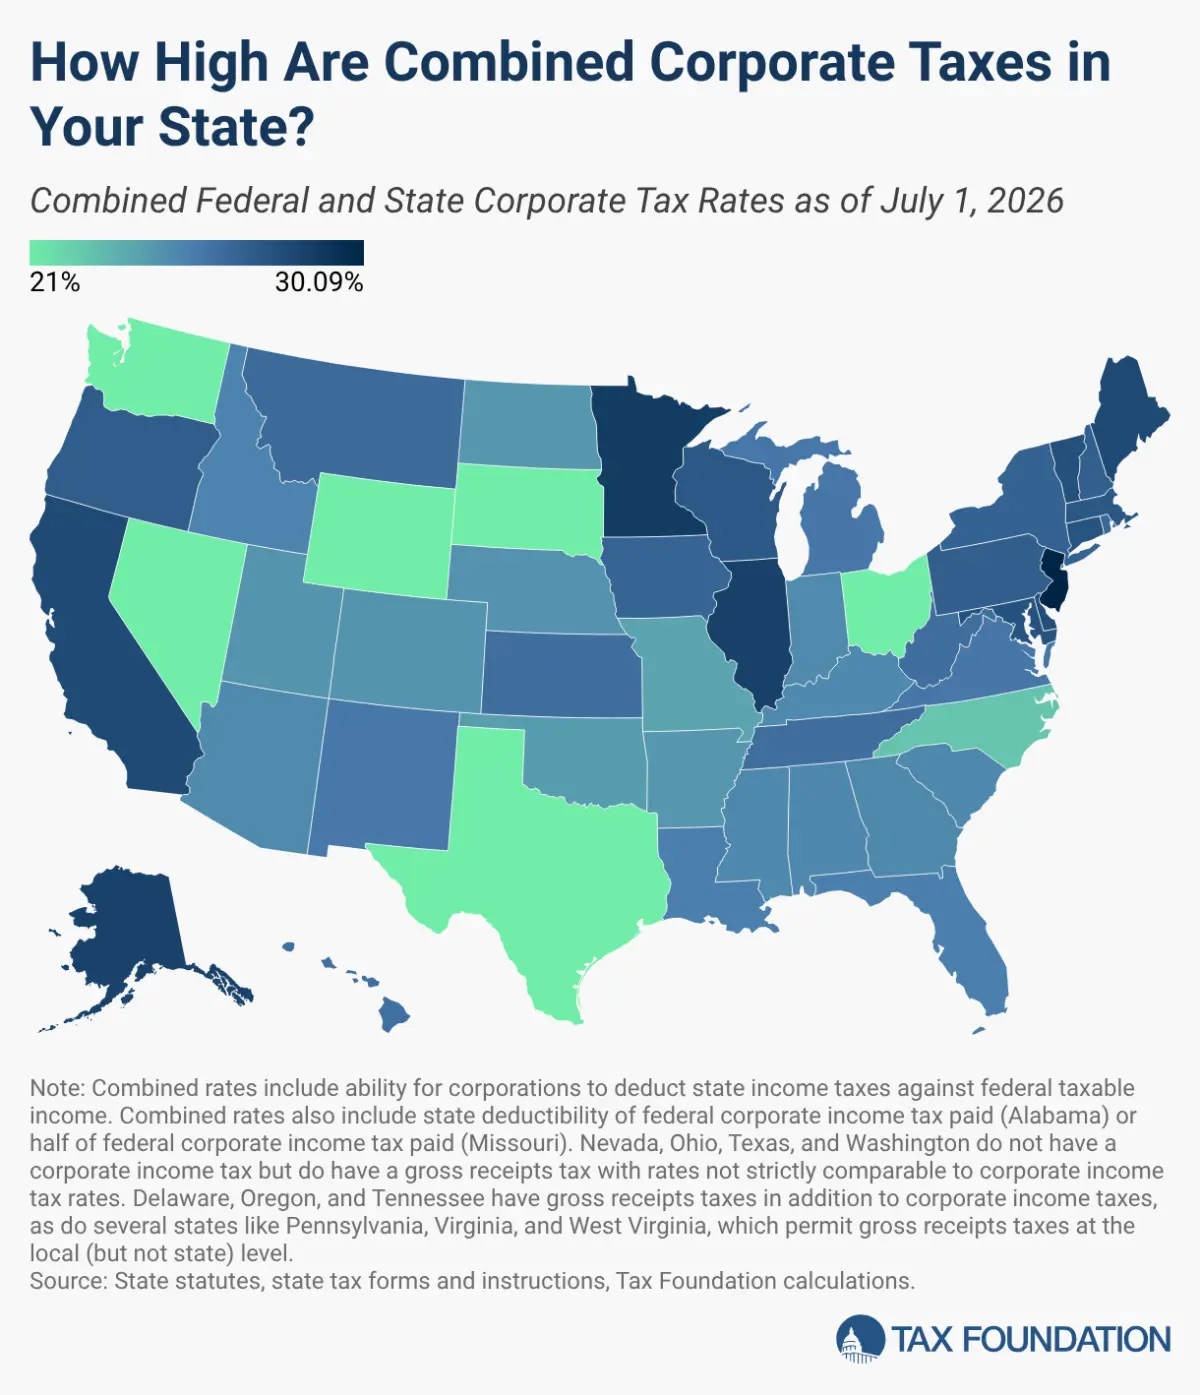
When corporations evaluate their tax obligations in the United States, they must navigate a complex, multi-layered system that combines federal mandates with a diverse patchwork of state-level policies. At the federal level, corporations are subject to a corporate income tax levied at a flat rate of 21 percent. However, the true tax burden a company faces rarely stops at the federal border. Forty-four states and the District of Columbia also impose their own taxes on corporate income, creating a wide spectrum of marginal rates, structural designs, and compliance requirements that can significantly alter a firm’s bottom line depending on where it chooses to operate.
State-level top marginal corporate income tax rates vary dramatically across the country. On the lower end, North Carolina imposes a top rate of just 2.0 percent, while New Jersey maintains the nation’s highest top marginal rate at 11.5 percent. When these state rates are combined with local levies and the federal requirement, the total tax burden climbs even higher. The state with the highest combined corporate income tax rate in the nation is New Jersey, where businesses can face a combined rate reaching 30.1 percent. Other states, including Alaska, Illinois, Maine, and Minnesota, also push corporations toward heavy tax burdens, with combined rates sitting at or above 28 percent.
The structural approach to taxing corporate income also differs significantly from one jurisdiction to the next. Among the 44 jurisdictions that levy a corporate income tax, 13 states utilize graduated tax brackets, applying higher rates as a corporation’s income increases. Meanwhile, 31 states and the District of Columbia opt for a flat rate structure, applying a single percentage to all taxable corporate income regardless of the firm’s total earnings.
Beyond traditional corporate income taxes, several states take alternative approaches to business taxation. In Nevada, Ohio, Texas, and Washington, corporations are not subject to a corporate income tax at all. Instead, these states levy gross receipts taxes. Gross receipts taxes are applied directly to a company’s gross sales, without allowing deductions for standard business expenses such as employee compensation, the cost of goods sold, or facility overhead costs. Unlike a standard retail sales tax, a gross receipts tax is assessed directly on businesses and applies to transactions at every stage of the production process. This cascading effect often leads to what economists call tax pyramiding, where the tax is compounded multiple times before a product or service ever reaches the final consumer.
The landscape becomes even more intricate in states that mix and match these policies. Delaware, Oregon, and Tennessee impose both a traditional corporate income tax and a separate levy on gross receipts. Meanwhile, Pennsylvania, Virginia, and West Virginia do not impose statewide gross receipts taxes, but they do allow local municipalities to levy gross receipts taxes at the local level. At the other end of the spectrum, South Dakota and Wyoming stand out as complete outliers, levying neither a corporate income tax nor a gross receipts tax. For corporations operating in South Dakota, Wyoming, Nevada, Ohio, Texas, and Washington, the state-level corporate income tax rate is zero, meaning these businesses face only the federal corporate income tax rate of 21 percent, though four of these states offset the absence of an income tax with statewide gross receipts liabilities.
When calculating their total tax liabilities, corporations must also account for how federal and state tax systems interact with one another. Under current rules, corporations are generally permitted to deduct the state corporate income taxes they pay against their federal taxable income. This deduction effectively lowers a company’s effective federal corporate income tax rate. For example, a corporation operating in Rhode Island is subject to the state’s 7 percent flat corporate income tax rate. Because that state tax payment can be deducted from federal taxable income against the 21 percent federal rate, the firm’s effective federal rate is reduced to 19.53 percent. When combined with the state levy, the resulting overall rate for a corporation in Rhode Island comes out to 26.53 percent.
In a few unique cases, the flow of deductions goes the other way as well. Two states allow corporations to deduct a portion of their federal corporate income tax liability against their state corporate income tax obligations. Alabama offers full deductibility, allowing corporations to deduct their entire federal corporate income tax liability from their state liability. Missouri takes a slightly more limited approach, permitting a 50 percent deduction of federal corporate income tax liability. These federal deductibility provisions further lower the effective corporate income tax rates faced by businesses operating within those state borders.
When factoring in all jurisdictions—including the states that choose not to levy any corporate income tax at all—the average combined state and federal corporate tax rate imposed across the United States sits at 25.5 percent. This national average reflects a delicate balancing act for policymakers who must fund essential public services while attempting to maintain an attractive environment for commercial investment.
Tax policy experts emphasize that when examining the overall tax burdens carried by businesses, lawmakers and analysts must look beyond federal figures and carefully weigh the cumulative impact of state-level policies. Corporate taxes are widely regarded by economists as one of the most economically damaging ways for governments to raise revenue, largely because they can discourage capital investment, slow wage growth, and diminish productivity. Consequently, reforming corporate tax structures remains a promising avenue for states looking to enhance their competitive standing, attract new commercial enterprises, and foster broader economic growth that can ultimately benefit both companies and their workforces.








No comments yet. Be the first to join the conversation!