
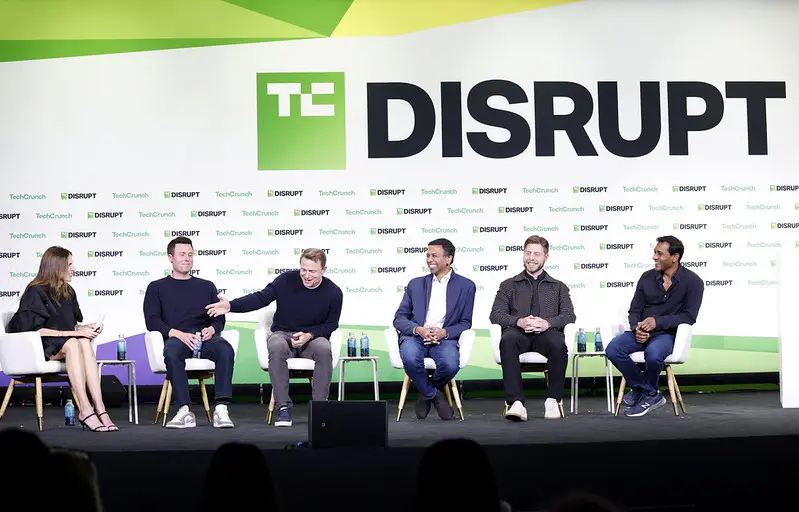
The players change, but the playbook remains remarkably resilient. When a reporter sat down with four of Benchmark’s general partners three years ago, three of those individuals have since moved on from the storied venture capital firm. Capital commitments have shifted as well; this summer, Benchmark made waves by announcing a massive $2 billion deployment plan split across two separate funds. In its 31-year operating history, the firm has only deviated from raising much smaller, tightly controlled vehicles twice.
Yet, during a panel at TechCrunch Disrupt, Benchmark’s current roster of five general partners presented a united, close-knit front that stands in stark contrast to the pedal-to-the-metal funding frenzy currently gripping Silicon Valley. While competitors rush to capitalize on the artificial intelligence boom with bloated check sizes and hyper-scaled operations, Benchmark is adhering to its historic pace: committing to just two or three new investments per partner each year. Despite an information-saturated modern landscape, their Monday partner meetings continue to operate without a formal agenda. And while broader economic indicators and market jitters point toward potential turbulence ahead, the partners remain unbothered, viewing many warning signs simply as the noisy byproduct of social-media-fueled hysteria.
Gathered together on stage, the five general partners—Peter Fenton, Ev Randall, Jack Altman, Chethan Puttagunta, and Eric Vishria—offered a rare, unfiltered look into the internal philosophy of one of venture capital’s most elite institutions.
Evolving the Core Without Losing the Craft
For decades, Benchmark’s brand has been synonymous with tight-knit, early-stage partnerships. The firm’s recent structural expansion—which includes a larger core fund alongside a $1.25 billion growth fund—raises natural questions about how an organization adapts to a changing market without diluting its identity.
Peter Fenton explained that the core fund remains fundamentally anchored to the early days of working shoulder-to-shoulder with founders. It is a relationship typically spanning 10 to 15 years, a high-touch commitment that inherently resists scaling. However, Fenton acknowledged that economic realities forced a long-overdue adjustment. The firm kept its core fund capped at $500 million for two decades, a figure that eventually lost alignment with broader macroeconomic inflation. Fenton admitted that holding the line for so long without adjustment was likely a tactical misstep.
The introduction of the growth fund, conversely, represents an intentional expansion of mandate. According to Fenton, the firm finally sought permission from the broader ecosystem to stretch beyond pure early-stage investing. In the past, missing out on mid-to-late-stage opportunities created a frustrating blind spot, as numerous companies that came across Benchmark’s desk went on to generate massive returns that the firm was structurally constrained from capturing.
When asked how the firm plans to deploy the $1.25 billion growth vehicle, Fenton emphasized a concentrated approach, noting that the beauty of their partnership lies in diverse viewpoints. Citing a recent J.P. Morgan paper detailing the "agony and ecstasy" of a concentrated portfolio, Fenton noted that if the fund succeeds, a mere one or two investments will ultimately drive 90% of its returns, suggesting a tightly bound target of four to six, or perhaps seven to eight, total bets.
A Magnet for Top-Tier Talent
For newcomers like Ev Randall, who previously spent time at Founders Fund, Bond, and Kleiner Perkins, choosing Benchmark came down to the chemistry of a small partnership. Randall noted that every venture firm ultimately mirrors the individuals who comprise it and how they collaborate. While many firms rely on massive, hierarchical structures featuring dozens of investment professionals and federated product groups, small partnerships enable a higher level of conversational throughput and fidelity. Decisions are made without wading through Byzantine corporate structures, resembling a sports team stepping out onto the field together.
Finding the right people—individuals who are not merely liked, but deeply admired and capable of mutual learning—is exceptionally rare, Randall noted. That unique dynamic drew him to Benchmark, a sentiment echoed by Jack Altman, who joined the firm in February. Altman, who famously raised a $275 million fund for his own firm in just one week as reported by the Wall Street Journal, noted that what initially drew him to Benchmark was their commitment to being the primary, trusted point of contact for founders. In an industry frequently obsessed with status and massive amounts of capital, Benchmark’s team demonstrated a genuine, foundational care for entrepreneurs. Though he enjoyed working as an independent investor, Altman admitted that navigating a volatile, fast-moving market entirely on his own held little appeal compared to learning alongside a focused, driven group of peers.
The Power of Unstructured Collaboration
That collaborative spirit is epitomized by Benchmark’s famous Monday partner meetings, which famously proceed with zero agenda. When the topic arose on stage, Chethan Puttagunta joked that Altman had tried to introduce an agenda, prompting Altman to playfully confirm he had prepared one for the upcoming week.
Eric Vishria described the lack of structure as deliberately arbitrary, serving instead as an ongoing, organic conversation. In an era of rapid technological transformation, the partners continuously evaluate what has suddenly become possible that was entirely out of reach six months prior, keeping tabs on emerging technologies and founders "bending light." Rather than forcing these discussions into rigid administrative frameworks, the five partners rely on decades-long rapport. Following the Disrupt panel, for instance, the group planned to have dinner with an entrepreneur behind a multi-hundred-billion-dollar enterprise—someone they are not even invested in—simply to challenge and stretch their own thinking.
Puttagunta emphasized that discarding formal agendas leaves vital space for reactive problem-solving. If a founder urgently needs assistance securing an executive hire or forging a critical strategic partnership, all five partners remain entirely at their disposal.
This aversion to bureaucratic friction extends to their internal decision-making process. When asked whether a single partner can unilaterally veto a deal, Puttagunta confessed that nobody actually knows because the firm maintains no hard-and-fast rules around the matter. Altman admitted he spent his early days waiting to see what protocol his colleagues would follow. Because the firm maintains a low volume of deals, a formal voting process, CRM systems, and heavy administrative rigor are entirely unnecessary.
Fenton added that avoiding arrogance is a cornerstone of the firm’s brand. Rather than acting like judges on a reality television show declaring immediate winners and losers, the partners approach early-stage opportunities with a sense of awe regarding future possibilities. If a prospective founder proves polarizing within the room, the deal typically does not move forward, recognizing that mutual alignment between the entrepreneur and the entire partnership is paramount.
Maintaining Pace and Managing Conflicts
Despite the blistering speed at which modern startups grow and scale, Puttagunta insisted that Benchmark’s investment pace remains entirely consistent. Accepting the reality of venture capital means acknowledging that a firm cannot—and should not—back every successful enterprise. When they identify an entrepreneur possessing unique strengths, their objective is simply to amplify those capabilities, working through capital structures and terms regardless of where a company happens to be positioned.
This rapid evolution, however, frequently brings modern venture capital into complex territory regarding competing portfolio companies. Vishria addressed the delicate balance of the VC-founder pact, noting that Benchmark makes an explicit commitment to work closely alongside an entrepreneur through whatever path their company takes. Yet, the harsh reality of the current tech landscape is that agile startups pivot, evolve, and expand into neighboring territory with incredible speed, inevitably introducing potential conflicts.
While emphasizing the absolute necessity of maintaining strict confidentiality, Vishria acknowledged that market dynamics are shifting, particularly in the artificial intelligence sector. Puttagunta pointed out that ultra-ambitious founders operating in the current AI landscape face near-zero coding costs, encouraging them to aggressively attack vast surface areas. While this will likely lead to more frequent overlap between portfolio companies in the future, Puttagunta maintains that professional relationships can be navigated with mutual respect and careful boundaries.
Navigating Hardware Bets and Market Volatility
Benchmark’s willingness to embrace unconventional bets was highlighted by its early investment in Cerebras, an AI chip company that represented a distinct departure from the firm’s historical focus. Vishria recalled backing the company in the spring of 2016 during its first round, marking Benchmark’s first hardware investment in a decade. Despite admitting he understood little beyond the founders’ simple thesis, Vishria pushed forward. He recounted how Peter Fenton initially told him on a Sunday night that the deal went against everything he had learned in venture capital, only to completely flip his perspective after the official Monday pitch meeting.
Reflecting on Cerebras’s turbulent public market trajectory—where shares priced at $185 during its initial public offering, surged to $350, and subsequently returned near the $185 mark—Vishria noted that public market volatility is staggering. Reviewing stock charts for companies like CoreWeave, Datadog, DoorDash, and Amazon reveals that peak-to-trough swings of 500% in a single year are remarkably common. Operating a public company, he noted, requires a titanium stomach, and employees must be prepared for the ride.
When the conversation turned to the traditional IPO process and the legacy debate championed by former Benchmark colleague Bill Gurley regarding direct listings, Vishria offered a pragmatic perspective. While direct listings have their merits, he noted that the current generation of capital-intensive AI companies requires massive amounts of funding to scale. Cerebras, for instance, raised $6 billion through its IPO, proving that traditional public offerings remain essential when capital requirements are exceptionally high.
Addressing broader macroeconomic fears—including high borrowing costs, exhausted free cash flow among AI startups, and recent high-profile bankruptcies such as Character.AI—Ev Randall dismissed macro prediction as a fool’s errand. He argued that much of the perceived panic is an artifact of the modern information ecosystem. Character.AI, for example, represented the remnants of a company whose founders and core team were acqui-hired by Google a year and a half prior for $2.3 billion; interpreting its Chapter 11 filing as a systemic chill across the AI sector is largely a product of hyperactive echo chambers on social media.
Randall pointed out that the massive valuations and capital expenditures seen across the market are tied to the surging annualized recurring revenue of private companies that will likely go public within the next year. Benchmark’s portfolio companies, he noted, continue to experience overwhelming demand, struggling only to secure enough compute capacity to serve paying customers at healthy gross margins. The ecosystem itself remains fundamentally sound; the primary pathology lies in market volatility driven by unverified data points and exaggerated rumors amplified for clicks.
The Gravity of San Francisco
As the conversation concluded, the partners addressed the geographic centralization of the tech industry, which has pulled the gravitational center firmly back to San Francisco in the age of generative AI. Altman noted that while a founder does not strictly need to be based in the Bay Area, the city unquestionably offers the easiest access to critical talent, capital, and early customers.
Fenton observed that historically, over 90% of venture capital returns have originated from companies founded locally. While rare outliers like Shopify or Ramp emerge elsewhere, the dense ecosystem effect created by successive waves of successful enterprises, ambitious executives, and rising bars of achievement is difficult to replicate systematically anywhere else.
Randall reinforced this sentiment, noting that nearly every non-San Francisco-based company he has met with over the past 18 months either maintains a local office, splits time between regions, or actively plans to relocate. In an era defined by rapid artificial intelligence breakthroughs, proximity to ambitious peers remains an unmatched catalyst for professional excellence.








No comments yet. Be the first to join the conversation!