
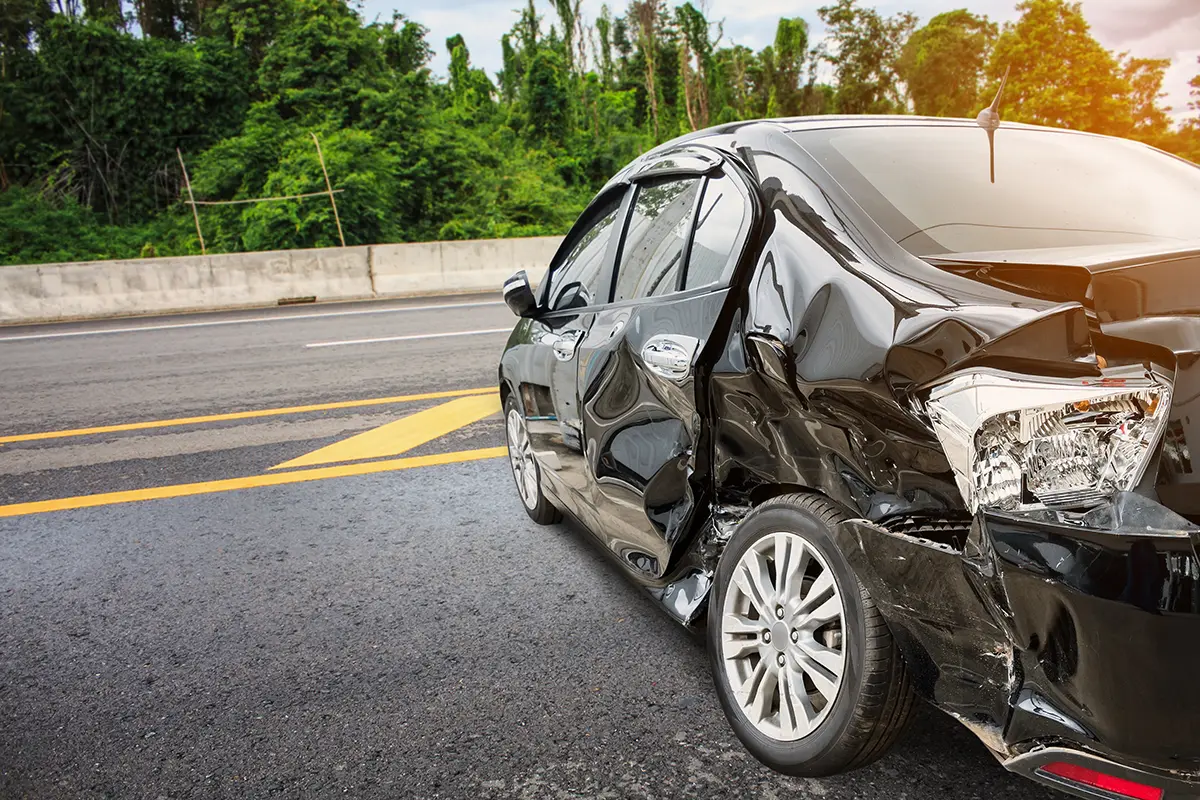
The share of auto insurance claims resulting in total losses ticked upward during the first half of the year, driven largely by an aging vehicle fleet, rising repair costs, and changing consumer behaviors that are fundamentally reshaping the auto claims ecosystem. According to the newly released 2026 Crash Course Mid-Year Update from CCC Intelligent Solutions, exactly 23.5% of all auto insurance claims were flagged as total losses in the opening six months of the year, representing a slight increase compared to the same period a year earlier.
The comprehensive industry report offers a granular look at the economic, technological, and demographic pressures currently influencing the collision repair and auto insurance industries. Chief among these trends is the growing vulnerability of older vehicles to total loss classifications. Vehicles that are seven years or older represented a staggering 74.3% of total loss valuations during the first half of the year. Within that broad demographic, vehicles between seven and 12 years old accounted for roughly 41% of total losses, showing a dramatic jump from 33.4% in 2020.
This concentration of total losses among aging automobiles underscores a persistent shift in vehicle economics. As modern automotive technology becomes increasingly complex and expensive to repair, the threshold at which an older vehicle is deemed economically unfeasible to fix continues to shrink. This dynamic is further highlighted by data concerning driveable vehicles. The share of driveable vehicles ultimately declared total losses rose to 11.2% in the first half of the year, up from 10.3% in the previous year and climbing significantly from 6.3% in 2022. Historically, more than 80% of driveable vehicles declared total losses have belonged to the cohort of vehicles that are seven years of age or older.
While total loss valuations experienced upward pressure, vehicle values themselves presented a mixed picture. The average adjusted vehicle value increased by a modest 1.2% to reach $13,594 through the second quarter of the year. However, this overall average masked a stark divergence: values for vehicles seven years or older remained relatively flat, offering little financial cushion when these older cars sustained damage.
Overall claims frequency continued its downward trajectory, declining 3.5% through September compared to the same period in the prior year. For context, the drop was less steep than the 8.3% decline recorded during the exact same timeframe last year. Looking deeper into the claims data, repairable estimates fell by 5.4%, while total loss valuations increased by 1.1%, according to the findings compiled by CCC Intelligent Solutions.
Simultaneously, financial pressures on consumers are manifesting clearly in policy choices, particularly regarding deductibles. The report reveals a continuation of a multi-year trend in which a growing share of consumers opt for higher deductibles in exchange for immediate relief on their monthly or semi-annual insurance premiums. The percentage of repairable collision claims carrying deductibles of $1,000 or more reached 28.4% in the first half of the year, up notably from 25.7% a year earlier and sharply higher than the 20.3% recorded in 2022.
The authors of the report point out that this shift in consumer behavior has broad consequences for the entire insurance industry. For individual policyholders, accepting a higher deductible provides immediate premium relief in an otherwise inflationary market. However, for the broader claims ecosystem, it fundamentally alters the economics of filing a claim. A deductible set at $1,000 or higher makes relatively minor vehicular damage much easier for drivers to postpone, self-fund out of pocket, or simply leave unrepaired.
As a result, this behavioral shift effectively removes smaller claims from the insurer-processed population, which in turn raises the apparent severity of the claims that do remain in the system, while exacerbating the overall share of total losses.
This trend toward self-funding minor damage is corroborated by data on independent repair orders. According to the report, self-pay repairs accounted for 26% of all repair orders in the first half of 2026, marking a 0.5 percentage point increase year-over-year. The financial footprint of these self-funded repairs contrasts sharply with insurance-backed claims. The average self-pay repair cost stood at $1,941 during the period, compared with an average of $4,821 for repairable insurance claims. Furthermore, the divide is visible in the distribution of repair sizes: more than 71% of self-pay repair orders were below the $2,000 threshold, whereas roughly 75% of repairable insurance claims exceeded that amount.
For the claims that do enter the insurance system, the cost of repair remains high. The average cost of repair reached $4,821 in the first half of the year, up 0.6% from the same period last year. While this year-over-year increase is relatively subdued, the longer-term perspective highlights a substantial structural shift in repair economics. The average cost of repair has climbed significantly from 2020, when it stood at $3,331. Driving these elevated costs are underlying inflationary pressures on components and shop operations. Average parts prices were found to be 8% higher year-over-year through the first half of 2026, while labor rates continued an upward march, rising 1.5%.
Beyond traditional mechanical components and sheet metal, rapidly evolving vehicle technology continues to exert a profound effect on repair processes, timelines, and costs. Modern automobiles are increasingly equipped with advanced driver-assistance systems and complex digital architecture that require precise diagnostics and recalibrations following a collision.
The data illustrates this technological dependency clearly. Nearly 75% of all repairable appraisals included a diagnostic scan in the first quarter of 2026, representing an increase from 70.9% a year earlier. Furthermore, the share of repair appraisals requiring physical or electronic calibration of vehicle sensors and cameras rose from 23.3% to 29.9% over the same period, adding specialized labor steps and technical requirements to standard collision repair workflows.
Powertrain changes are also steadily altering the composition of repair queues, though internal combustion engines still dominate the market. Hybrid vehicles accounted for 9.9% of repairable claims in the second quarter of the year, while electric vehicles represented a smaller, though closely watched, share at 4.3% of repairable claims.
The findings detailed in the 2026 Crash Course Mid-Year Update are drawn from extensive, aggregated industry data encompassing electronic appraisals, total loss valuations, and detailed claims information processed directly through CCC Intelligent Solutions’ networks.








No comments yet. Be the first to join the conversation!