
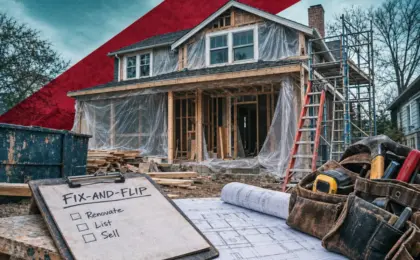
The United States fix-and-flip housing market experienced a notable contraction in momentum during the third quarter, caught in the crosshairs of stubbornly high mortgage rates, declining home values, and mounting labor costs. According to the latest market sentiment survey jointly published by Kiavi and John Burns Research and Consulting, these converging headwinds have severely squeezed profit margins for real estate investors across the country, pushing market sentiment to its lowest point in nearly four years.
The Burns + Kiavi Fix and Flip Market Index fell to a reading of 53 in the third quarter. This represents a significant decline from the 59 recorded in the second quarter and sits below the 56 points registered during the same period a year earlier. The index, which tracks broader conditions within the renovation and resale sector on a scale from 0 to 100, now hovers perilously close to the threshold that defines an outright market contraction.
Within this index framework, any reading below 50 signals market contraction, while figures above 50 indicate expansion. The third-quarter report, based on a proprietary quarterly survey of approximately 280 active fix-and-flip investors, highlights a growing sense of caution across the industry as macroeconomic pressures complicate traditional investment strategies.
Higher Rates, Lower Prices, and Shrinking Optimism
The impact of prolonged high interest rates—which have kept mortgage rates hovering above the 7% mark—has visibly dampened buyer demand at the retail level, leaving property flippers with diminished pricing power and longer holding periods. Sentiment regarding future sales has plummeted accordingly. Only 23% of surveyed investors expect good sales performance over the subsequent six-month period, marking the smallest share of optimistic flippers recorded by the survey in four years. Conversely, 19% of respondents anticipate poor sales conditions ahead, representing the highest share of pessimism captured by the metric since the final quarter of 2022.
This broad slowdown is sparing virtually no corner of the market, affecting large and small operators alike. Interestingly, large-scale flippers—categorized as those who have either purchased or sold at least eight residential properties over the preceding 18 months—reported worse market conditions than their smaller counterparts for the first time since the third quarter of 2022, signaling that heavy capital exposure is becoming an increasing liability in a cooling environment.
The cooling demand environment has directly impaired the pricing leverage historically enjoyed by property renovators. Fully 40% of participating flippers reported that home sale prices in their specific local markets were lower than they were one year prior. By contrast, only 16% of investors observed higher sale prices, while the remaining 36% noted that prices had remained largely flat or unchanged.
Geographic disparities reveal where the correction has hit hardest, with the American Southwest leading the way in price reductions. In that region, 67% of flippers reported experiencing lower selling prices. Southern California followed closely behind, with 50% of investors noting downward price adjustments. Meanwhile, in the dynamic markets of Texas and the broader Southeast, 47% of respondents observed lower prices, and 44% of Florida-based investors reported similar downward trends.
These localized price corrections have translated into tangible valuation shortfalls upon exit. Approximately one in five flippers indicated that they were ultimately forced to sell renovated homes at prices mostly below their initial after-repair value (ARV) estimates. This metric is now rapidly approaching the highest level recorded by the survey since tracking began in 2021, illustrating the difficulty of accurately forecasting property values in a shifting real estate cycle.
Labor Constraints and Immigration Enforcement
Beyond financing costs and softening sales prices, residential real estate investors are confronting escalating operational headwinds on the ground, particularly concerning renovation labor. The survey revealed that increased immigration enforcement is creating tangible disruptions in the availability and cost of construction labor.
Forty-one percent of surveyed flippers reported that heightened immigration enforcement has had a negative impact on their labor force. This represents a sharp increase from the 33% who voiced similar concerns when the same question was posed in the second quarter of 2025.
Investors reported widespread difficulties in recruiting qualified tradespeople, which in turn drove up wage pressures and extended project completion timelines. While these labor constraints were felt nationally, the disruption was cited as particularly acute in Florida and the Southeast, though operational friction was also reported across various other regional markets.
Inventory as a Reluctant Tailwind
Amid these mounting economic and operational challenges, rising housing inventory has provided a minor silver lining, offering investors expanded acquisition opportunities even as market participation grows more complex.
The availability of inventory has altered competitive dynamics in the acquisition space. Twenty-four percent of flippers reported that competition for prospective deals was lower than usual during the third quarter, marking the highest share of reduced competition recorded in the history of the survey.
However, despite this influx of available properties and a relative easing of bidding wars, investors are maintaining strict financial discipline regarding acquisition pricing. The average surveyed flipper targeted a maximum purchase price equivalent to 67% of a property’s projected after-repair value, representing a slight downward adjustment compared to the previous quarter as buyers seek to protect their margins against unforeseen market corrections.
Renovation expenses continued to display significant regional variance across the country. The national average cost to completely renovate a flipped home stood at $72,000 during the third quarter. Regional cost pressures varied dramatically, with renovation expenditures soaring to an average of $133,000 in Southern California and reaching $86,000 in the Northeast. Conversely, renovation costs were substantially lower in the Southeast and Texas, averaging $47,000 and $46,000 per project, respectively.
Strategic Recommendations for Investors and Lenders
The cumulative findings of the third-quarter index point to sustained pressure on real estate investors. The combination of elevated financing costs, subdued retail buyer demand, and persistent labor constraints has fundamentally complicated the financial modeling and project economics of residential flipping.
In light of these persistent headwinds, John Burns Research and Consulting advised that fix-and-flip operators maintain strict financial discipline when acquiring new properties. The firm emphasized the importance of building robust safety margins into underwriting models to properly account for potential further price declines and elevated labor expenses.
Furthermore, financial institutions and private lenders active in the sector were advised to adjust their underwriting practices. John Burns recommended that lenders evaluate properties based on projected future sale prices expected at the time of ultimate asset disposition, rather than relying exclusively on recently closed comparable sales data, which can lag significantly behind market reality in a downward-trending housing cycle.
No comments yet. Be the first to join the conversation!