
The history of property taxation traces its roots back centuries, originating in feudal times when assessments were levied primarily on agricultural land and paid mostly by farmers who worked the soil. Over generations, this ancient fiscal instrument evolved into a cornerstone of modern public finance. Today, property taxes are routinely levied on a broad spectrum of assets, most notably real estate, and are paid on a recurrent basis by individuals, corporations, and other legal entities. While these levies remain a vital tool for governments worldwide, a recent examination of international tax policies reveals stark contrasts in how different nations approach the taxation of property, highlighting significant implications for economic growth, investment, and business location decisions.
From an economic standpoint, property taxes can serve a dual purpose. Ideally, they provide local governments with a reliable and valuable fiscal incentive to permit new development, offering a sustainable mechanism to fund local public services—such as schools, infrastructure, and emergency services—whose value is ultimately capitalized into surrounding property prices. However, the structure of these taxes matters immensely. High property taxes levied not only on land but also on physical buildings and permanent structures can actively discourage investment in those assets. When businesses face additional tax burdens on commercial facilities, warehouses, and offices, the cost of expansion rises. Consequently, businesses may strategically choose to locate away from jurisdictions with punitive property tax regimes, seeking more hospitable environments for their capital.
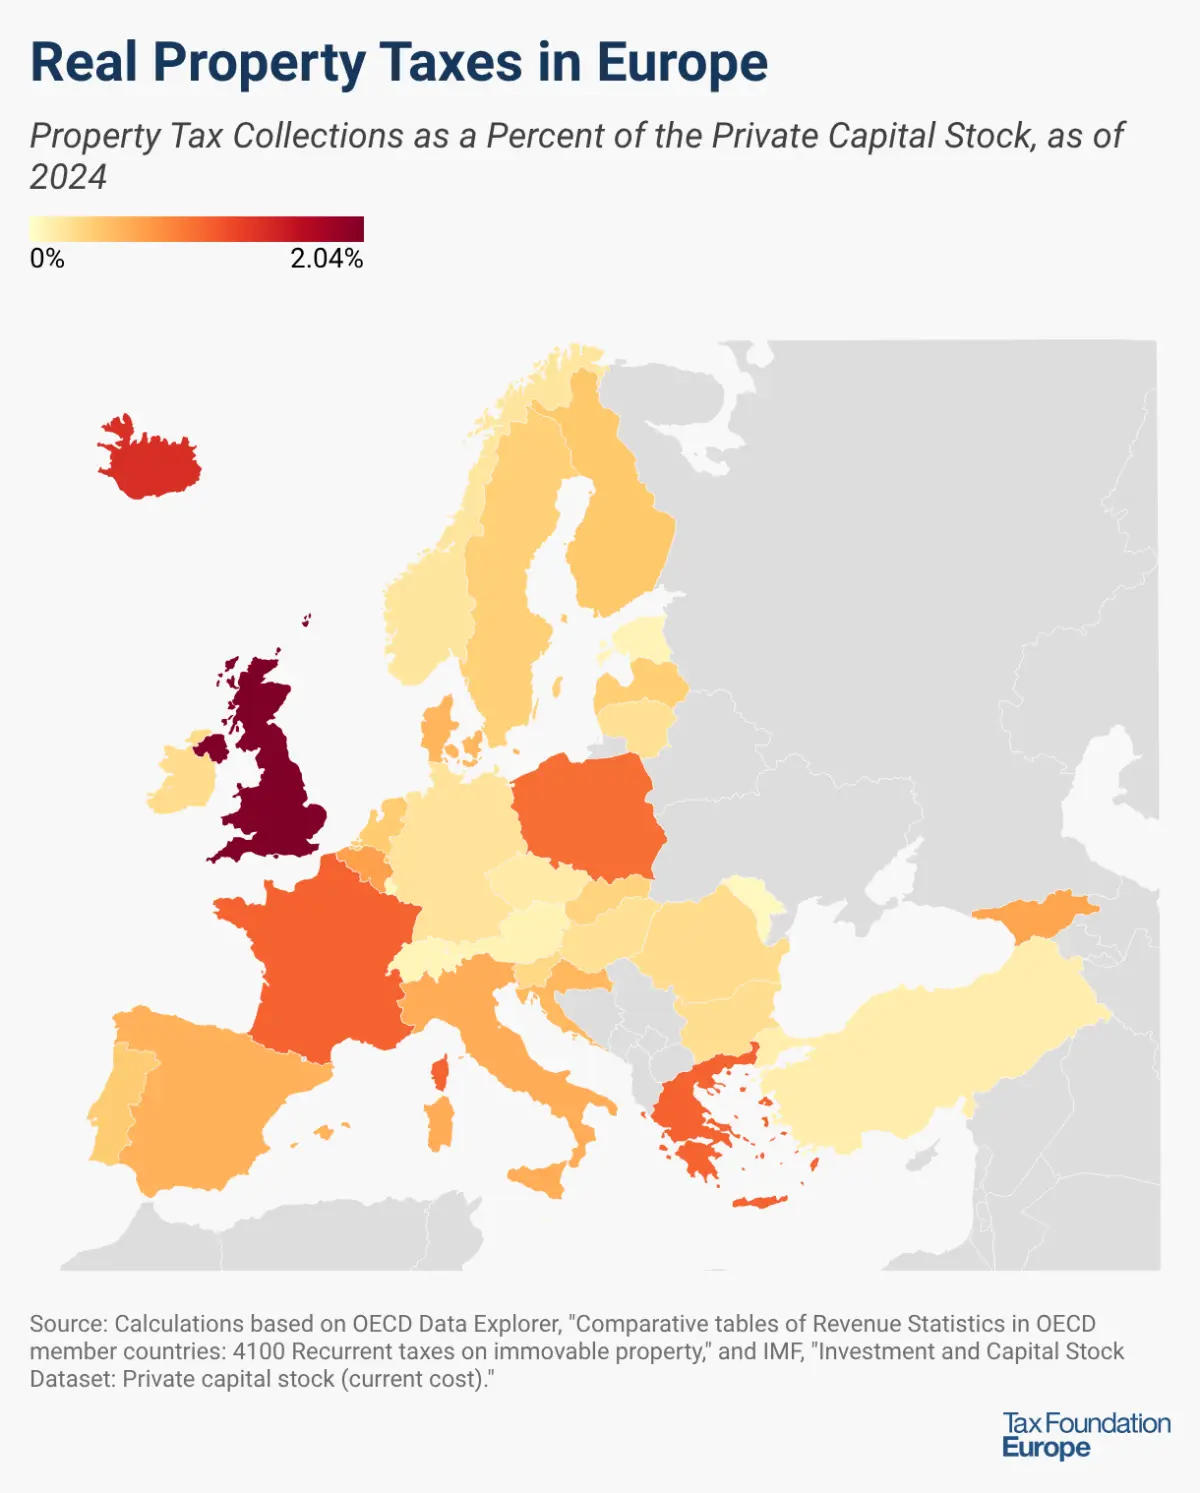
International comparisons underscore just how varied these tax philosophies are across the globe. Among 34 European countries analyzed in recent comparative tax data, two nations—Liechtenstein and Malta—stand out for not levying any recurrent taxes on property at all. Meanwhile, Estonia takes a unique approach as the sole country on the map to tax exclusively land rather than the structures built upon it. By exempting buildings from recurrent taxation, Estonia ensures that its real property tax framework operates with maximum economic efficiency, removing disincentives for structural improvements and real estate development.
The mechanics of how countries treat property taxes within corporate tax systems further influence business investment decisions. Of the 32 European countries that do levy recurrent property taxes, the vast majority—28 nations—allow businesses to deduct their property or land taxes from their corporate income. This policy effectively mitigates the overall tax burden and encourages ongoing commercial investment. However, a minority of four countries—Austria, Iceland, Italy, and Slovenia—prohibit the deduction of property taxes from business income. This restriction results in the double taxation of business properties, requiring firms to pay taxes twice on the same underlying stream of income, whether evaluated at the corporate or individual level.
Disparities are equally pronounced when examining property tax revenues as a share of private capital stock. Luxembourg and Moldova raise the lowest property tax revenues relative to their private capital stock, hovering at around 0.05 percent. Switzerland and Estonia follow closely behind at 0.08 and 0.09 percent, respectively. At the opposite end of the spectrum, the highest property taxes as a share of private capital stock are found in the United Kingdom at 2.04 percent, followed by Iceland at 1.43 percent and France at 1.08 percent.
Across the 32 European countries that maintain a recurrent property tax, the average revenue raised sits at 0.45 percent of their private capital stocks. To contextualize these figures against other major Western economies, the United States relies far more heavily on property taxation as a primary revenue source. The U.S. raises an estimated 1.88 percent of its private capital stock in property taxes, making it the single largest source of state and local revenue across the Atlantic, helping to fund essential public goods and community services.
Furthermore, looking at the distribution of the tax burden between households and businesses across 16 European countries that track these metrics reveals that households shoulder the lion’s share. On average, households remit approximately 60 percent of total property tax revenue. However, individual nations vary wildly: households account for a mere 7.4 percent of receipts in the Slovak Republic, compared to a staggering 71.4 percent in France, illustrating vastly different domestic policy priorities regarding who bears the cost of local governance.
Recent Changes
As fiscal policies continue to evolve, several nations are implementing notable reforms to their property tax structures. Beginning in 2025, Germany has moved to devolve its property tax base to the state level, allowing regional authorities greater autonomy over their fiscal policies. Seizing this opportunity, the German state of Baden-Württemberg restructured its approach to apply property taxes solely to the value of the land, mirroring the economically efficient model long championed by reformers. Meanwhile, Croatia expanded its fiscal toolkit by introducing a brand-new recurrent property tax in 2025, designed to be levied systematically based on the physical dimensions of land and floor area.








No comments yet. Be the first to join the conversation!