
For years, comprehensive polling data from KFF has consistently highlighted the heavy financial burden that high health care costs place on families across the United States. These expenses are not merely line items in household budgets; they actively factor into critical decisions regarding insurance coverage, routine care-seeking, and long-term financial planning. As health care expenses continue to outpace many household incomes, they rank as the foremost financial anxiety for adults and their families, overshadowing numerous other economic concerns.
This sustained public pressure forms a central backdrop for policy discussions and political engagement. Recent KFF polling data captures the public’s ongoing struggles, anxieties, and difficult compromises when attempting to navigate the American health care system.
Worries and Difficulty Affording Medical Costs
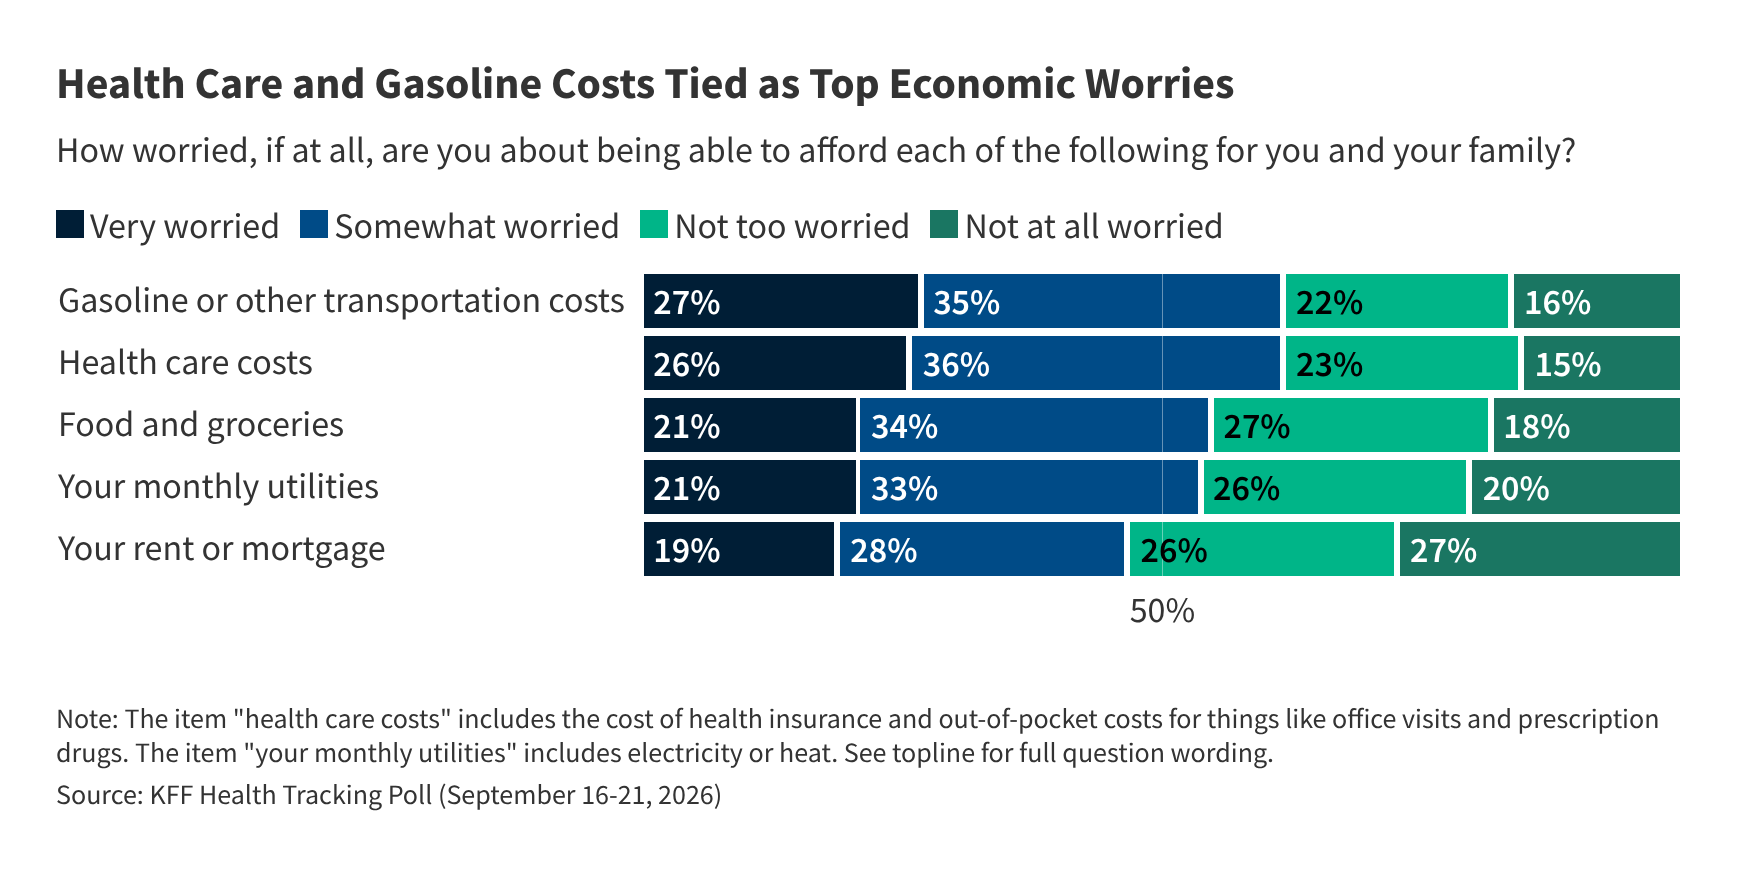
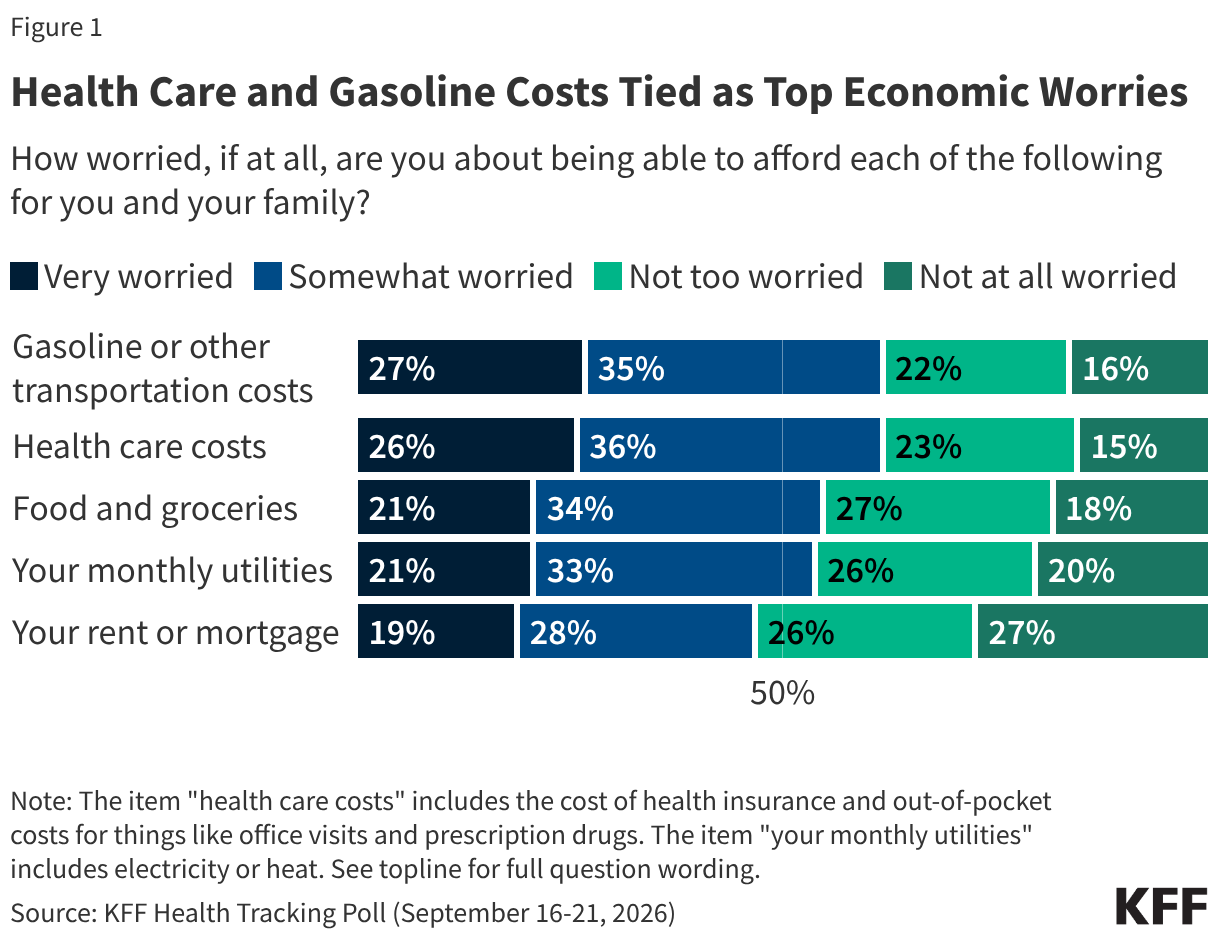
Throughout much of 2026, health care costs have remained securely at or near the absolute top of the list of financial worries for the American public. In the critical period leading up to the 2026 midterm elections, approximately six in ten adults reported being either very worried or somewhat worried about affording health care costs for themselves and their immediate families. This broad category of concern encompasses everything from monthly health insurance premiums to out-of-pocket expenses required for routine physician office visits and vital prescription drugs.
To put this level of anxiety into perspective, a comparable share of adults—about 27%—reported being very worried about affording gas and transportation costs. Meanwhile, everyday household expenses ranked slightly lower in terms of acute anxiety: roughly one in five adults expressed being very worried about affording monthly utilities, food and groceries, or keeping up with their rent or mortgage payments.
The weight of these financial worries is distributed unevenly across different demographics, yet it touches nearly every corner of society. Among uninsured adults under the age of 65, approximately eight in ten reported feeling very or somewhat worried about affording the cost of health care. However, having insurance is far from a complete shield against anxiety; a commanding 63% of insured adults under age 65 shared these same fears. Ultimately, health care costs persist as a dominant household worry regardless of an individual’s specific insurance type or political affiliation.
Echoing these pervasive worries, a significant portion of U.S. adults find medical expenses genuinely difficult to afford. While lower-income and uninsured individuals bear the brunt of this financial pressure, those with steady health insurance coverage and higher household incomes are far from immune. Just under half of all U.S. adults reported that it is very difficult or somewhat difficult to manage their health care costs.
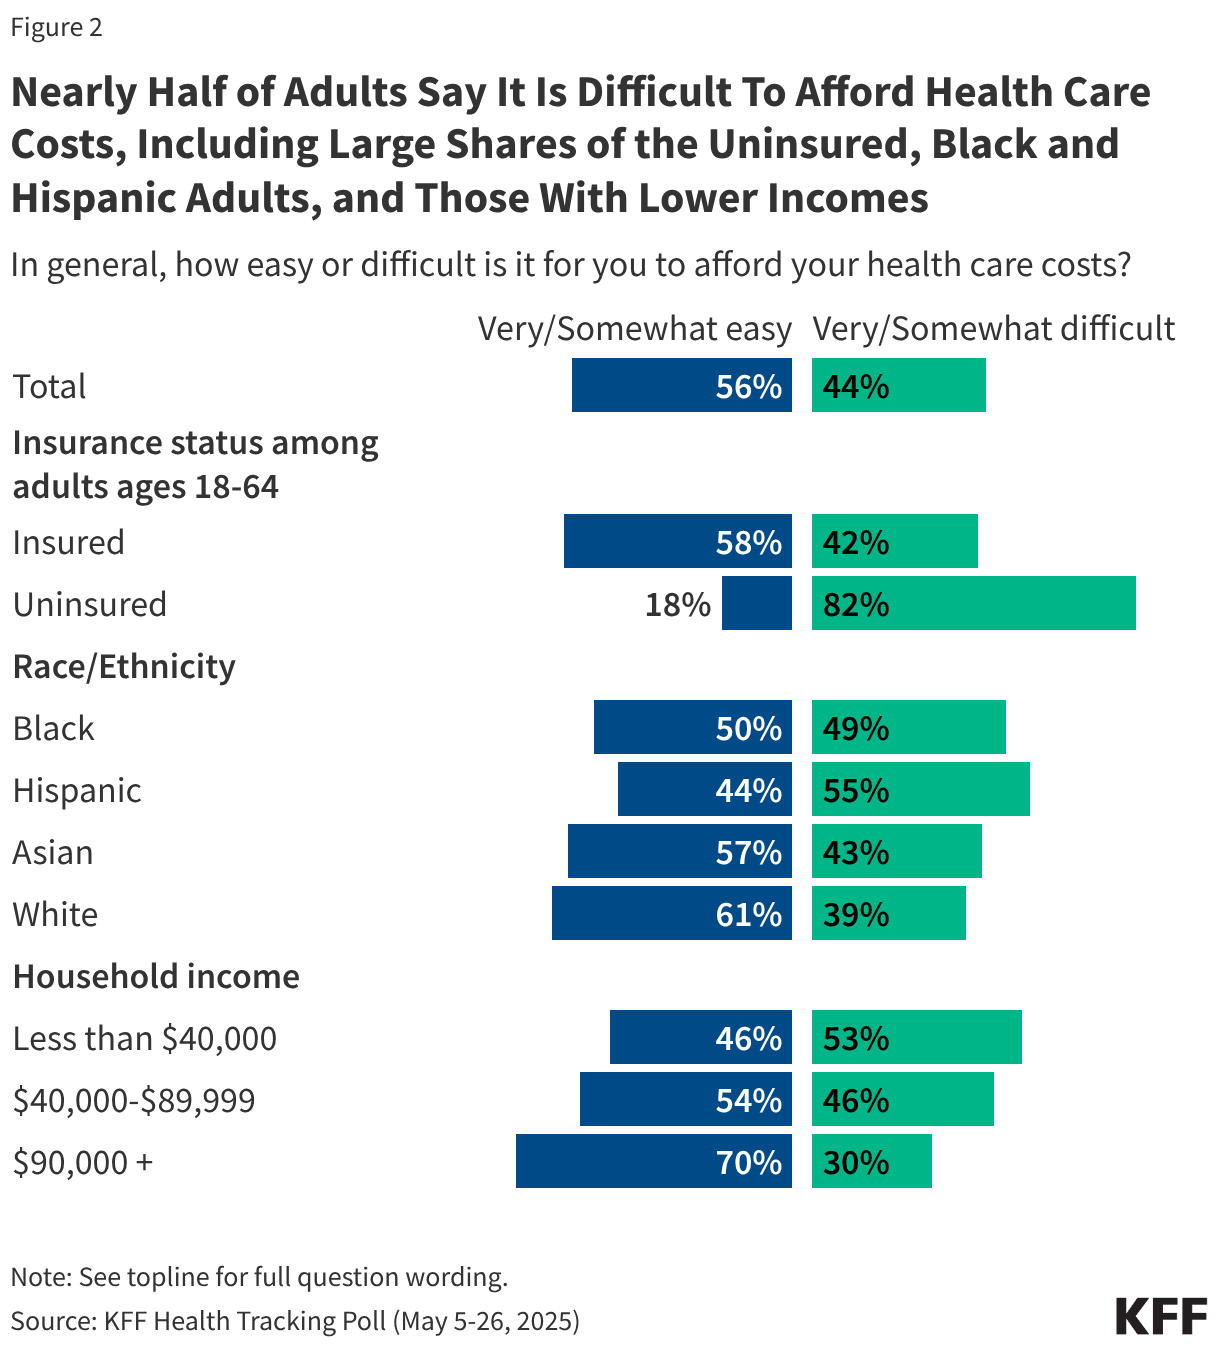
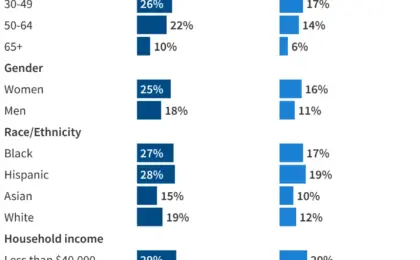
The disparities become even clearer when examining specific populations. Uninsured adults under 65 are vastly more likely to report acute affordability challenges, with 82% describing costs as difficult, compared to 42% of those with health insurance coverage. Racial and ethnic disparities also emerge clearly from the data: a slight majority of Hispanic adults and half of Black adults reported difficulty affording health care costs, compared to roughly four in ten White adults. Furthermore, households with annual incomes under $40,000 face these hurdles at rates significantly higher than their higher-income counterparts.
Skipping Care and Financial Sacrifices
The relentless climb of medical expenses routinely forces individuals to make difficult choices regarding their physical well-being. Chief among these compromises is the decision to forego or delay necessary medical attention. Roughly three in ten adults reported that they had skipped or postponed getting needed health care within the past 12 months simply because they could not comfortably afford it.
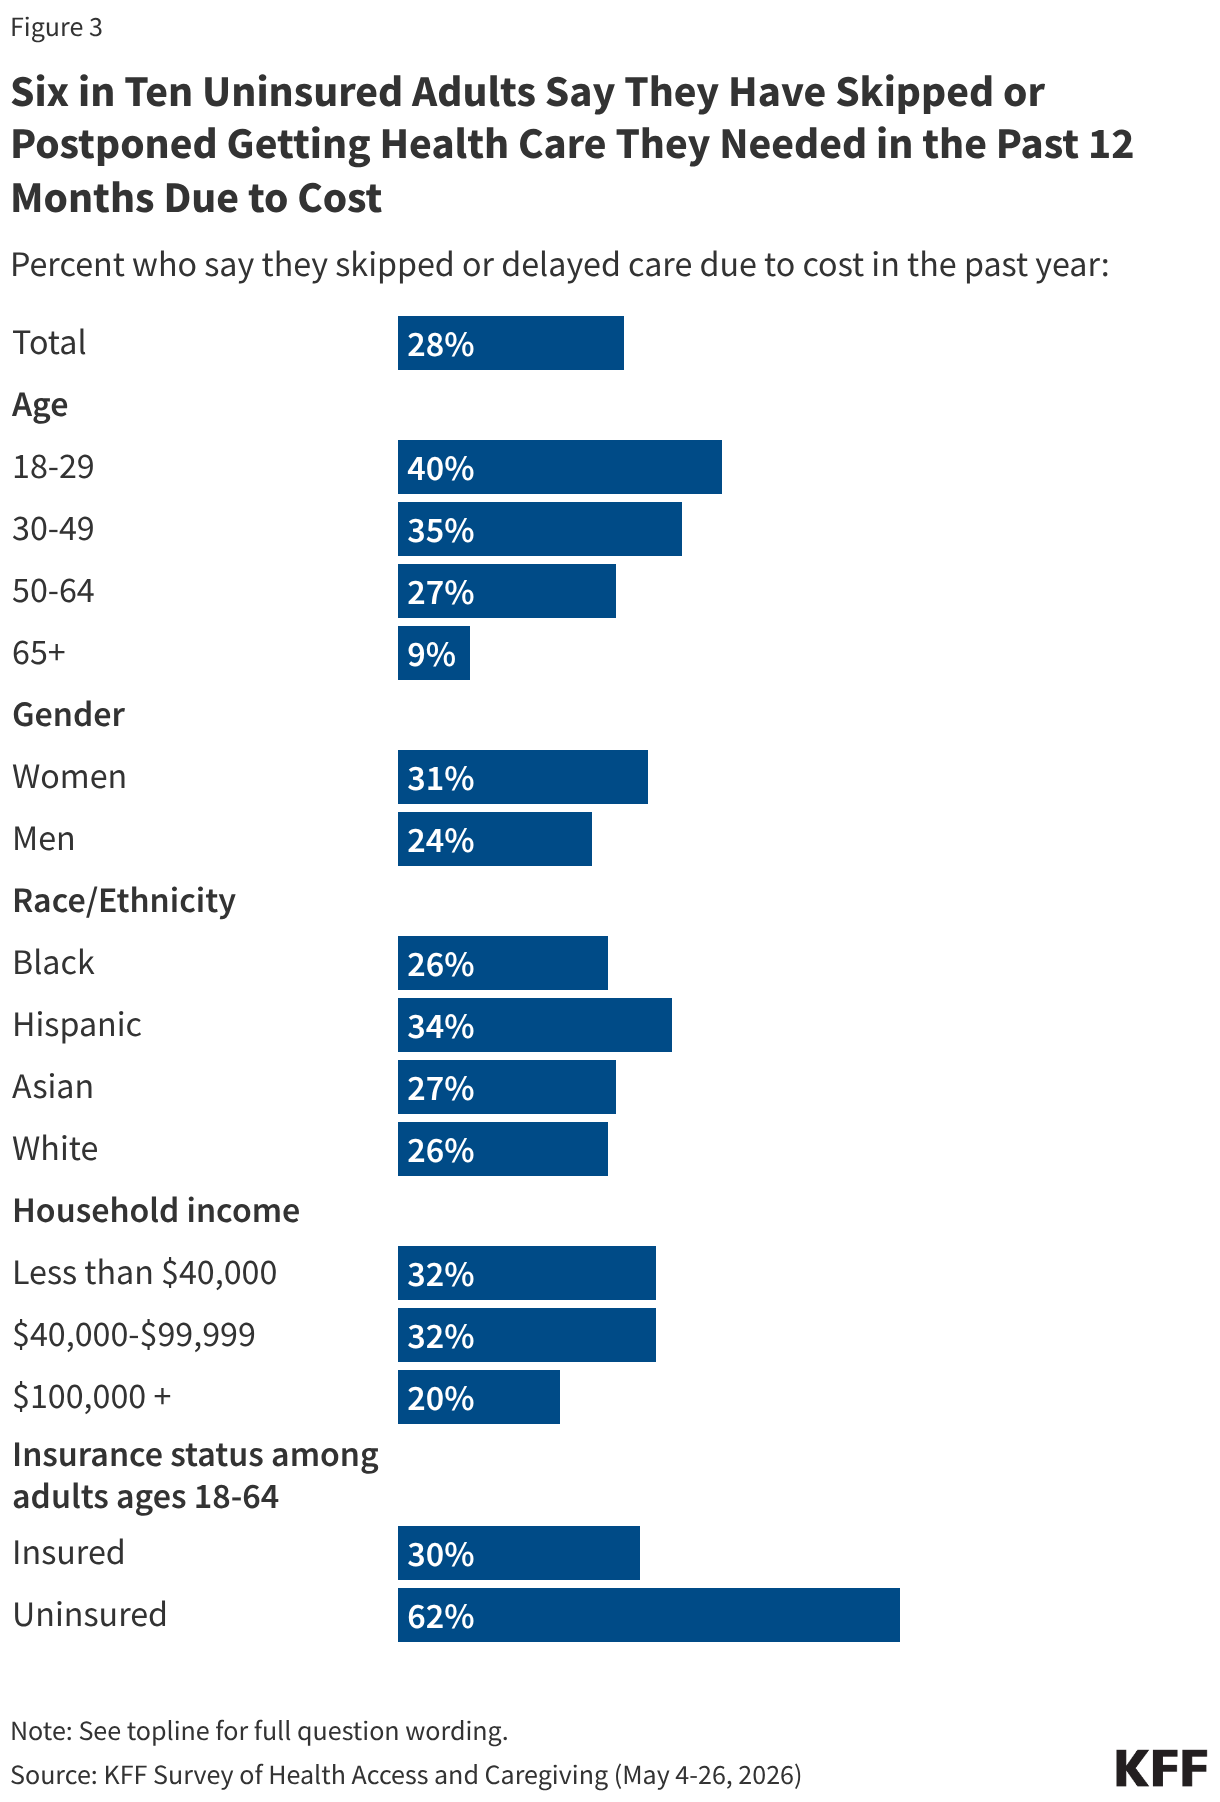
This behavior is particularly prevalent among specific demographic groups. Women, younger adults, Hispanic individuals, and lower-income households are consistently more likely than others to report deferring care due to cost. The situation is starkest among the uninsured, where roughly six in ten individuals report skipping needed medical services. Yet, holding insurance does not guarantee full protection against these trade-offs; three in ten insured adults aged 18 to 64 still reported bypassing necessary care because of out-of-pocket financial barriers.
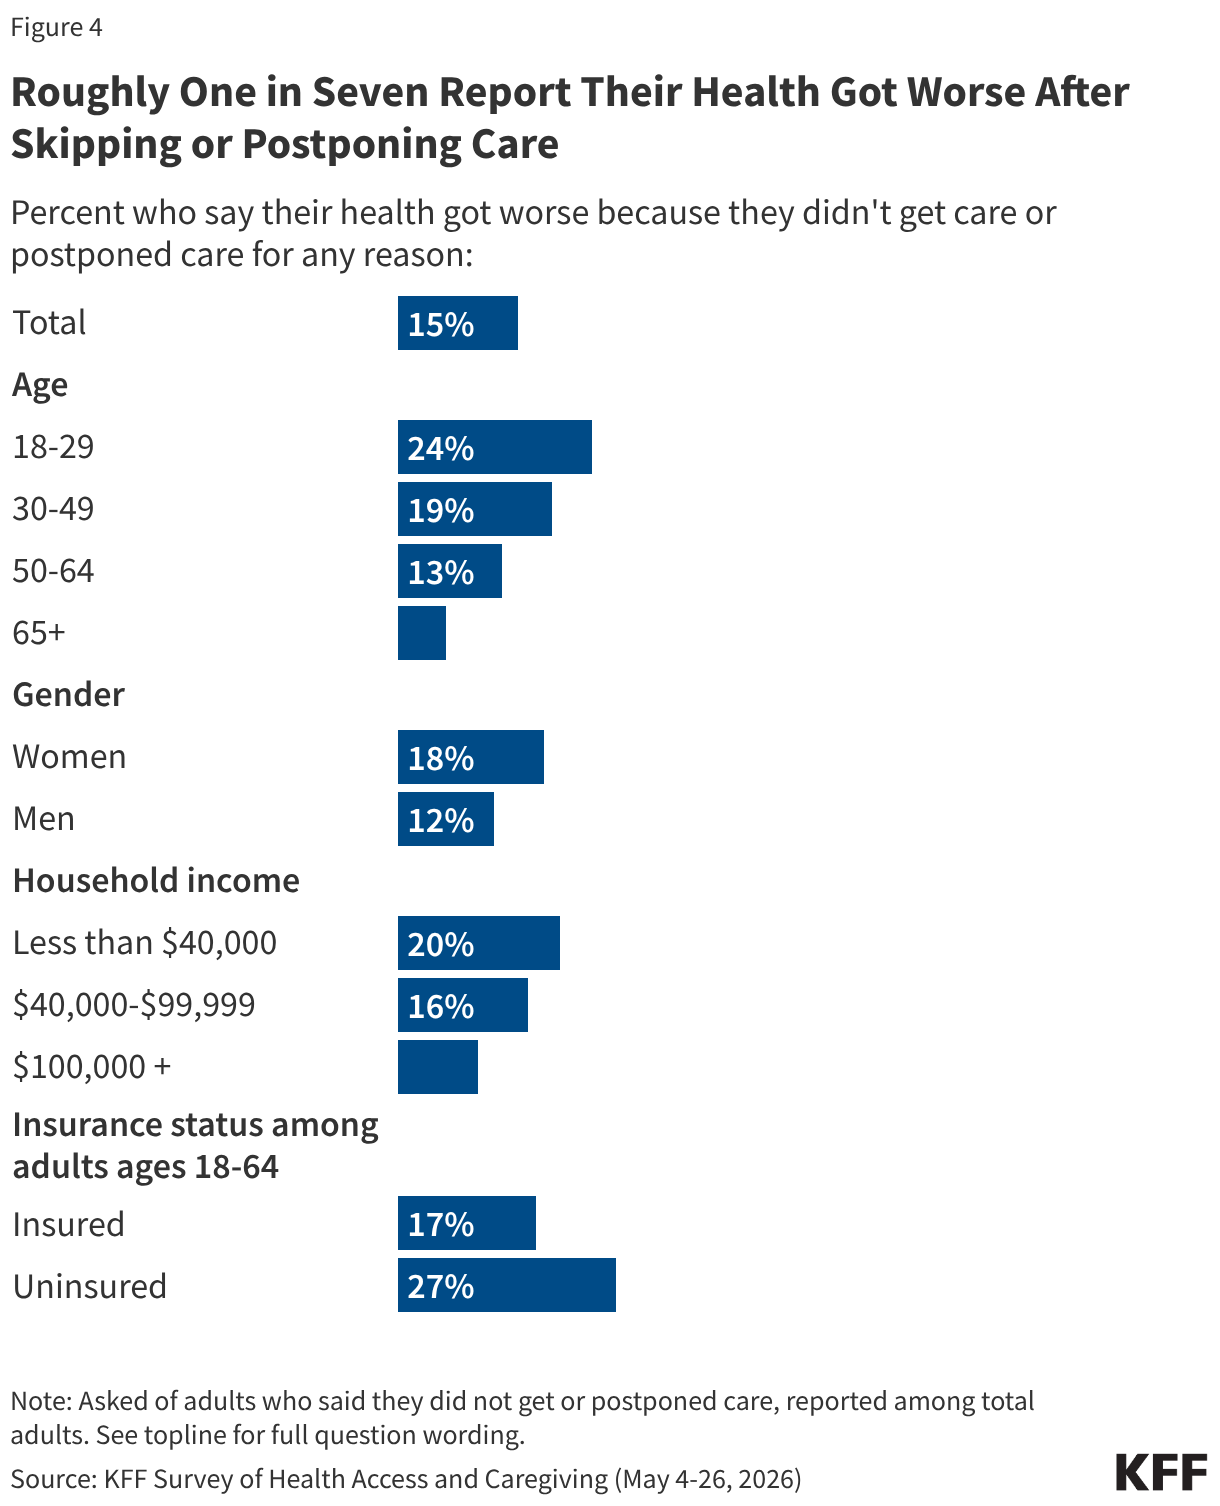
Postponing or avoiding medical treatment rarely comes without consequences. Approximately one in seven adults reported that their overall health deteriorated specifically because they skipped or delayed care for any reason. Among adults under 65, the uninsured are significantly more vulnerable to subsequent health declines than those with coverage. Furthermore, younger generations feel this impact acutely; adults under the age of 30 were four times as likely as adults aged 65 and older—most of whom benefit from Medicare—to report that their health worsened after skipping or postponing medical attention.
Problems Paying Medical Bills
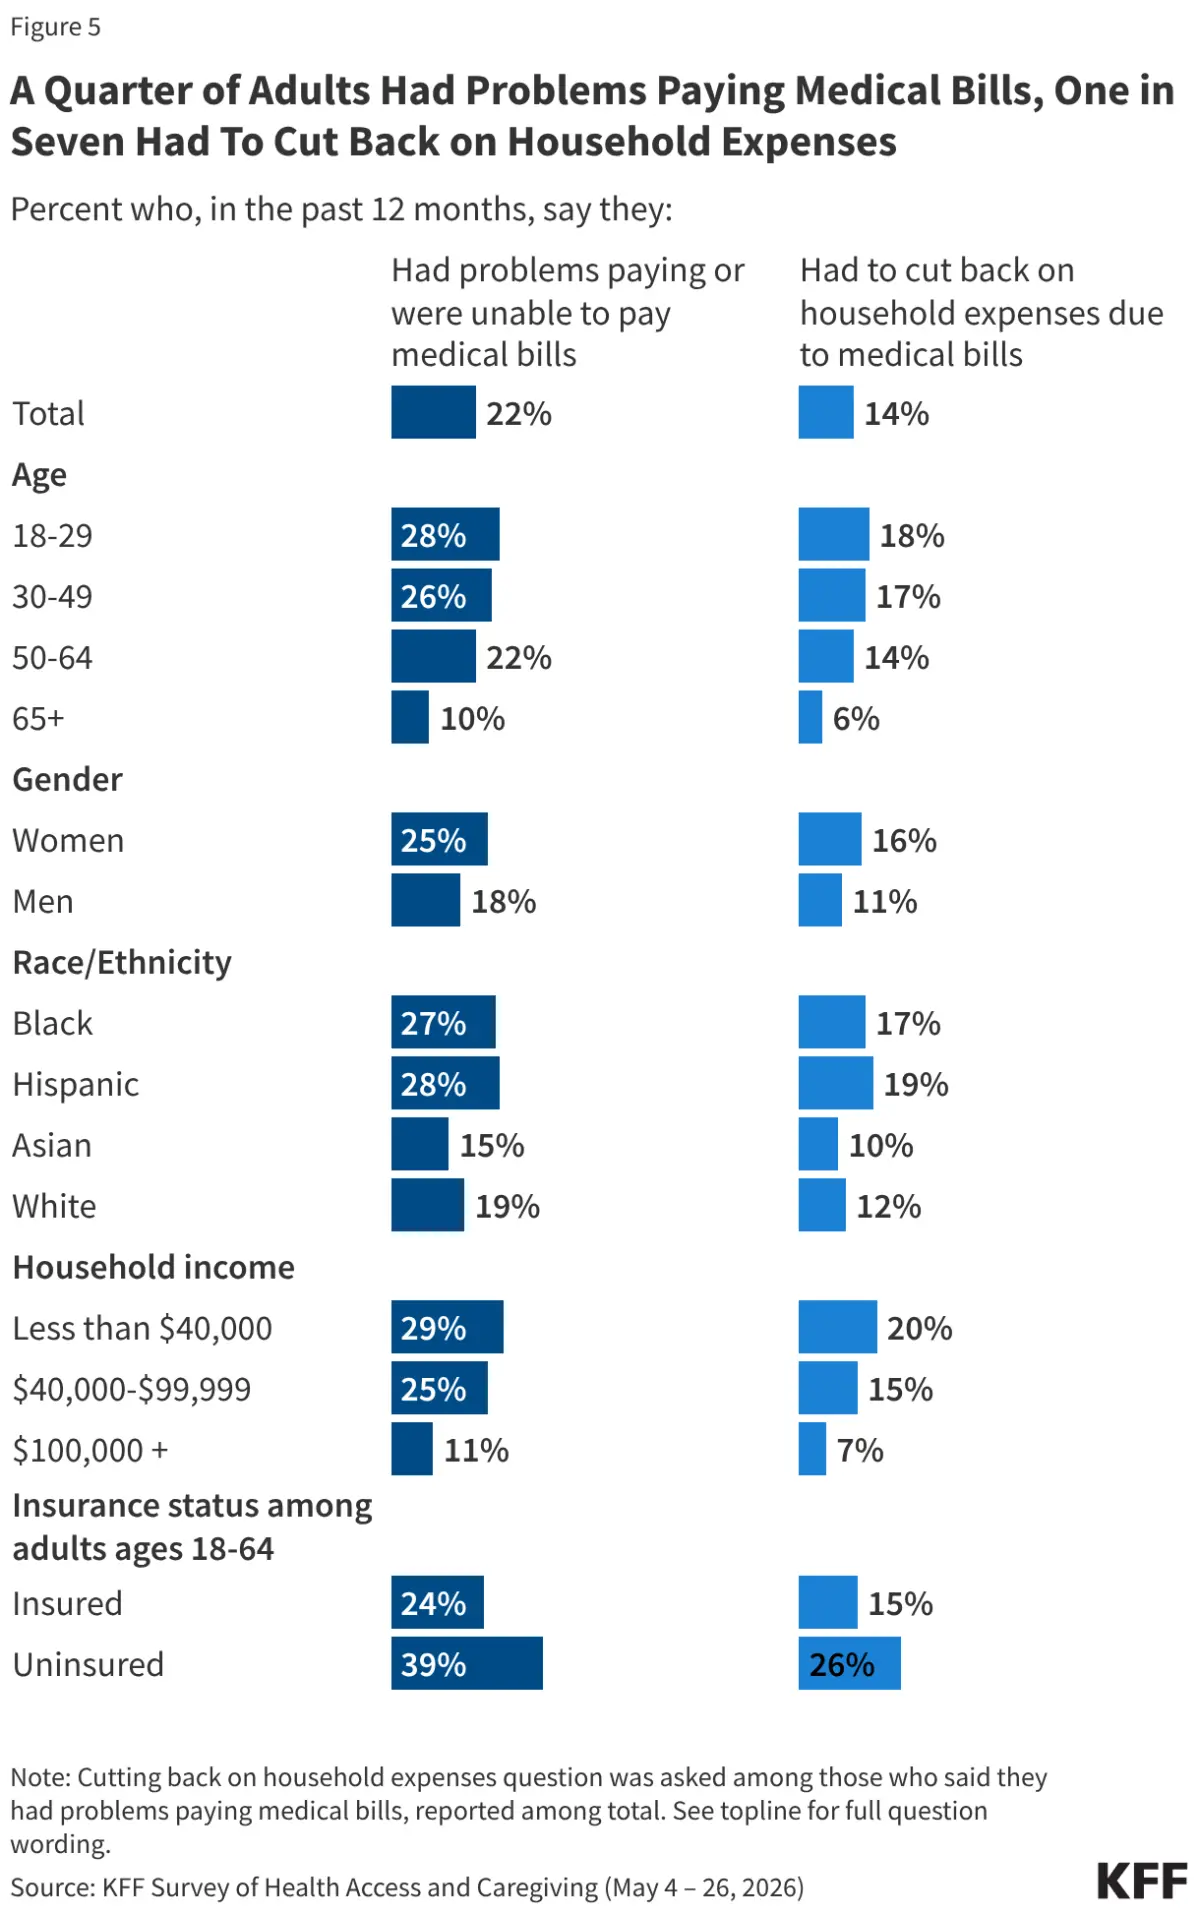
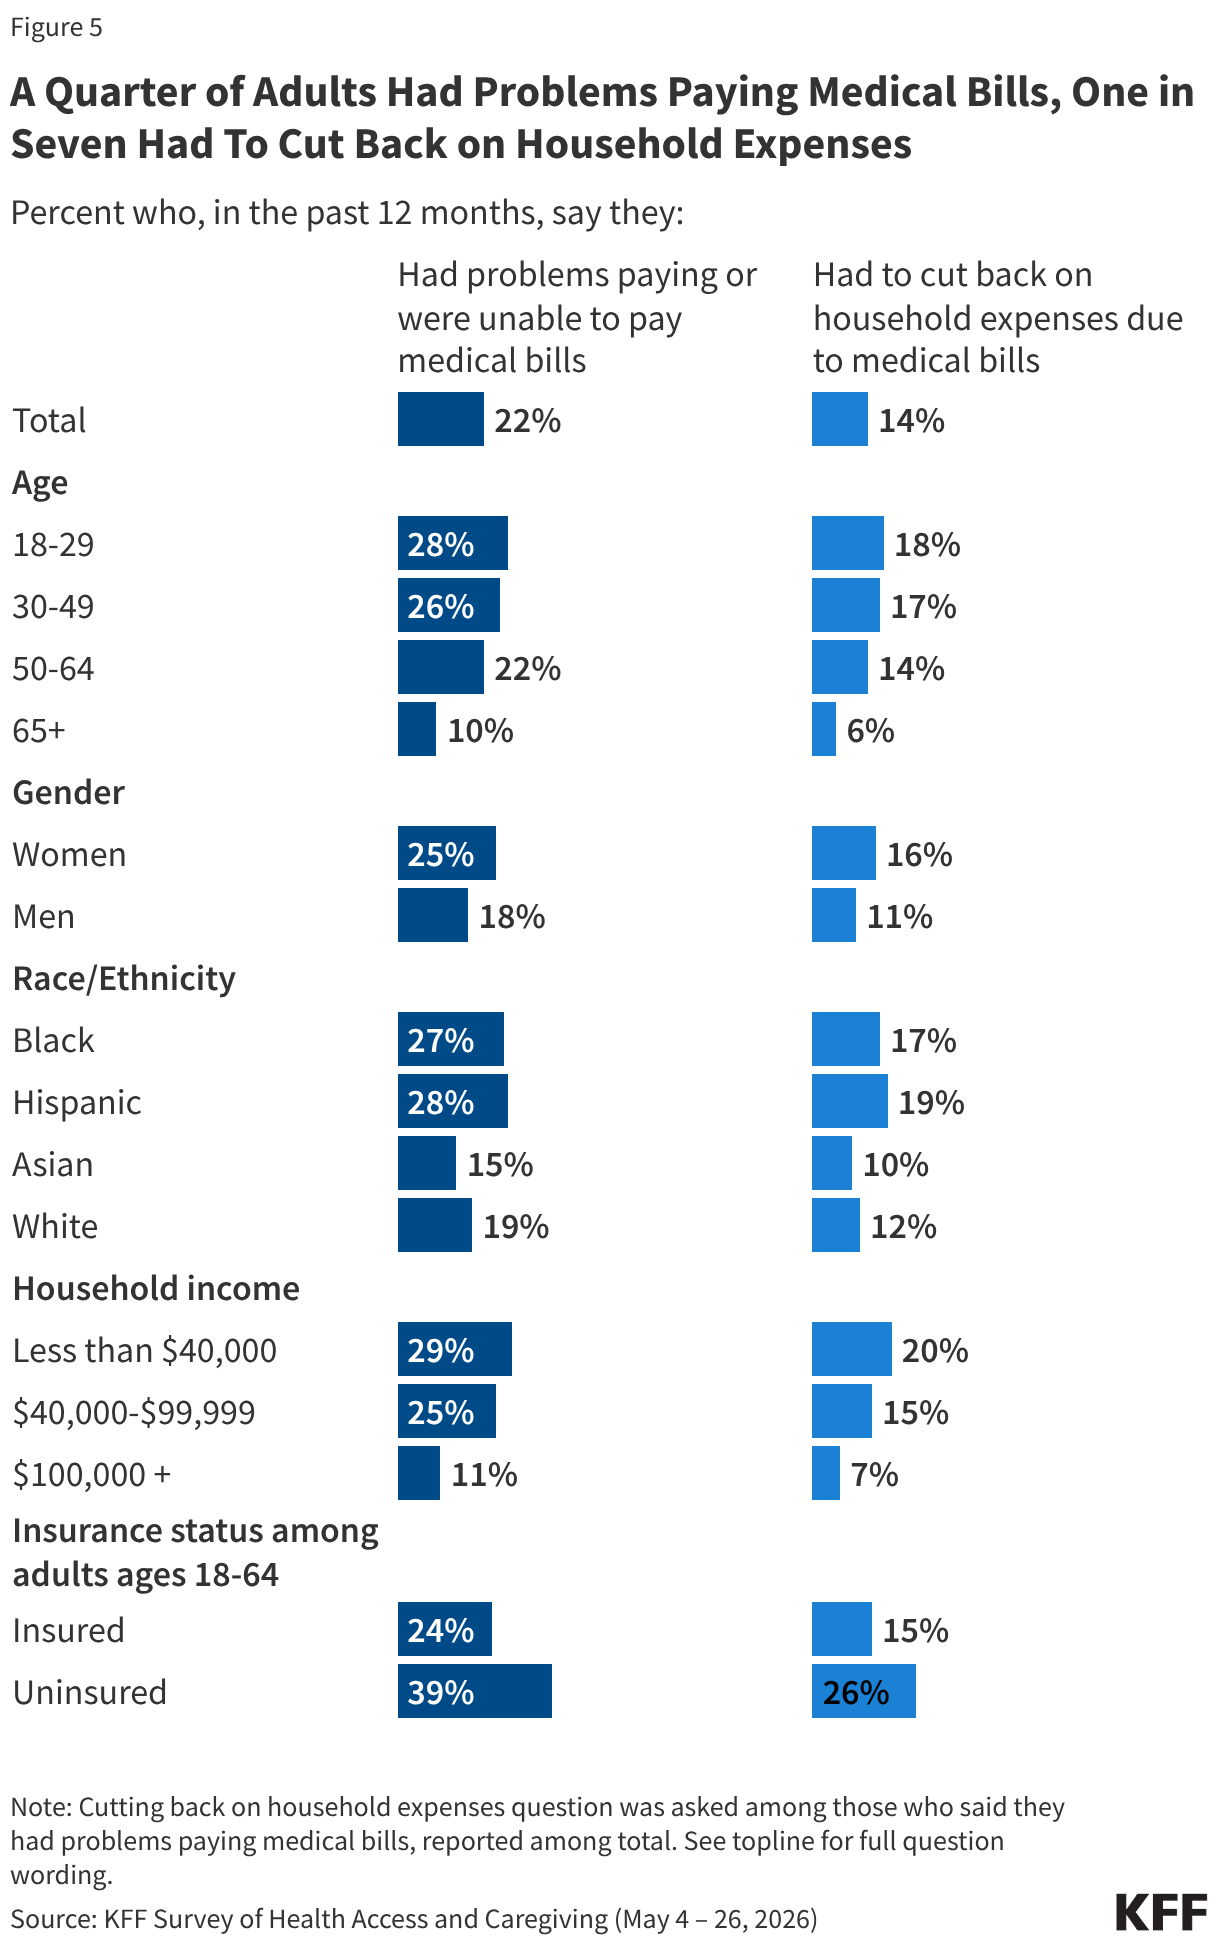
Beyond the immediate anxiety of accessing care, direct medical debt and bill collection pose immense challenges. About one in five adults overall reported experiencing problems paying, or an outright inability to pay, medical bills over the previous 12 months. These troubles encompass bills originating from doctor consultations, laboratory tests, diagnostic imaging, and pharmaceutical prescriptions. Once again, younger adults, women, Hispanic and Black adults, lower-income earners, and uninsured individuals under 65 reported these financial strains at disproportionately higher rates.
The fallout from unpaid medical bills extends deep into daily life. One in seven adults stated they had to make painful cutbacks on essential household expenses—such as food, clothing, and basic necessities—just to manage their health care costs. Naturally, this survival tactic is most common among economically vulnerable populations, appearing in one-fifth of households earning under $40,000 annually and in over a quarter of uninsured adults under 65.
Challenges Among LGBTQ+ Adults and Vulnerable Populations
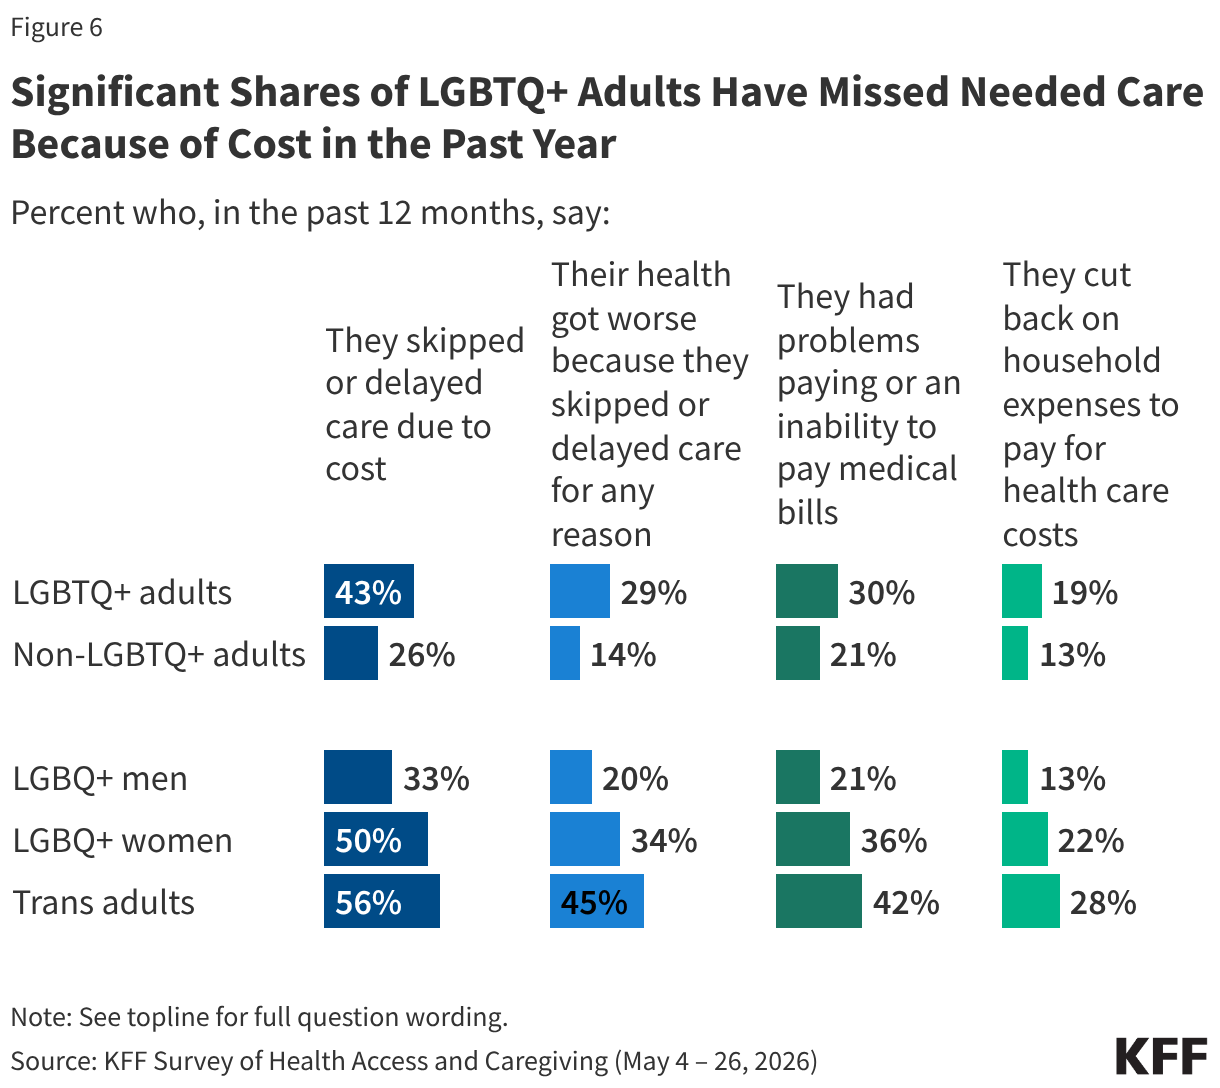
Certain communities experience compounded challenges when navigating the financial landscape of the U.S. health care system. LGBTQ+ adults, who on average skew younger and report lower median incomes than their non-LGBTQ+ peers, face exceptionally high hurdles. According to KFF findings, more than four in ten LGBTQ+ adults reported skipping or delaying care due to cost within the past year, compared to roughly a quarter of non-LGBTQ+ adults.
Additionally, about three in ten LGBTQ+ adults encountered problems paying medical bills, with nearly two in ten forced to cut back on basic household expenses to stay afloat. Transgender adults face even steeper obstacles; over half reported delaying care due to cost, and nearly half stated that their health deteriorated as a result of skipped or delayed treatment.
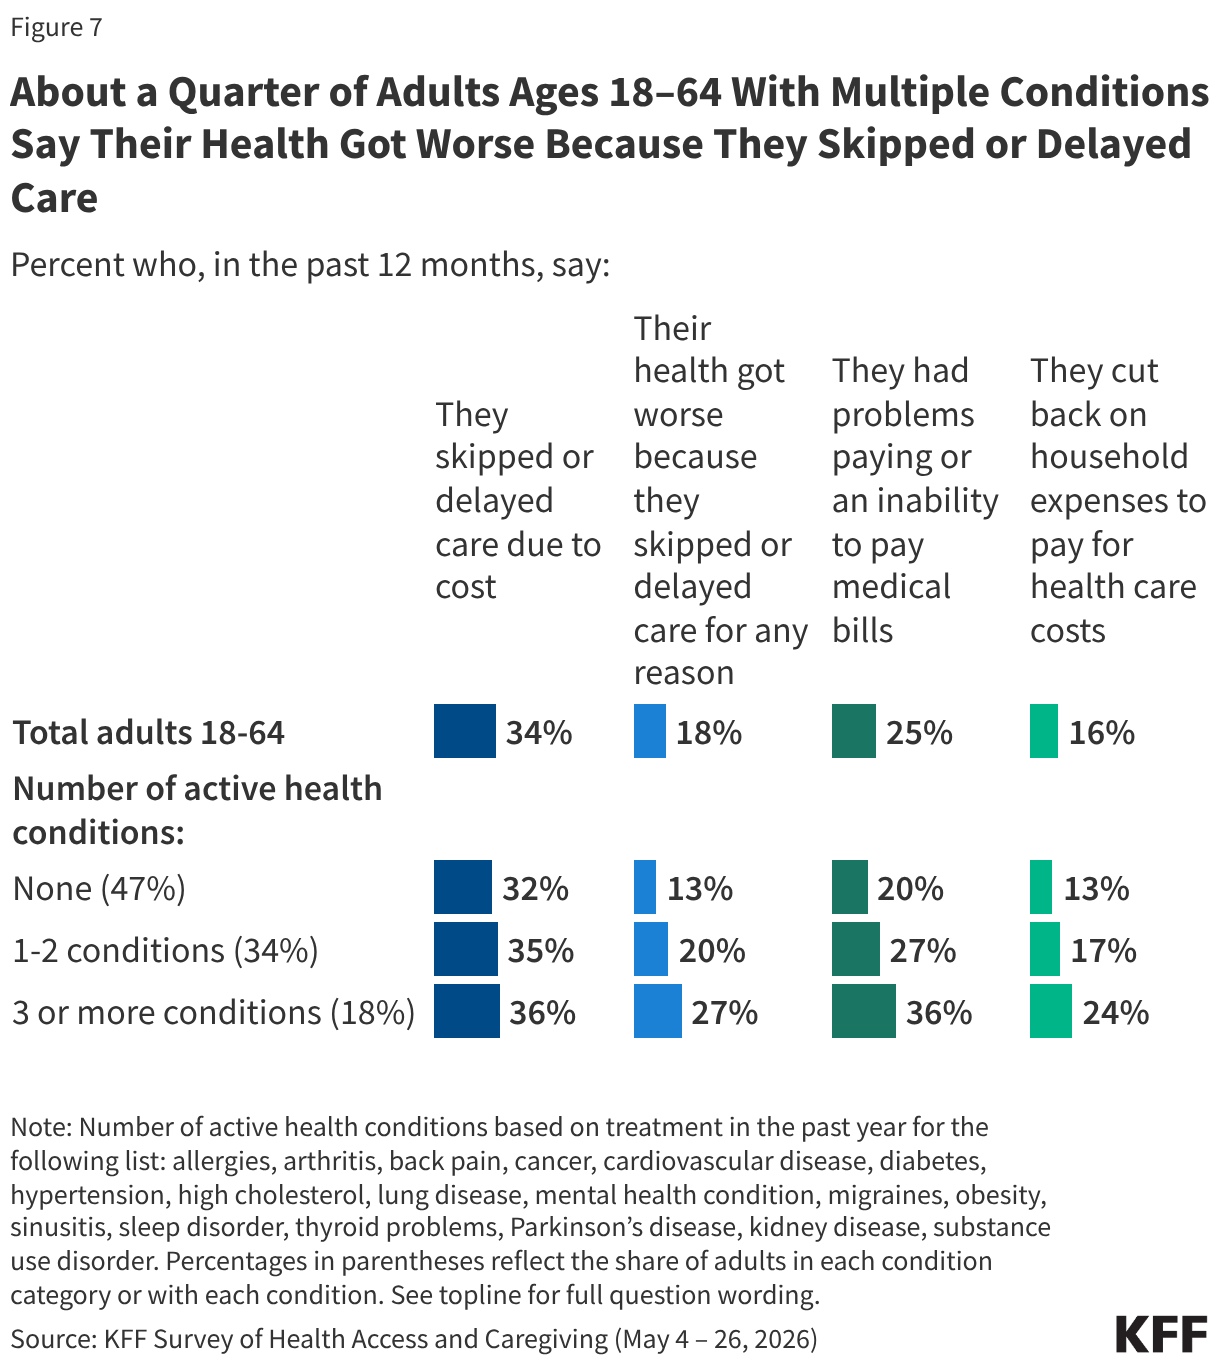
A similar pattern of disproportionate burden falls upon individuals managing multiple or complex chronic health conditions. Roughly one-third of adults aged 18 to 64 with three or more active health conditions reported failing to get necessary care due to cost over the past year. Furthermore, 27% of these complex-care patients stated their health worsened because they delayed or skipped treatment. Beyond physical health tolls, over a third of working-age adults with three or more conditions faced problems paying medical bills, and nearly a quarter had to curtail basic household spending to cover medical expenses.
Prescription Drug Costs and Coping Mechanisms
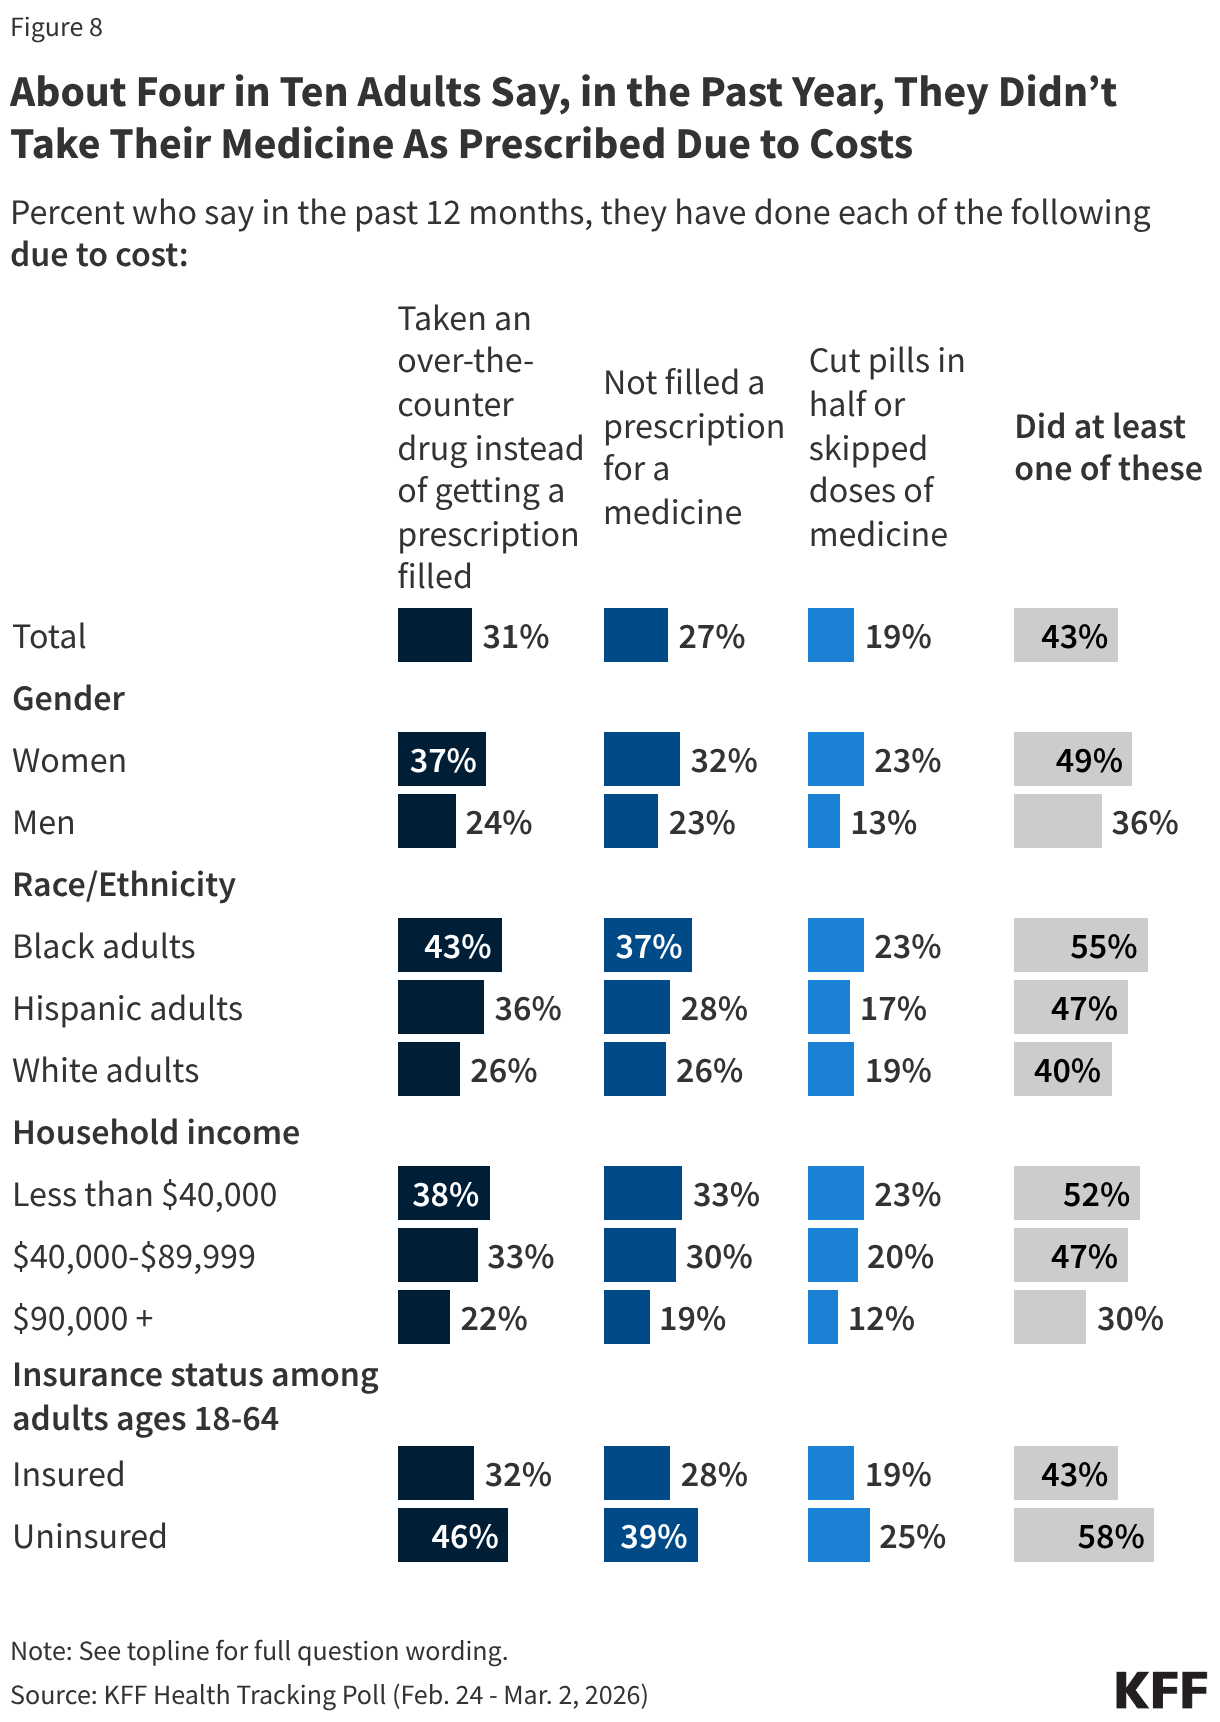
The escalating price of prescription medications has driven many patients to adopt risky behaviors to ration their treatments. About three in ten adults reported taking an over-the-counter medication instead of filling a prescribed drug due to cost concerns. Additionally, about a quarter of adults chose not to fill a prescription entirely, and roughly one in five resorted to cutting pills in half or skipping doses altogether. In total, over four in ten adults reported engaging in at least one of these cost-saving measures over the past year—continuing an upward trajectory documented in previous tracking polls.
These coping strategies are heavily concentrated among middle- and lower-income households. Approximately half of adults in households earning under $40,000, as well as those earning between $40,000 and $90,000, admitted to not taking their medications as prescribed due to cost concerns. This compares to about three in ten adults in households with incomes of $90,000 or more.
Uninsured individuals under 65 are similarly strained, with nearly six in ten reporting altered medication usage due to cost. Demographic divides also appear prominently here, with nearly half of women and over half of Black adults reporting that they have taken measures to reduce medication expenses.
Health Insurance Cost Ratings and Long-Term Debt
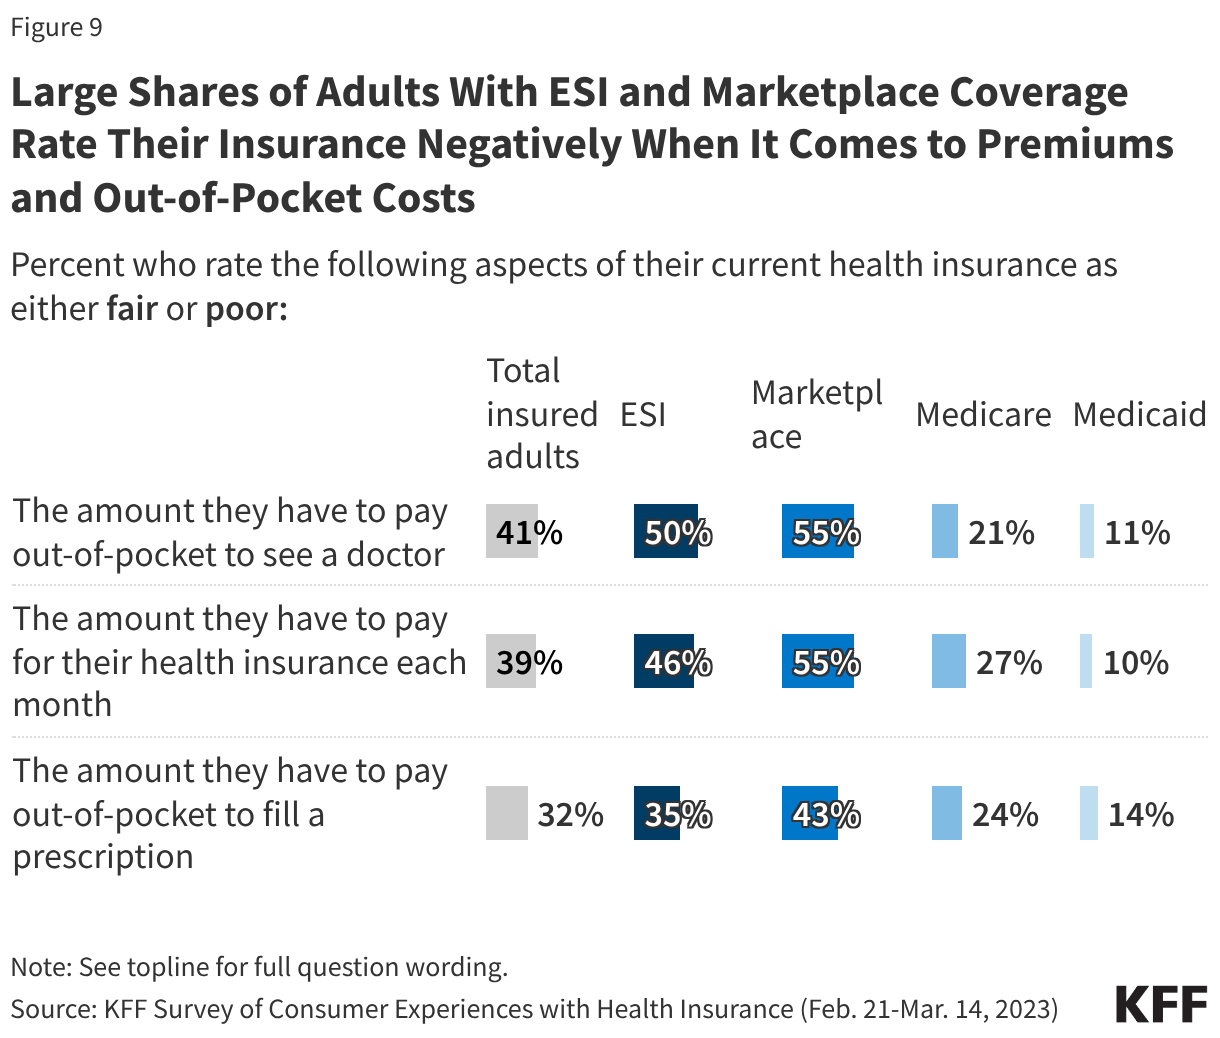
While health insurance provides a vital financial buffer, premiums, deductibles, and cost-sharing mechanisms frequently generate substantial financial friction. Most insured adults maintain generally favorable views of their coverage regarding specific routine encounters, with a majority rating their insurance as good or excellent concerning out-of-pocket prescription costs, doctor visit copays, and monthly premiums. However, at least three in ten policyholders rate their insurance as fair or poor across these same metrics, and perceptions vary significantly depending on the structure of their coverage.
Individuals enrolled in private plans—whether obtained through an employer or a state Marketplace—tend to express more negative views regarding monthly premiums, doctor visit out-of-pocket expenses, and prescription copays compared to those enrolled in Medicare or Medicaid. Conversely, Medicaid enrollees generally report fewer affordability grievances, largely due to structural protections regarding premiums and nominal copays.
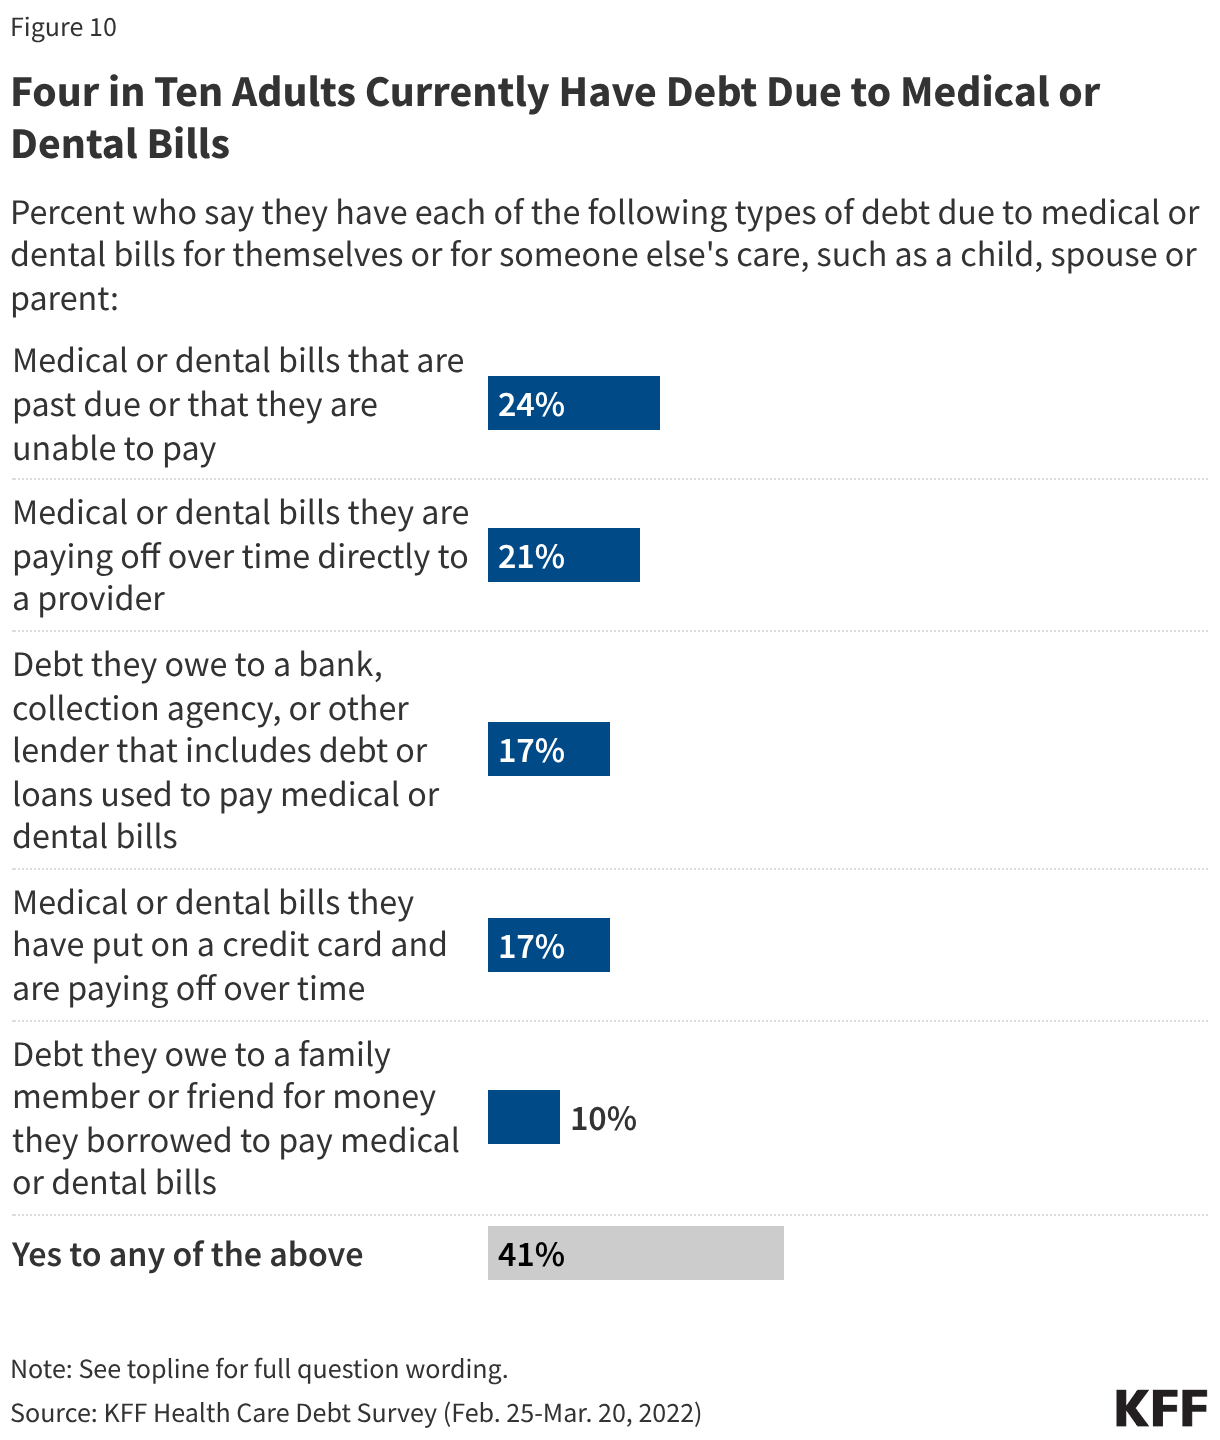
This underlying financial strain frequently matures into long-term debt. Comprehensive investigations into health care debt have revealed that roughly 41% of U.S. adults carry some form of debt resulting from medical or dental bills for themselves or dependents. This includes past-due balances, payment plans directly with providers, loans taken from financial institutions, credit card balances accrued for medical care, and money borrowed from friends or family members.
Compounding this reality, a vast number of Americans remain vulnerable to a single unforeseen health event. About half of U.S. adults stated they would be unable to readily pay an unexpected $500 medical bill out of pocket without resorting to borrowing, incurring credit card debt, or failing to pay it altogether. Women, lower-income earners, and Black and Hispanic adults are disproportionately represented among those who would struggle with such an emergency.
Among older Americans and those approaching retirement age, financial anxieties extend into long-term care and support services. Well over half of adults aged 65 and older expressed anxiety about affording nursing home care or assisted living facilities if the need arose, while half worry about paying for in-home support services such as paid nurses or aides. Among adults aged 50 to 64, these anxieties are even more pronounced, with over seven in ten expressing worry about affording residential care and professional in-home assistance in the future.
No comments yet. Be the first to join the conversation!